Does Tesla Model X Qualify for Section 179 and When Does It Apply?

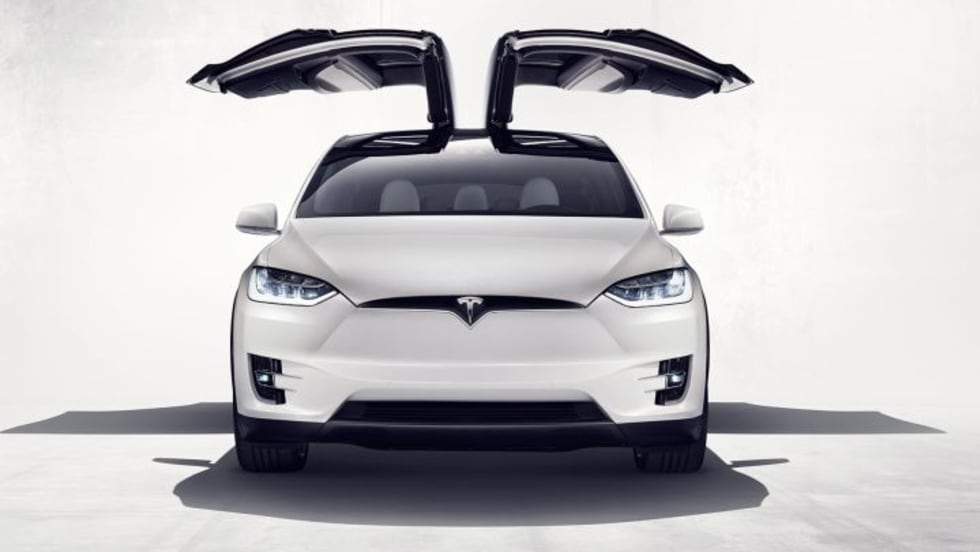
Yes, a Tesla Model X qualifies for the Section 179 deduction because its gross vehicle weight rating (GVWR) exceeds 6,000 pounds, which puts it in the heavy SUV category instead of the passenger automobile category. The deduction applies in the tax year the Model X is placed in service and driven more than 50% for business. For 2026, Section 179 covers up to $32,000 of the cost, and 100% bonus depreciation covers the remaining business basis, so the full business portion can come off in year one. Below we walk through the weight rule, the dollar limits, the timing rules, how the rest of the Tesla lineup compares, what changed now that Tesla has ended Model X production, and how to claim the deduction without creating a problem three years later.
Key Takeaways
- The Tesla Model X carries a GVWR between roughly 6,250 and 6,768 pounds depending on model year and configuration, which clears the 6,000 pound heavy SUV threshold.
- Section 179 caps the Model X deduction at $32,000 for 2026, and 100% bonus depreciation covers the remaining business basis with no cap.
- The vehicle must be placed in service by December 31 of the tax year you claim it. Ordering it or paying a deposit does not count.
- Business use must stay above 50% for the full five-year recovery period, or part of the deduction comes back as ordinary income.
- The Model Y, Model S, and Model 3 all sit under 6,000 pounds GVWR and face a $20,300 first-year ceiling for 2026.
- A used Model X still qualifies as long as it is new to your business, which matters now that Tesla ended Model X production on June 30, 2026.
- The federal clean vehicle credit ended for vehicles acquired after September 30, 2025, so the deduction is the remaining federal tax benefit.
Does a Tesla Model X Qualify for Section 179?
A Tesla Model X qualifies for Section 179 because its gross vehicle weight rating exceeds 6,000 pounds and it is used more than 50% in a trade or business. The weight rating is what moves the Model X out of the passenger automobile rules and into the heavy SUV rules. Passenger automobiles run into the depreciation ceilings of Internal Revenue Code Section 280F, which hold the first-year write-off to $20,300 for 2026 under IRS Revenue Procedure 2026-15. Heavy SUVs escape that ceiling entirely.
Escaping that ceiling changes the arithmetic by tens of thousands of dollars on a single purchase. A business owner who assumes the Model X is just another luxury car and schedules it over five years gives up most of the first-year benefit. We see this misclassification often in tax planning reviews, and correcting it usually costs nothing beyond amending the depreciation schedule.
The qualification itself rests on three conditions, and all three have to hold at once. The vehicle must carry a GVWR above 6,000 pounds. It must be used more than 50% for legitimate business purposes during the tax year. It must be placed in service during the year you claim the deduction. Miss any one of those and the deduction either shrinks or disappears, which is why the weight rating is only the starting point.
Is the Tesla Model X Over 6,000 Pounds?
Yes, the Tesla Model X is over 6,000 pounds by gross vehicle weight rating, though not by curb weight. Published GVWR figures for the Model X run from about 6,250 pounds on recent model years to 6,768 pounds on the original 2015 and 2016 cars, with manufacturer data on 2023 and 2025 vehicles showing roughly 6,525 pounds. Curb weight sits much lower, between 5,152 and 5,441 pounds depending on trim, which is exactly why the two numbers get confused.
Curb weight measures the empty vehicle. Gross vehicle weight rating measures the maximum safe operating weight of the vehicle plus passengers, cargo, and accessories, and it is set by the manufacturer. Every published GVWR figure for the Model X clears 6,000 pounds, but the spread between 6,250 and 6,768 pounds is wide enough that you should never rely on a number you read online.
How Do You Verify Your Tesla Model X GVWR?
You verify your Tesla Model X GVWR on the federal certification label inside the driver's side door jamb. That label is required on every vehicle sold in the United States, it lists the rating in pounds, and it reflects your exact configuration rather than a generic trim average. Photograph it the week you take delivery and keep the photo with your purchase documents permanently.
Two backup sources work if the label is damaged or unreadable. The owner's manual lists weights and capacities by trim, and a VIN lookup through the manufacturer returns the specification for your individual car. Neither carries the same evidentiary weight as the door jamb photograph, which is the document an examiner asks for first.
Why GVWR Matters More Than Curb Weight
GVWR matters more than curb weight because Section 280F applies two different weight tests to two different vehicle categories. Passenger automobiles are tested on unloaded curb weight at a 6,000 pound threshold. Trucks and vans, which includes sport utility vehicles built on a truck classification, are tested on gross vehicle weight rating at the same 6,000 pound threshold. The Model X is measured under the second test.
That second test is also why the Department of Transportation classification carries weight in a dispute. The Model X is classified as a non-passenger automobile because of its three-row seating configuration and flat-folding interior, which supports treating it as a truck for depreciation purposes rather than as a car. Taxpayers have had this deduction challenged and reversed on exactly this point, so the combination of a door jamb photograph and the manufacturer specification is worth assembling before you file rather than after.
How Much Can You Write Off on a Tesla Model X?
You can write off up to $32,000 of a Tesla Model X under Section 179 for the 2026 tax year. That $32,000 figure is the heavy SUV sub-limit, which applies to every vehicle rated between 6,001 and 14,000 pounds GVWR that is primarily designed to carry passengers on public roads. It is set by Internal Revenue Code Section 179(b)(5) and adjusted annually for inflation by the IRS.
The sub-limit has climbed steadily. IRS revenue procedures set it at $28,900 for 2023, $30,500 for 2024, $31,300 for 2025, and $32,000 for 2026. Note that some manufacturer-published tax guidance still quotes the 2025 figure of $31,300, so confirm the year you are actually filing for before you build a projection. The broader 2026 Section 179 limit of $2,560,000 applies to your total equipment purchases for the year, not to any single vehicle.
One limitation catches newer businesses off guard. Section 179 cannot create or increase a net operating loss. Your deduction is capped at your taxable business income for the year, with the excess carried forward. A practice that buys a Model X in its first profitable quarter may find the $32,000 is partly deferred, which is a planning question worth answering before the purchase rather than at filing.
Can You Combine Section 179 and Bonus Depreciation on a Tesla Model X?
Yes, you can combine Section 179 and bonus depreciation on a Tesla Model X, and combining them is how the full business cost comes off in year one. Section 179 is applied first up to the $32,000 heavy SUV cap, that amount reduces your basis, and 100% bonus depreciation then covers whatever basis remains with no cap of its own.
Bonus depreciation carries no cap because Internal Revenue Code Section 168(k) does not contain a heavy SUV sub-limit. The One Big Beautiful Bill Act, signed July 4, 2025 as Public Law 119-21, restored the rate to 100% permanently for qualifying property acquired after January 19, 2025. That reversed the scheduled phase-down, which had dropped the rate to 80% in 2023 and 60% in 2024 and was set to fall to 40%. The mechanics of stacking bonus depreciation on top of a Section 179 election work the same way on any qualifying business vehicle.
Run the numbers on a Model X acquired for $95,000 and used 100% for business. Section 179 takes the first $32,000. The remaining basis of $63,000 is deducted in full under 100% bonus depreciation. Total first-year deduction: $95,000. At 80% business use on the same vehicle, the deductible basis drops to $76,000, Section 179 still takes $32,000, and bonus covers the remaining $44,000.
The difference between the Model X and the rest of the Tesla lineup comes down entirely to that weight rating. The table below applies the 2026 limits published by the IRS in Revenue Procedure 2025-32 and Revenue Procedure 2026-15 across the four models.
Do Tesla Model Y, Model S, and Model 3 Qualify for Section 179?
The Tesla Model Y, Model S, and Model 3 qualify for Section 179 as business property, but none of them receives heavy SUV treatment because all three sit under 6,000 pounds GVWR. That puts them inside the Section 280F passenger automobile ceiling, which holds the combined first-year deduction to $20,300 for 2026 no matter how much Section 179 or bonus depreciation you elect.
The $20,300 ceiling is itself the product of two numbers. Revenue Procedure 2026-15 sets the base first-year limit at $12,300, and Section 168(k)(2)(F)(i) adds a fixed $8,000 whenever bonus depreciation applies to the vehicle. The ceiling then steps down to $19,800 in year two, $11,900 in year three, and $7,160 for each year after that until basis is recovered.
Practically, that means a $60,000 Model Y bought for business recovers its cost over roughly five to seven years, while a $95,000 Model X can recover its full business cost in one. The Model X is the only vehicle in the Tesla lineup that crosses the threshold, which is why the question gets asked about the Model X specifically and not about the rest of the lineup.
What Vehicles Are Eligible for the Section 179 Deduction in 2026?
Vehicles eligible for the Section 179 deduction in 2026 fall into three tiers, and the tier is determined by weight rating and body configuration rather than by price or fuel type. Electric drivetrains receive no special treatment and no penalty, so a Model X is evaluated against the same weight rules as a gasoline SUV.
- Full expensing tier. Vehicles rated above 14,000 pounds GVWR, cargo vans with no passenger seating behind the driver, and pickup trucks with a cargo bed of at least six feet. These are deductible up to the full $2,560,000 Section 179 limit for 2026.
- Heavy SUV tier. Vehicles rated between 6,001 and 14,000 pounds GVWR that are primarily designed to carry passengers. Section 179 is capped at $32,000, with 100% bonus depreciation available on the balance. The Model X sits here, alongside vehicles like the Toyota Sienna, the Cadillac Escalade, and the Chevrolet Suburban.
- Passenger automobile tier. Cars with an unloaded weight of 6,000 pounds or less, and SUVs, trucks, and vans rated at 6,000 pounds GVWR or less. First-year deductions are held to $20,300 for 2026.
No official IRS list of qualifying vehicles exists, which surprises people. Eligibility is verified vehicle by vehicle from the certification label, because gross vehicle weight rating shifts with trim level, battery configuration, and factory options on the same nameplate. The same three-tier logic also governs equipment used in other asset classes, including items placed in service on rental property.
When Does the Section 179 Deduction Apply to a Tesla Model X?
The Section 179 deduction applies to a Tesla Model X in the tax year the vehicle is placed in service, not the year it was ordered, financed, or paid for. For a calendar-year business, the Model X must be delivered and available for business use by December 31 to produce a deduction on that year's return.
That December 31 line is firm, and it is the single most common timing mistake on vehicle deductions. A Model X ordered in November with a deposit paid in December but delivered in January produces a deduction for the following tax year. The money left your account in one year and the deduction landed in the next, which can scramble a projection built around offsetting a high-income year.
What Does Placed in Service Mean for a Tesla?
Placed in service means the Tesla is ready and available for its intended business use, not simply owned. Readiness requires delivery, title transfer, registration, and insurance, so that the vehicle could be driven to a client meeting the moment the business needs it. Ownership on paper with the car still sitting at a delivery center does not satisfy the standard.
The documentation that proves readiness is ordinary and easy to assemble. Keep the delivery receipt with its date, the title or bill of sale, the registration, and the first dated entry in your mileage log. New entities should also keep the formation documents showing the business existed on the placed-in-service date, since a deduction claimed before the entity's business formation date invites an easy adjustment.
Can You Finance a Tesla Model X and Still Take Section 179?
Yes, you can finance a Tesla Model X and still take Section 179 on the full qualifying purchase price in year one. The deduction is based on the cost of the asset, not on what you paid out of pocket during the year, so a down payment of $10,000 on a $95,000 vehicle still supports a deduction measured against the $95,000 basis.
Lease-to-own arrangements follow the same logic as long as the structure is a conditional sale that transfers ownership to you. A true operating lease is different: lease payments are deducted as they are made, subject to an income inclusion amount on high-value vehicles, and Section 179 does not apply because you never take title. Reading the contract matters more than reading the marketing material attached to it.
How Much Business Use Does a Model X Need for Section 179?
A Model X needs more than 50% qualified business use for Section 179 to apply at all. At or below 50%, Section 179 and bonus depreciation are both unavailable and the vehicle moves to the slower Alternative Depreciation System. Above 50%, the deduction is prorated by the actual business percentage: 80% business use on a $95,000 vehicle produces $76,000 of deductible basis.
Vehicles are listed property under Internal Revenue Code Section 280F(d)(4), which triggers a higher substantiation standard than most business expenses. IRS Publication 463 requires contemporaneous records, meaning entries made at or near the time of each trip. A log reconstructed in March from calendar memory does not meet the standard, and it is the first thing an examiner tests. Founders in our startups practice get the most value from a tracking app that timestamps automatically, because the discipline fails fastest in the busiest quarters.
A defensible log carries five elements for every business trip:
- The date of the trip
- The destination, by address or by route
- The business purpose, stated specifically rather than as a generic label
- Miles driven for that trip
- Odometer readings at the start and end of the tax year
Two categories of driving trip people up. Commuting between home and a regular work location is personal mileage, no matter who owns the vehicle. Errands run during a commute count only for the additional miles the errand added, not for the whole trip.
What Happens If Business Use Drops Below 50%?
If business use drops below 50% during the recovery period, the IRS recaptures the depreciation you claimed above what straight-line depreciation would have allowed, and that recaptured amount is reported as ordinary income. Recapture is the reason a Section 179 vehicle is a multi-year commitment rather than a one-year decision.
Vehicles carry a five-year MACRS recovery period, so the business-use test applies in each of those five years and not just in the first one. Three events trigger recapture: business use falling to 50% or less, conversion of the vehicle to personal use, or disposal before the recovery period ends. The rules around the five-year recovery period govern all three.
Selling early produces the sharper version of the same problem. A Model X fully expensed in year one has an adjusted basis of zero, so the entire sale price becomes gain, and that gain is ordinary income under Internal Revenue Code Section 1245 rather than long-term capital gain. Sell a fully expensed vehicle for $60,000 in year three and $60,000 is taxed at your marginal rate. You still come out ahead of a five-year schedule in most cases, but the margin narrows enough that the exit should be modeled before the purchase. Building the hold period into a broader tax strategy is what separates a clean deduction from an expensive surprise.
Does a Used Tesla Model X Qualify for Section 179?
Yes, a used Tesla Model X qualifies for Section 179 as long as it is new to your business. Section 179 requires that the property be new to the taxpayer, not that it come from a factory, so a pre-owned Model X purchased from an unrelated seller receives the same $32,000 cap as a new one.
Bonus depreciation follows the same principle. Used property has been eligible for 100% bonus depreciation since 2018, provided you did not previously own or use the asset and did not acquire it from a related party. The same treatment applies across asset classes, which is why a business can expense used equipment on the same terms as new equipment.
The related-party restriction is where these deals fail. Selling a Model X you already own personally into your own LLC does not create a new deduction, because you previously used the vehicle. Purchases from a spouse, parent, child, grandparent, or an entity you control are also disqualified. An arm's-length purchase from a dealer or an unrelated private seller is clean.
What Tesla Ending Model X Production Means for the Deduction
Tesla ending Model X production means the used market and remaining dealer inventory are now the two routes to a qualifying vehicle. Tesla announced the wind-down on its fourth-quarter 2025 earnings call on January 28, 2026, the final cars left the Fremont line in late May, and the company logged June 30, 2026 as the official end of production after roughly 610,000 combined Model S and Model X deliveries across 14 years.
The tax treatment did not change when production ended. A Model X acquired in 2026 is evaluated on its gross vehicle weight rating, its business use percentage, and its placed-in-service date, exactly as it would have been in 2024. What changed is availability, and availability affects timing. A buyer who needs the vehicle placed in service by December 31 now has less control over delivery dates than a buyer ordering from an active production line, which makes the December 31 deadline a real planning constraint rather than a formality.
Is the Tesla Model X Eligible for a Tax Credit?
No, the Tesla Model X is no longer eligible for the federal clean vehicle tax credit. The One Big Beautiful Bill Act ended the Internal Revenue Code Section 30D credit of up to $7,500 for vehicles acquired after September 30, 2025, so a Model X acquired in 2026 receives no federal purchase credit.
Losing the credit does not reduce the deduction, and the two were never interchangeable. A credit reduces tax dollar for dollar. A deduction reduces taxable income, so its value depends on your marginal rate. With Section 30D gone, Section 179 and bonus depreciation are the remaining federal tools for a business buyer, and on a vehicle in the Model X price range the deduction was always the larger of the two.
One adjacent provision causes confusion worth clearing up. The same legislation created a deduction of up to $10,000 per year for interest on loans used to buy new personal vehicles under 14,000 pounds GVWR with final assembly completed in the United States, purchased after December 31, 2024 and before January 1, 2029, phasing out above $100,000 of modified adjusted gross income for single filers and $200,000 for joint filers. That provision covers personal use vehicles only. It does not apply to a business Model X and it does not stack with Section 179.
How Do You Claim the Section 179 Deduction on a Vehicle?
You claim the Section 179 deduction on a vehicle by filing Form 4562 with the tax return for the year the vehicle was placed in service. Form 4562 is where the election is actually made, and Section 179 is not automatic: without the form, there is no election. Bonus depreciation works the opposite way and applies by default unless you formally elect out for the entire asset class.
The sequence below is the order we work through on a Model X, and following it in order prevents the arithmetic errors that show up when people stack the deductions backward.
- Confirm the GVWR. Photograph the federal certification label in the driver's door jamb and file the image with the purchase documents.
- Confirm the placed-in-service date. Delivery, title, registration, and insurance all in hand, with the date documented.
- Calculate business use percentage. Business miles divided by total miles for the year, supported by the contemporaneous log.
- Apply the percentage to cost. Purchase price multiplied by business use percentage produces the deductible basis.
- Elect Section 179 first. Up to $32,000 for 2026, and no more than your taxable business income for the year.
- Apply 100% bonus depreciation to the remainder. The basis left after the Section 179 election is deducted in full.
- File Form 4562. Part I reports the Section 179 election, Part II reports bonus depreciation, and both have to tie to your asset schedule.
- Track the asset for five years. Record business use annually so recapture never arrives unannounced.
Entity structure affects step four more than most owners expect. When the business owns the vehicle outright, every mile is business mileage by default and personal use is reported as a fringe benefit on the owner's W-2 instead of reducing the deduction. For pass-through entities, the Section 179 dollar limit and the income limit are applied at the entity level and again at the owner level, so basis matters, and the choice between an LLC and an S Corp election changes how the deduction reaches your personal return. Working the vehicle decision into year-end planning rather than treating it as a standalone purchase is what makes the structure line up.
Does Your State Follow the Federal Section 179 Deduction?
Your state may not follow the federal Section 179 deduction, and the gap can be substantial. Federal treatment is uniform across the country, but state conformity is decided state by state, so the same Model X can produce a full first-year deduction federally and a fraction of that amount on a state return.
Florida is favorable on both counts for most owners. The state levies no individual income tax, so a sole proprietor, partner, or S corporation shareholder keeps the full federal benefit with no state adjustment to compute. Florida corporate income tax is the exception: C corporations must add back federal bonus depreciation and recover it over seven years, which creates a timing difference rather than a permanent loss. For the businesses we work with around Miami, the entity type usually settles the question in a single conversation.
Two large states are far more restrictive. California caps Section 179 at $25,000 and does not conform to bonus depreciation at all, so a vehicle fully expensed federally still depreciates over five years on the state return. New York disallows Section 179 entirely on SUVs rated above 6,000 pounds for personal income tax purposes, which reaches the Model X directly. Businesses operating across state lines need parallel depreciation schedules from year one, and that recordkeeping is part of what ongoing Virtual CFO support handles rather than something to reconstruct at filing.
Frequently Asked Questions
Why Is Tesla Discontinuing the Model X?
Tesla is discontinuing the Model X to repurpose its Fremont, California production line for Optimus humanoid robots. Elon Musk announced the decision on the company's fourth-quarter 2025 earnings call on January 28, 2026, describing the retirement of the Model S and Model X programs as an honorable discharge. Tesla has said it will continue supporting existing owners with parts, service, and software after production ends.
Will There Be a 2026 Tesla Model X?
There was a 2026 Tesla Model X, but production of it ended. The final vehicles left the Fremont assembly line in late May 2026, with June 30, 2026 recorded as the official end-of-production date, closing an 11-year run for the nameplate. Remaining new inventory and the used market are the only routes to a Model X now, and both qualify for the deduction on identical terms.
What Is the Life Expectancy of a Tesla Model X?
The life expectancy of a Tesla Model X comfortably exceeds the five-year MACRS recovery period that governs the deduction, which is the number that matters for tax purposes. Vehicles are depreciated over five years regardless of how long they physically last, so a Model X kept for ten years still finishes its depreciation schedule in year five. Holding the vehicle through that full period is what avoids early-disposal recapture.
Does the Tesla Model X Hold Its Value?
Whether the Tesla Model X holds its value matters for the deduction mainly through the recapture rules rather than as a resale question. A vehicle fully expensed in year one carries an adjusted basis of zero, so any amount you sell it for becomes gain, and that gain is taxed as ordinary income under Section 1245 up to the depreciation you previously claimed. A higher resale price produces a larger recapture, which is why the sale year deserves its own projection.
Can an LLC or S Corp Own the Tesla Model X?
Yes, an LLC or S Corp can own the Tesla Model X, and entity ownership is often the cleaner structure. The entity purchases, insures, and operates the vehicle, all mileage is business mileage by default, and any personal use is valued and reported as taxable compensation on the owner's W-2. Payments should flow through the business account rather than mixing personal funds, since commingling is what makes an otherwise valid deduction hard to defend.
Can You Take Section 179 on a Leased Tesla Model X?
You cannot take Section 179 on a true operating lease of a Tesla Model X, because the deduction requires that you own the asset. Lease payments are deducted as operating expenses instead, reduced by an income inclusion amount on higher-value vehicles. A lease-to-own or conditional sale arrangement that transfers title to you is treated as a purchase, so Section 179 does apply in that case.
How Long Do You Have to Keep a Section 179 Vehicle?
You have to keep a Section 179 vehicle above 50% business use for its full five-year recovery period. Selling it, converting it to personal use, or letting business use fall to 50% or less inside those five years triggers recapture of the depreciation you claimed above straight-line, reported as ordinary income. Holding the vehicle through the complete five years is the simplest way to keep the entire first-year deduction intact.
The Bottom Line
A Tesla Model X qualifies for Section 179 because its gross vehicle weight rating clears 6,000 pounds, which keeps it out of the $20,300 passenger automobile ceiling that catches the Model Y, Model S, and Model 3. For 2026, that qualification is worth up to $32,000 under Section 179 plus 100% bonus depreciation on the remaining business basis, which can take the full business cost off in a single year. The deduction applies in the tax year the vehicle is placed in service, requires more than 50% business use, and holds you to that threshold for five years.
The purchase date, the delivery date, the entity that holds the title, and the state you file in all change the result, and they are easier to arrange before the vehicle is in the driveway than after the return is filed. Our Miami office works with business owners in every state on decisions exactly like this one. If you are weighing a Model X or any heavy vehicle for your business, we are glad to look at the numbers with you. Reach out to NR CPAs & Business Advisors or call (305) 872-3096.