



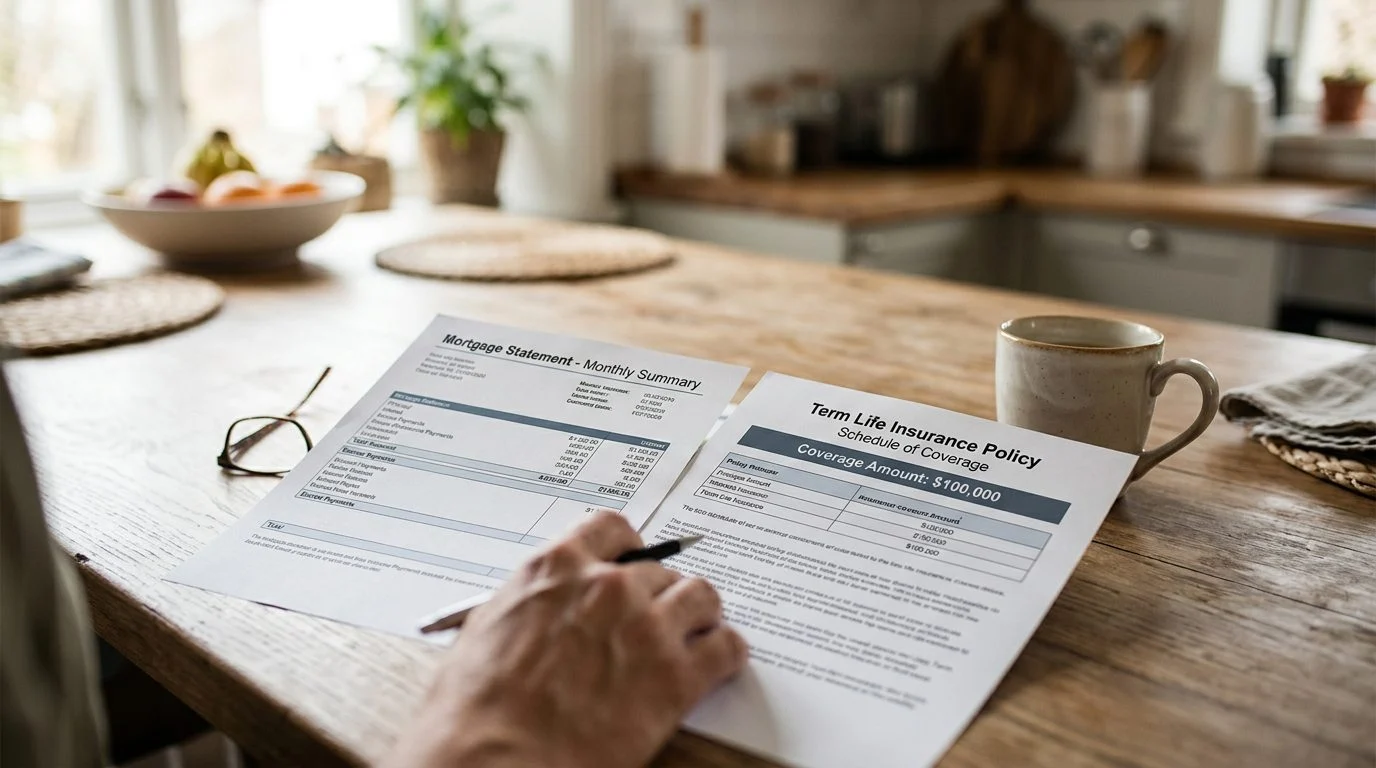
Life Insurance Guide | Miami, Florida
What Shapes the Monthly Cost of $100,000 Life Insurance
There is no single monthly price for a $100,000 policy. Insurers set the premium after underwriting, so the same coverage amount can carry different costs. Learn the factors behind the number, then call us today to start a coverage review.
By Nischay Rawal · Published October 16, 2026
There is no single answer to how much does a $100,000 life insurance policy cost per month. The premium is set by the insurer after underwriting, which is the review of your application. Two people can ask for the same $100,000 and receive different monthly premiums. This guide explains what shapes that number, so you can ask sharper questions. It is general information, not a quote or tax advice.
Why there is no single monthly price for a $100,000 policy
The monthly premium is a variable figure, not a price on a shelf. Insurers set it after they review the application, the policy type, and the person being insured. The same face amount can carry different premiums from one insurer to another, and from one applicant to the next.
That matters when you’re researching for someone else. Many people start this search during a hard change, such as a spouse’s illness, a parent’s aging, a new mortgage, or a business partner’s exit. In that moment, one number can feel like an answer. It usually isn’t.
Premium figures depend on the insurer, the policy, and the individual’s circumstances. Treat any dollar figure you read online as an example for someone else, not a quote for you. The rest of this page explains the variables, so you can see what moves the number.
If you're weighing this after a diagnosis in your family or a partner's decision, you don't have to sort out the numbers alone. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What a $100,000 death benefit means in plain words
The death benefit is the amount the policy pays when the insured person dies, if the policy is in force and the claim is approved. The face amount is the coverage figure stated on the policy. A $100,000 face amount is a chosen number, not a calculated need.
Benefit payment depends on the policy terms, the insurer’s review, and the facts of the claim. No policy can promise payment in every case, so read the contract closely.
With whole life, a policy loan or withdrawal can reduce the death benefit. Loans can also reduce cash value. Loan terms depend on the policy. The Florida Department of Financial Services guide covers policy loans and other basic features for consumers.
How term and whole life change the monthly premium
Term life insurance covers a set period. Its premium depends on the level-premium period stated in the specific policy and contract, so ask how long that period lasts. The NAIC Life Insurance Buyer’s Guide explains term and permanent coverage side by side.
Whole life insurance is permanent coverage. It may build cash value under the contract. That value includes guaranteed and non-guaranteed amounts. Dividends, where a policy pays them, are not guaranteed. In general, whole life premiums are often higher than term premiums for the same face amount, but this depends on the insurer and the policy.
Whole life is life insurance. It is not a savings plan, an investment, or a tax-deferred vehicle.
Tax treatment depends on the policy, the contract, and the individual’s situation. Under the federal tax code on death benefits, amounts paid because of death are generally excluded from gross income, subject to exceptions. This is general information, not tax advice.
Factors that move the monthly premium
Age, health answers, tobacco use, term length, and policy type are the main factors. Each one is a variable input the insurer weighs, not a fixed surcharge.
Age. Age at application is a rating factor. Under Florida’s misstatement-of-age rule, if the age was stated wrong, the benefit is what the premium would have bought at the correct age. Get the age right on the application.
Health. Health questions are required, and issuance depends on insurability. Your answers or any exam results can change the rate class the insurer assigns.
Tobacco and nicotine. Insurers often rate tobacco users differently, and the difference varies by insurer. Don’t assume one standard surcharge applies everywhere.
Term length and policy type. A longer level-premium period, or a permanent policy, changes the cost picture. Each insurer prices these differently.
Family history, occupation, and riders. These are weighed against your application. Each rider adds its own cost and terms.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What age does to the picture for a 60-year-old applicant
Age can change both the premium and the amount of coverage a person may consider. It is not a fixed multiplier that works the same way for every insurer.
For an older applicant, the premium is a variable figure. It depends on the insurer, the policy, underwriting, and health. Older applicants may face more underwriting questions, and approval is not assured.
Age also shapes the planning side. A coverage amount that fits one stage of life may not fit another, depending on debts, dependents, and obligations.
A 60-year-old’s premium is not a number you can read off a chart and apply to your own case. The insurer’s review decides it.
Is $100,000 a good amount? A starting point, not a formula answer
$100,000 is a starting point, not a recommended or sufficient amount. It’s a round figure, not a calculated need.
Some planners use rules of thumb, such as a multiple of annual income. These are widely discussed starting points, not definitive answers. They don’t account for your full situation.
The right amount depends on what you’re protecting. Household expenses, debts and a mortgage, dependents, and business obligations all count. A business owner may also look at key person or buy-sell needs, which depend on the business and its agreements.
This page is general information. It does not determine the amount you need, and our team does not claim a special ability to set that amount for you.
What happens to the premium after 10 years and beyond
Some policies have a level-premium period, and premium terms depend on the policy and contract. After that period, the premium may change under the policy’s terms. Ask the insurer to show that schedule in writing.
Whole life cash value includes guaranteed and non-guaranteed amounts. Dividends, where a policy pays them, are not guaranteed. Loans can reduce both cash value and the death benefit, and loan terms depend on the policy.
Florida rules also apply. Under Florida’s grace period rule, every policy must give at least 30 days to pay a premium after the first. The policy stays in force during that grace period, and the insurer may charge interest up to 8 percent per year. Under Florida’s incontestability rule, a policy is generally incontestable after two years in force, with exceptions such as nonpayment of premiums.
Bring these questions to your coverage review. Ask the insurer, in writing, about the level period, the premium after it, and how loans affect the policy.
Coverage review, review period, and next steps
The next step is a coverage review, a first meeting to look at your situation and the questions above.
Florida law sets a 14-day review period for life insurance policies (Fla. Stat. 626.99(4)), and how any specific policy applies depends on the issuing insurer and the policy’s terms. The Florida DFS guide also describes this review period, which is 14 days for a life insurance policy. Coverage, premiums, and benefits depend on the issuing insurer’s underwriting and the policy’s terms. Dividends are not guaranteed. No specific policy is named here, and the issuing insurer is named in any policy offered to you.
Quick answers
How much does a $100,000 life insurance policy cost per month? It depends on the insurer, the policy, and the individual’s circumstances. No single monthly figure applies to every reader.
Does a policy loan reduce the death benefit? It can. Loans can reduce cash value and the death benefit, and terms depend on the policy.
Is $100,000 enough? It is a starting point only. The right amount depends on what you’re protecting.
If you’re weighing this after a diagnosis in your family or a partner’s decision, you don’t have to sort out the numbers alone. Contact our team to set up a coverage review; insurance is offered through a licensed insurance agent, separately from the accounting practice.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
How to use this guide
General information only
This page explains how premiums are commonly shaped. It is not a quote, a recommendation, or tax advice. Your premium depends on the insurer, the policy, underwriting, and your circumstances.
Plain-language terms
Insurance terms such as underwriting, term length, and cash value are explained in everyday words so you can ask clearer questions.
Built for your household or business
Life insurance can protect families, and key person and buy-sell coverage can protect business continuity. Your coverage review focuses on what your situation needs to protect.
Next step: a coverage review
Contact NR CPAs & Business Advisors to schedule a first meeting. We will walk through the factors in this guide as they apply to you.
Important: insurance is offered separately
Insurance is offered through Nischay Rawal, a Florida-licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors. Actual premiums, coverage, and tax treatment depend on the insurer, the policy, and your individual circumstances.
Factors that commonly shape the monthly premium
Age and health
Insurers often review age and health history during underwriting. These factors can affect the premium offered, and the approval itself depends on the insurer's review.
Tobacco and lifestyle
Some insurers apply different rates to tobacco users. The size of any difference depends on the insurer and the policy, so ask about the specific rating in your case.
Term length or permanent coverage
A term policy and a whole life insurance policy are priced differently. Term premiums depend on the level-premium period stated in the contract, and whole life premiums depend on the policy design.
Policy features and riders
Optional riders and policy features can change the premium. Each feature should be reviewed against the policy's terms and limitations.


