



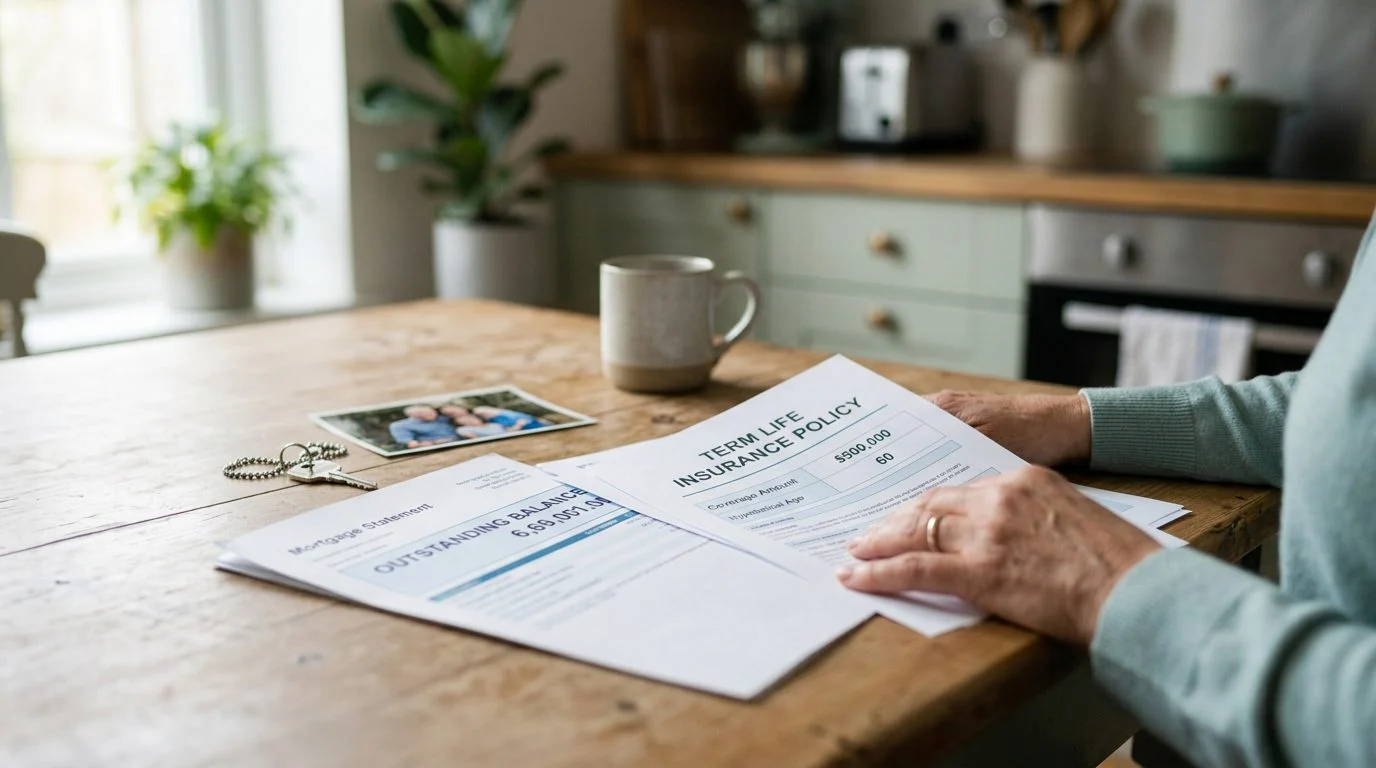
Life Insurance Guide | Florida
How Much Is a $500,000 Life Insurance Policy at 60?
A general look at what affects the cost of a $500,000 policy at age 60, and why the answer depends on your insurer, your policy, and your circumstances.
By Nischay Rawal · Published October 16, 2026
There is no single price for a $500,000 life insurance policy for a 60-year-old man. The premium depends on the insurer, the policy type, the health review, and how long the coverage lasts. This page explains those factors so you know which questions matter before any number means much.
Florida’s life insurance rules focus on helping buyers understand what they are buying. Fla. Stat. 626.99 says cost and benefit information should help buyers choose the most appropriate plan for their needs.
What a $500,000 Life Insurance Policy Means at Age 60
A $500,000 policy pays a $500,000 death benefit. It does not tell you what the policy costs to keep in force.
The face amount is the death benefit, the amount the policy pays when the insured dies. The premium is the payment you make to keep the policy in force. Those are two different numbers.
Insurers set premiums after underwriting. Underwriting means the insurer reviews your application and decides whether to issue coverage and at what premium. That review looks at age, health history, and tobacco use, along with the policy you choose.
No single figure applies to every 60-year-old man. Any premium you read about is illustrative. It may reflect different health, a different policy type, or a different insurer.

Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Why There Is No Single Price for This Coverage
Insurers price coverage using their own rates. The same face amount can cost different amounts from one company to another.
Factors insurers commonly review include:
- Age at application
- Health history and current medical conditions
- Tobacco use
- Sex, where state rules allow it to be considered
- Policy type, such as term or whole life
- Term length or the length of the premium period
- The face amount
- The rate class the insurer assigns after underwriting
Two applicants of the same age and face amount can land in different rate classes. The result depends on the carrier and the underwriting outcome.
Age errors matter too. Under Fla. Stat. 627.456, if the age or sex of an insured was misstated, the benefit is adjusted to what the premium would have bought at the correct age. That is why an accurate application matters.
Simple premium totals have limits too. Florida’s cost disclosure rules say a method that ignores the time value of money should not be used to compare two or more life insurance policies.
How Age 60 Changes Both Cost and the Amount Needed
Age 60 can change the premium, the policy types available, and the underwriting result. It can also change how much coverage a household needs.
Needs at 60 often differ from earlier years. Retirement timing may shift when income stops. A mortgage or other debt may still be open. A spouse may depend on a paycheck or a pension. Some men at this age own a business interest that needs funding for a buyout.
Term coverage that ends at a set age matches obligations that end at that age, such as a loan or a dependent’s schooling. It may not match an obligation that lasts longer. Whether the premium stays level depends on the level-premium period in the policy and contract. Level premiums are not promised for every policy.
For a deeper look at permanent coverage, read our whole life insurance guide. To compare structures side by side, see whole life vs term life for a 60-year-old.
If you may move outside the United States, see whether a US life insurance policy covers someone who moves back to India. Coverage terms depend on the policy and the insurer.
Term or Whole Life at a $500,000 Face Amount
Term premiums depend on the policy and the level-premium period stated in the contract. When that period ends, premiums and terms may change under the contract’s terms.
With whole life, cash value includes guaranteed and non-guaranteed amounts. Dividends, where a policy offers them, are not guaranteed. Whole life is life insurance. It is not a savings account, an investment, or a tax-efficient plan.
A policy loan can reduce both the cash value and the death benefit. Fla. Stat. 627.458 sets out policy loan rules. It says that if unpaid interest makes the debt equal or exceed the loan value, the policy can terminate after at least 30 days’ notice. That section does not apply to term policies.
Treatment depends on the policy, who owns it, and your situation. This is general information, not tax advice.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Using a Rule of Thumb as a Starting Point Only
A common rule of thumb starts with annual income. It is a general practice, not a formula from a regulator, and it is only a starting point.
Some planners begin with a multiple of annual income. They then adjust for debts, dependents, and savings. The rule gives a rough first step. It does not capture your full situation.
Several obligations can shift the right amount:
- A mortgage balance
- A business loan a family member would have to repay
- A spouse’s income needs
- Funding for a buy-sell agreement if a partner dies or leaves
Each one can call for a different amount. That is why a general rule cannot set one correct figure. We can talk through these general factors with you. We do not set a single correct amount from a formula.
What Happens Between the Question and the Policy
A fully underwritten application asks health questions. The insurer decides whether to issue coverage and on what terms.
Issue may depend on insurability. The application may also require medical records or an exam, depending on the insurer and the policy. Whether any benefit is paid depends on the policy terms and the insurer’s review. Nothing here promises payment.
Florida’s life insurance rules include a review period after delivery of a policy. For a life insurance policy, Florida law provides a 14-day review period, and the issuing insurer’s policy terms govern the details.
Future changes are not assured. Any future increase in coverage depends on insurability and the policy terms at that time. A term policy may offer a conversion option, but that depends on the policy terms and insurability when you convert.
Florida requires a license to solicit insurance, which includes describing premiums or advising on coverage. Fla. Stat. 626.9531 requires agents to tell prospective insureds that they act as insurance agents.
Talk Through Your Situation Before You Decide
If you’re researching this for a parent, a spouse, or a business partner, you may be facing a hard question on someone else’s behalf. A recent diagnosis in the family or a partner’s plan to retire can make the question urgent.
NR CPAs & Business Advisors is a Miami CPA firm. It helps families, professionals and business owners across the United States look at whole life, term, key person, buy-sell, estate planning, and NRI life insurance.
To talk through your own numbers and obligations, contact our team to request a coverage review with Nischay Rawal.
Insurance is offered through Nischay Rawal, a licensed insurance agent, separate from the accounting practice. Under Florida rules, you may review and return a life policy within 14 days after the policy is delivered.
Common questions
Is $500,000 coverage expensive at age 60?
The premium depends on the insurer, the policy, underwriting, and your circumstances. No single answer applies to every applicant.
Does whole life build cash value?
It may, under the contract. That value includes guaranteed and non-guaranteed amounts, and loans can reduce it and the death benefit.
Are death benefits taxable?
Treatment depends on the policy, ownership, and your situation, and exceptions apply (26 U.S.C. 101). This is general information, not tax advice.
Starting Points, Not Final Answers
Coverage amount
Rules of thumb, such as multiplying income, are only general starting points. The right amount depends on what is being protected, including debts, dependents, and business obligations.
Term or whole life
Term life insurance covers a set period. Whole life insurance may build cash value under the contract. That value includes guaranteed and non-guaranteed amounts, and loans can reduce both the cash value and the death benefit.
Age and health
Age and health can affect both premiums and whether a policy is issued. Health questions are required, and issue may depend on insurability.
Business and estate uses
Key person and buy-sell coverage, and policies used in estate planning, each have their own terms. Tax treatment depends on the policy, the business structure, and your particular situation.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
What Shapes the Premium
The insurer and the policy
Premiums differ by insurer and by policy type, form, and riders. Any figure depends on the specific contract.
Underwriting
Health history, medical records, and other underwriting factors are reviewed before a premium is set.
Term length and payment period
The length of coverage and how long premiums are payable both affect cost and depend on the policy.
Your overall plan
Coverage should fit your family, business, and cash flow.
Important Disclosures
This page is general information only and is not tax or legal advice. It does not quote premiums. Any premium, benefit, or tax result depends on the issuing insurer, the policy terms, underwriting approval, and your individual circumstances. Dividends are not guaranteed.


