



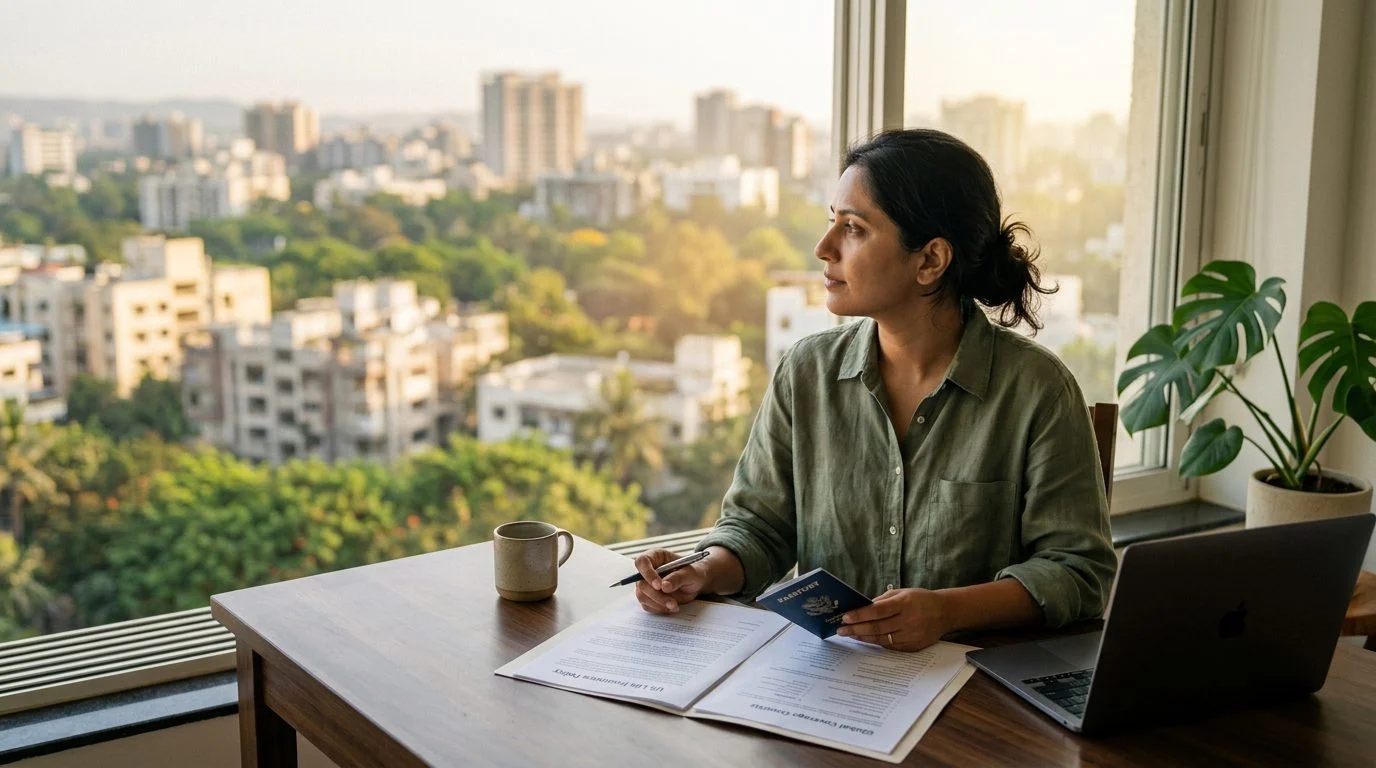
Life Insurance | Moving Abroad
Moving to India? Check How Your US Life Insurance Responds
Your policy's residence terms, premium payment options and insurer review all affect coverage after a move. Start with a coverage review with NR CPAs & Business Advisors.
By Nischay Rawal · Published October 16, 2026
You may be asking, does my US life insurance cover me if I move back to India? The short answer is that it depends on your policy contract, the insurer that issued it, and your own situation. Whether a move affects a policy depends on the policy’s residence, territory, or travel terms and on the insurer. It can, however, change how premiums, notices, and claims are handled.
This page explains what to check before you go. It is general information, not advice about your specific policy. Many families and business owners, including Indian-American households with ties to both countries, raise this question before a move.
The Short Answer: It Depends on Your Policy Contract
There is no single yes-or-no answer that fits every US life insurance policy. The policy form, the issuing insurer, and the wording of your contract decide what happens after you move.
General statements about whether coverage stays in force abroad can’t replace reading your own documents. Start with the policy form number, the face amount, and the premium schedule. Then find any section that discusses where the owner lives.
Whether a move affects coverage depends on the specific policy contract and the insurer. It also doesn’t automatically keep every feature the same. Some features, such as premium payment options or loan access, may change. Your task is to confirm which ones, in writing, before you leave.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Why Your Country of Residence Can Matter
Your country of residence can affect how an insurer administers your policy, even when the coverage itself stays in place. Some contracts include residence, territory, or travel terms. Those terms can shape notice requirements, payment options, and how a claim is reviewed.
Underwriting and servicing rules can also differ for policyholders who live outside the United States. The insurer decides how its own contract applies to a change of residence. You can’t assume the answer is the same for every carrier.
Find the clause that covers changes of address or residence. Note what notice it requires and how soon you must give it. Also check who is named as beneficiary, and where that person lives. Keep copies of every written confirmation the insurer sends you.
Paying Premiums While You Live in India
Premium payment can change after a move. The options you can use depend on your insurer and your policy, not on a general rule. Currency, bank routing, and payment timing are cash-flow questions. Plan them before you leave.
Ask which payment methods the insurer accepts from abroad. Ask how it handles currency conversion and which bank fees may apply. Then set a payment calendar so a premium doesn’t slip during the move.
If a premium is missed, your contract may allow a grace period. For life insurance policies governed by Florida law, Fla. Stat. § 627.453 addresses grace periods for premiums after the first, and the grace period and its terms depend on the statute and the policy. Whether the policy remains in force during a grace period, and whether the insurer may charge interest for those days, depends on the statute’s terms and the policy contract (Fla. Stat. § 627.453). Reinstatement terms depend on your contract.
Premium amounts and payment terms depend on the insurer, the policy, and your circumstances. How long your premium stays at the same level depends on the level-premium period set in your policy and contract.
How a Claim Could Be Handled From India
A beneficiary living in India may need to send documents the insurer requests. Those often include certified death records and identity documents. The exact list depends on the insurer, so ask for its claim checklist and keep it with your policy papers.
Payment of any death benefit depends on the policy terms, the insurer’s review, and underwriting. Timing and method of payment are not certain. For lump-sum proceeds under a policy Florida law governs, interest is payable from the date the insurer receives written due proof of death (Fla. Stat. § 627.4615).
They matter when a beneficiary or a relevant jurisdiction is sanctioned. The OFAC foreign beneficiary FAQ describes how those rules work. Ask the insurer how it handles foreign beneficiaries.
Tax and Reporting Questions to Raise (General Information)
This section is general information, not tax or legal advice. Tax treatment depends on the policy, the contract, applicable US and Indian rules, and your own situation.
Under Section 101 of the Internal Revenue Code, gross income does not include amounts received under a life insurance contract if such amounts are paid by reason of the insured’s death, except as otherwise provided in that section. Exceptions apply, and tax treatment depends on the policy and the individual’s circumstances. Interest paid on proceeds held by the insurer can be taxable. The IRS guidance on taxable proceeds explains that treatment varies with the circumstances.
Estate inclusion is a separate question from income tax. Federal law can include insurance receivable by the executor, and by other beneficiaries when the decedent held incidents of ownership, in the gross estate (IRC § 2042). Whether that applies to you depends on your facts.
Loans and withdrawals from a whole life policy can reduce both cash value and death benefit. Florida’s policy loan rules do not apply to term policies (Fla. Stat. § 627.458). Loan terms depend on your policy.
Reporting questions can come up for a policy held after a move. Add them to your checklist. The answers depend on your situation.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Term Versus Whole Life When Your Move Is Coming
Term life insurance covers you for a set period. Whether it can be renewed, and on what terms, depends on the specific policy and contract. Term coverage can end when its period ends.
Whole life insurance is life insurance that may build cash value under the contract. That cash value includes guaranteed and non-guaranteed amounts. Dividends, where a policy pays them, are not guaranteed. Loans can reduce both cash value and death benefit, and loan terms depend on the policy.
A move can affect each type differently. A term policy’s coverage period may end while you’re abroad. A whole life policy’s loan and cash value features may need more attention. Neither type is the right choice for everyone.
Avoid comparing premiums or projections across insurers as a shortcut. Your own policy’s numbers are the starting point for any review.
Questions to Bring to a Coverage Review
A coverage review is a first meeting to look at your own policy and situation. The answers depend on the insurer’s terms and underwriting, not on general rules.
Gather these items before the meeting:
- Insurer name and policy form number
- Face amount and premium schedule
- Residence, travel, and notice clauses
- Beneficiary designations and each beneficiary’s country of residence
- Any riders attached to the policy
- Grace period and reinstatement terms
- Loan and cash value provisions, if the policy has them
- Documents the insurer would need for a claim
Also write down your questions. Ask how premiums can be paid from India. Ask whether any term or cash value feature changes after a move.
Bringing Your Policy Questions to NR CPAs & Business Advisors
If you hold a US whole life or term policy and your move date is getting closer, contact NR CPAs & Business Advisors to set up a coverage review of your policy. Bring the contract and the items on the checklist above.
We can walk through what your own documents say about residence, premiums, and claims. We can’t say how your policy will respond to a move until we read the contract. Outcomes depend on the policy and insurer.
Please contact NR CPAs to request that coverage review.
Insurance Agent Disclosure and Required Notices
Frequently Asked Questions
Does my US life insurance cover me if I move back to India?
It depends on your policy contract, the insurer, and your situation. Read the residence clause and confirm how the insurer applies it.
Can I pay my premium from India?
It may be possible, but accepted payment methods depend on the insurer and the policy.
Is a life insurance death benefit taxable?
Federal law generally excludes death proceeds from gross income, but exceptions apply and treatment depends on your situation.
Is this page tax advice?
No. This page is general information only.
Agent and Insurance Disclosures
Insurance is offered through Nischay Rawal, acting as a Florida-licensed insurance agent, separately from the accounting practice.
Insurance is offered separately from the accounting practice of NR CPAs & Business Advisors. This page does not advertise a specific policy and quotes no premiums.
Florida law (Fla. Stat. 626.99(4)) gives the owner of a life insurance policy 14 days after delivery to review the policy and return it for a refund, as the statute provides. Coverage, premiums, and benefits depend on the issuing insurer’s underwriting and the policy’s terms. Dividends are not guaranteed, and cash value includes guaranteed and non-guaranteed amounts.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Questions to Raise Before You Relocate
Read the residence terms
Many policies include language about where the insured lives. Review your contract and ask how the insurer applies that language to a move abroad.
Confirm premium payments
Ask whether premiums can be paid from India and which methods the insurer accepts. The answer depends on the insurer and the policy.
Understand what changes
Coverage, premiums and benefits depend on the issuing insurer's terms, underwriting and your circumstances. Do not assume nothing changes after a move.
Separate general information from advice
This page is general information, not tax or legal advice. Your situation and your policy's terms determine the outcome.
Important
Do not assume your US life insurance continues unchanged after you move.
How We Can Help Before You Go
Coverage review
A coverage review is our first meeting. We look at your existing policy, its residence terms and how your plans may affect it.
Policy questions to the insurer
We help you organize the questions to put to your insurer so you understand how your specific contract applies.
Tax and cash-flow context
As a CPA firm, we can explain how a move may affect your household or business finances. Tax treatment depends on the policy and your situation.


