



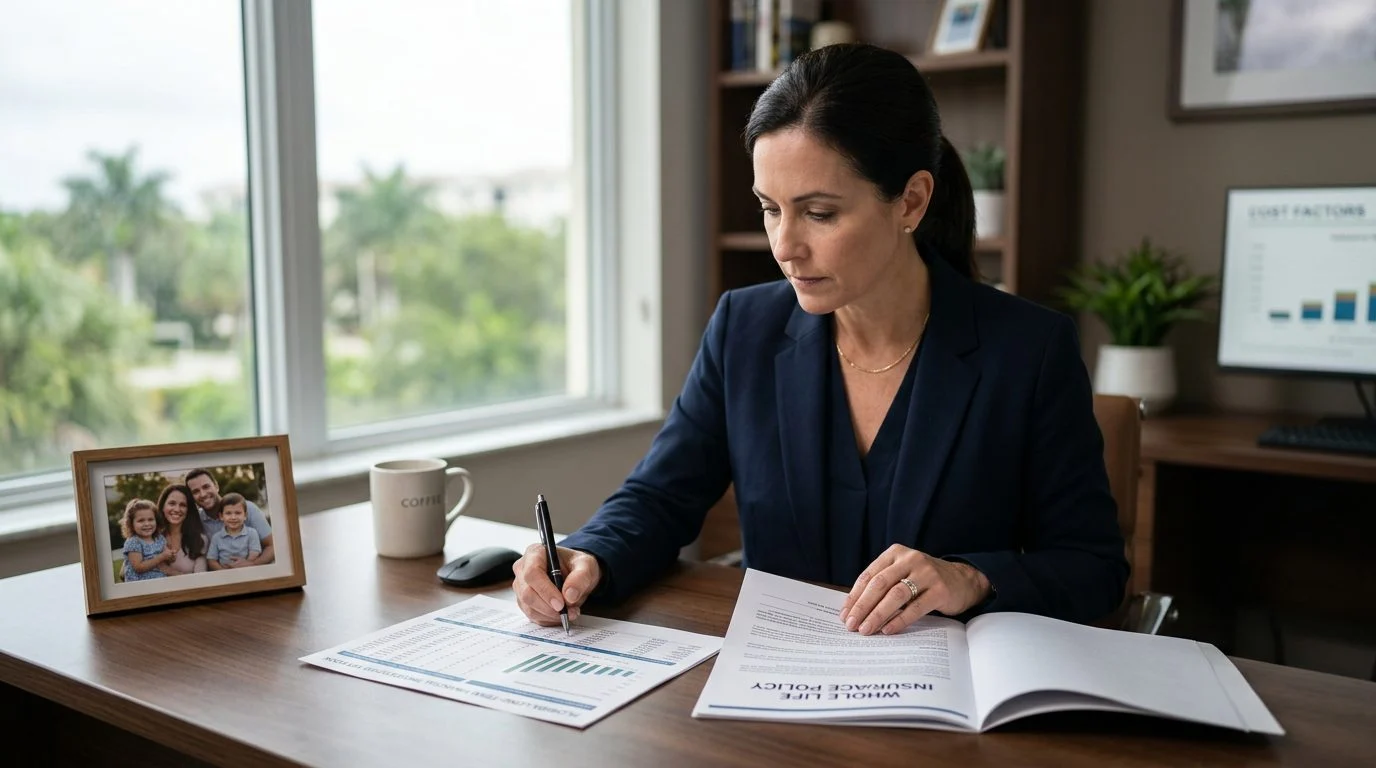
Whole Life Insurance | Florida
Whole Life Cost Per Month in Florida: What Sets It
There is no single monthly figure. The premium depends on the insurer, the policy, underwriting, and your circumstances. Here is what shapes it, and how a coverage review can help you plan.
By Nischay Rawal · Published October 16, 2026
There is no single monthly figure for whole life insurance. The premium depends on the insurer, the policy design, the face amount, the insured’s age and health, and how long premiums are scheduled to be paid. This page explains those factors in plain words. It is general educational information, not a quote, tax advice, or financial advice.
Why there is no single monthly figure for whole life
A whole life premium is not one number that applies to every household. Each insurer prices its policies under its own rules, and each policy is built differently. Treat any monthly amount as one piece of a larger picture.
Many readers start with a proposal already in hand. A relative, a business partner, or an earlier agent may have sent it. It is reasonable to ask what the monthly number covers. The answer is in the policy terms, not in the figure alone.
Ask for the full document. A monthly amount without the insurer’s name, the face amount, the premium period, and the limitations tells you very little. Nothing on this page is a price for any policy.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
The factors that set a whole life premium
The main drivers are the insurer, the policy design, the face amount, the insured’s age, health, and underwriting results, and the premium payment period. Riders and billing mode also change the bill.
Underwriting is the insurer’s review of health information. Issue may depend on insurability. An offered premium can differ from an early estimate after that review. Florida law addresses misstated ages: if an insured’s age was misstated, the amount payable is what the premium would have bought at the correct age, based on the insurer’s rate at date of issue, under Fla. Stat. § 627.456.
Age also affects how much coverage a household may want. Age is not a detail to skip.
A common starting point for coverage size is a multiple of income. This is only a rule of thumb. It does not set a premium or a required amount. The right amount depends on what is being protected.
Do not assume that any age-based cost difference or smoker surcharge applies to you. Those figures vary by insurer and must come from that insurer’s own proposal.
Level-pay and limited-pay whole life: how the payment period changes the bill
Level premium whole life is designed so the premium may stay level for the premium period stated in that specific policy and contract. Limited-pay whole life schedules premiums over a shorter stated period. Because the same protection is paid for over fewer years, the periodic payment is generally higher. Exact amounts depend on the insurer and the policy.
Whether a premium stays level or changes depends on the contract. Read the premium terms in the policy documents, not in a summary. A payment schedule may differ from what a sales conversation suggested.
Missed payments have rules too. Under Fla. Stat. § 627.453, Florida life insurance policies are subject to a grace period of not less than 30 days for paying premiums after the first. During that period the policy continues in force. Check the policy for how interest applies.
Monthly billing, payment modes, and total cost over time
Premiums may be billed monthly, quarterly, semi-annually, or annually. The billing mode changes each bill and the total paid over the years, depending on the insurer. Ask for the premium for each billing mode in writing.
Total premiums depend on the premium period, the face amount, and how long the policy stays in force. A policy that lapses early can leave premiums paid and coverage ended. There is no general total to quote.
Compare term and whole life by design, not by monthly figure. Under a cash-value policy, part of each premium may go toward the policy’s cash value, depending on the contract and the insurer. Premiums for term and cash-value policies depend on the insurer, the policy, underwriting and individual circumstances. FINRA explains that term covers a limited period, while whole life covers the insured’s life and includes a cash-value feature.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Cash value, loans, and dividends: what the premium does and does not promise
Cash value has guaranteed and non-guaranteed amounts, shown separately in the policy documents. The amounts depend on the contract and the insurer. You cannot reliably work out cash value from the premium alone.
Policy loans may be available once a policy has a cash surrender value and no premium is in default, under Fla. Stat. § 627.458. The insurer may deduct existing debt and accrued interest. A loan or withdrawal can reduce both the cash value and the death benefit. Loan terms depend on the policy. Cash value is not an emergency fund.
Dividends, where a policy offers them, are not guaranteed. Non-guaranteed amounts can change.
Whole life is life insurance that may build cash value. It is not a savings, retirement, or investment plan. Tax treatment depends on the policy and your situation. Under the rule in Internal Revenue Code § 101(a), gross income does not include amounts received under a life insurance contract if such amounts are paid by reason of the death of the insured, except as otherwise provided in that section, and treatment depends on the policy and the individual’s circumstances. A policy must also meet federal tests, such as the cash value accumulation test, to qualify as life insurance.
What a complete premium presentation must show, and the next step
A complete premium presentation shows the insurer’s name, the policy form number, and the type of plan next to the face amount and premium. It also shows the premium and payment period, any change in face amount or premium, the limitations and exclusions, and whether the policy is renewable, cancellable, or subject to age-based change.
Coverage, premiums, and benefits depend on the issuing insurer’s underwriting and the policy’s terms.
Insurance is offered through Nischay Rawal, acting as a Florida-licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors. An agent must clearly indicate that he or she is acting as an insurance agent, as Fla. Stat. § 626.9531 requires.
If you are reviewing a proposal a parent or partner received, you can contact NR CPAs & Business Advisors to discuss its terms in plain words at a coverage review. Our team can review the policy terms with you in a coverage review at NR CPAs & Business Advisors. Any fee for a coverage review is set out in writing before any work begins.
Common questions
How much does whole life cost per month?
There is no single figure. The premium depends on the insurer, the policy, underwriting, and your circumstances.
Does whole life cash value grow every year?
Cash value may build under the contract. It includes guaranteed and non-guaranteed amounts, so it does not grow on a fixed schedule.
Are whole life dividends guaranteed?
No. Dividends, where offered, are not guaranteed.
What Sets the Monthly Premium
The insurer and the contract
Each insurer prices whole life policies under its own rules, and the contract terms, riders, and payment schedule all affect the premium. Actual figures vary from one insurer and policy to another.
The face amount and policy design
The death benefit amount and how the policy is structured both influence the premium. Changes to face amount can change the premium.
Age and underwriting
Age, health history, and the underwriting process can affect whether a policy is issued and at what premium. Issue depends on insurability.
Payment frequency and timing
Monthly, quarterly, and annual payment options can carry different amounts. Premium payment periods and any age-based changes are set by the specific policy.
Your circumstances
Your household, business, and estate goals help determine the coverage you need, which in turn shapes the premium discussion. These are general factors, not a quote.
Whole life cash value may build under the contract. It includes guaranteed and non-guaranteed amounts, and dividends, where offered, are not guaranteed. Loans or withdrawals can reduce both cash value and the death benefit. Tax treatment depends on the policy and your situation, and this page is general information, not tax advice.
Questions to Bring to Your Coverage Review
What is the total monthly cost?
Ask for the premium, payment period, and any age-based changes under the specific policy, along with the limitations and exclusions.
How much coverage fits my needs?
A common rule of thumb is a multiple of income, but it is only a starting point. The right amount depends on what you are protecting and your circumstances.
Which guarantees apply?
Separate the guaranteed values from the non-guaranteed ones, and ask how loans or withdrawals would affect cash value and the death benefit.
How does the policy fit my plans?
Whether the policy supports an estate plan, a business agreement, or a family need depends on the contract terms and applicable rules.
Protect your loved ones with a coverage review
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.


