



Life Insurance Costs | Florida and across the United States
What a $1,000,000 Life Insurance Policy Costs Depends on Your Situation
There is no single monthly price for $1,000,000 of coverage. Policy type, term, age, health and underwriting all shape the cost. NR CPAs & Business Advisors helps families, professionals and business owners understand those factors before they choose a policy.
By Nischay Rawal · Published October 19, 2026
How much does a $1,000,000 life insurance policy cost per month?
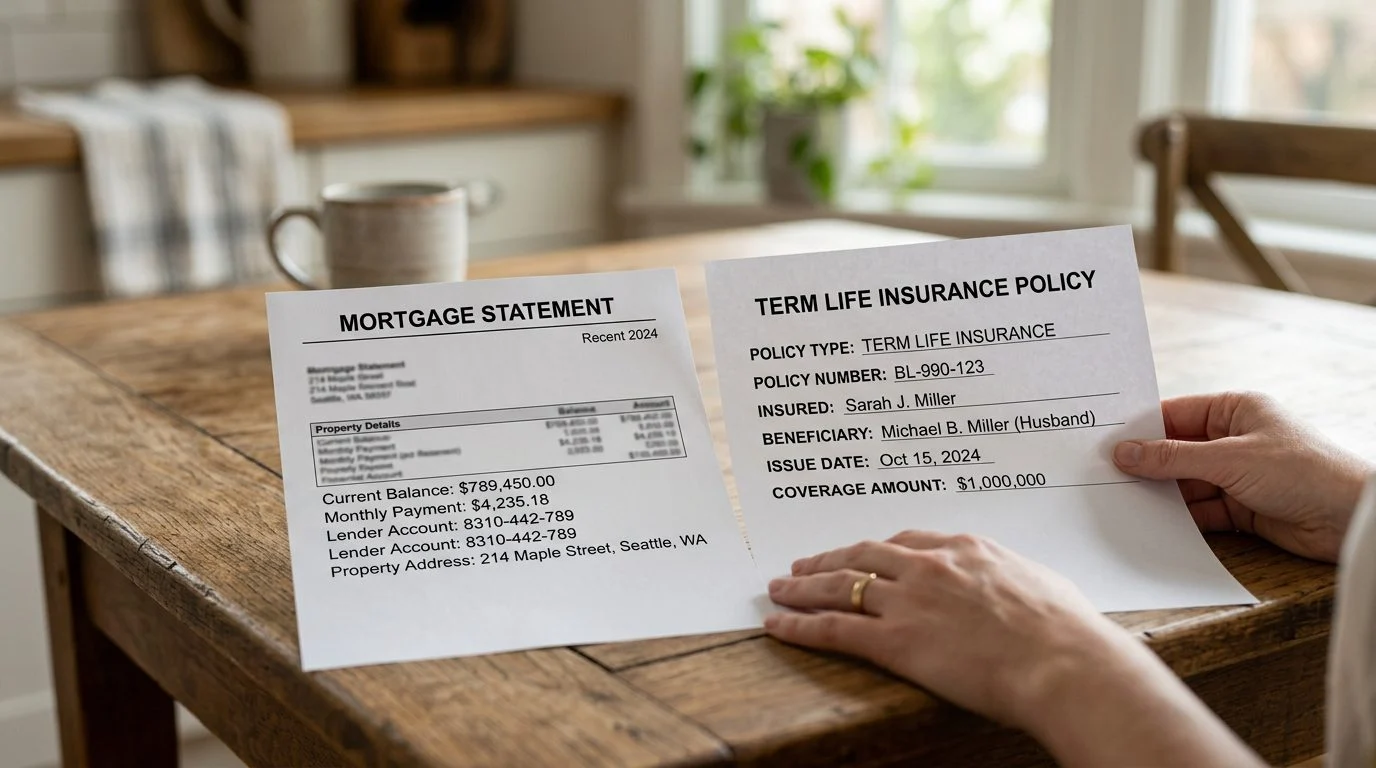
A $1,000,000 life insurance policy has no single monthly price. The cost depends on the policy type, the length of coverage, your age and health, and how the insurer underwrites your application.
This guide explains each cost driver in plain words. It also covers the Florida rules and tax points that affect the policy after you buy it.
NR CPAs & Business Advisors is a CPA firm in Miami, Florida. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Does term or permanent coverage change the monthly cost?
Yes. The policy structure is the biggest cost driver. Colorado’s Division of Insurance notes that term life insurance is typically less expensive than cash-value policies. The reason is that cash-value premiums also fund the cash value.
Term coverage lasts for a set number of years and has no cash value. Oregon’s Division of Financial Regulation explains that permanent coverage can stay in force as long as premiums are paid. It also has a cash-value account.
South Carolina’s Department of Insurance explains that whole-life coverage builds cash value. That cash value can be borrowed against or cashed out. Those features are part of why the monthly cost is higher.
Comparing the two types takes more than comparing monthly amounts. FINRA’s guidance on exchanging a life insurance policy points to surrender charges, cash value and policy replacement as factors to weigh.
How do age and health affect the monthly cost?
Age and health are the next biggest factors. Premiums generally rise with age at issue. Insurers review your health history before they set the rate.
Health questions are part of the application. Issue may depend on insurability. The insurer’s decision and the rate both depend on what it finds.
Accurate facts matter. That calculation uses the insurer’s rate on the issue date.
How does the payment schedule affect cost and coverage?
Your payment schedule changes your monthly outlay. It also changes what happens if a payment is late.
Florida law requires a grace period. Fla. Stat. § 627.453 says every insurance contract must give at least 30 days to pay any premium after the first. The policy stays in force during that period.
For some older policyowners, Florida adds a notice step. Fla. Stat. § 627.4555 provides that a life insurance contract issued or issued for delivery in Florida on or after October 1, 1997, that covers a natural person aged 64 or older and has been in force for at least 1 year may not be lapsed for nonpayment of premium unless, after the grace period expires and at least 21 days before the effective date of any such lapse, the insurer has sent a notification of the impending lapse in coverage to the policyowner and to a secondary addressee designated in writing by name and address. For a policy that provides a grace period of more than 51 days, that notification must instead be mailed to the policyowner and the secondary addressee at least 21 days before the grace period expires. The policyowner may designate a secondary addressee when applying for the policy, on a form the insurer provides, and at any time the policy is in force, by sending the insurer written notice with the secondary addressee’s name and address. The section does not apply to a contract under which premiums are payable monthly or more frequently and are regularly collected by a licensed agent or are paid by credit card or by a preauthorized check processing or automatic debit service of a financial institution.
Incontestability also has a time limit. Fla. Stat. § 627.455 says a policy becomes incontestable after it has been in force during the insured’s lifetime for 2 years from its date of issue. Fla. Stat. § 627.455 reads: “Every insurance contract shall provide that the policy shall be incontestable after it has been in force during the lifetime of the insured for a period of 2 years from its date of issue except for nonpayment of premiums and except, at the option of the insurer, as to provisions relative to benefits in event of disability and as to provisions which grant additional insurance specifically against death by accident or accidental means.” The exception for nonpayment of premiums still applies.
What is the tax and estate view of a $1,000,000 policy?
A death benefit is generally not counted as income to the beneficiary. Under IRC § 101, gross income does not include amounts received, whether in a single sum or otherwise, under a life insurance contract if such amounts are paid by reason of the death of the insured, except as otherwise provided in the section, including the transfer-for-value and later-payment rules.
Estate tax is a separate question. IRC § 2042 provides that the value of the gross estate shall include the value of all property to the extent of the amount receivable by the executor as insurance under policies on the life of the decedent, and to the extent of the amount receivable by all other beneficiaries as insurance under policies on the life of the decedent with respect to which the decedent possessed at his death any of the incidents of ownership, exercisable either alone or in conjunction with any other person. IRC § 2042 reads: “For purposes of the preceding sentence, the term “incident of ownership” includes a reversionary interest (whether arising by the express terms of the policy or other instrument or by operation of law) only if the value of such reversionary interest exceeded 5 percent of the value of the policy immediately before the death of the decedent.” The first is insurance receivable by the executor. The second is insurance receivable by other beneficiaries when the decedent held incidents of ownership at death. IRC § 2042 reads: “For purposes of the preceding sentence, the term “incident of ownership” includes a reversionary interest (whether arising by the express terms of the policy or other instrument or by operation of law) only if the value of such reversionary interest exceeded 5 percent of the value of the policy immediately before the death of the decedent.”
The IRS sets the 2026 basic exclusion amount at $15,000,000 for estate and gift tax. See IRS Revenue Procedure 2025-32. Whether a death benefit counts toward the gross estate depends on facts such as who owns the policy.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
What should business owners know about cost?
Business coverage is built around a specific purpose. Key person and buy-sell coverage are two common examples.
Florida law allows a buy-sell party to insure another party’s life. Fla. Stat. § 627.404 says a party to a contract for the purchase or sale of an interest in a business entity has an insurable interest in the life of each other party. That interest applies for the purpose of that contract only.
The same statute says an insurer may rely on the applicant’s statements about insurable interest. The insurer is not liable, except as set forth in the policy, for untrue statements it relied on in good faith. Accurate paperwork protects both sides.
Coverage amounts for business policies are often tied to the terms of the business agreement. Cost follows from the amount, the structure and the insured’s age and health.
Next steps for families and business owners
Families in Miami, Fort Lauderdale, Orlando, Tampa and Jacksonville face the same cost drivers. Florida’s grace period and incontestability rules apply statewide.
Start by listing the purpose of the coverage. Note who depends on the income, who owns the business interest and how long the need will last. Those facts shape the policy type and the cost.
Frequently asked questions
How much does a $1,000,000 life insurance policy cost per month?
There is no single monthly price. The cost depends on the policy type, term, age, health and underwriting.
Is term life insurance cheaper than whole life insurance?
Term life insurance is typically less expensive than cash-value policies. Cash-value premiums also fund the cash value.
How long is the grace period for a life insurance premium in Florida?
Florida law requires at least 30 days to pay any premium after the first. The policy stays in force during that period.
When does a life insurance policy become incontestable in Florida?
Under Fla. Stat. § 627.455, a Florida life policy generally becomes incontestable 2 years after its date of issue, subject to statutory exceptions, and nonpayment of premiums is one of those exceptions.
Is the death benefit taxable?
Under federal law, amounts paid because of the insured’s death are generally excluded from gross income. Estate tax treatment depends on facts such as who owns the policy.
Talk with a licensed agent about your numbers
If you’re weighing a $1,000,000 policy for your family or your business, the cost depends on your own facts. Request a coverage review with NR CPAs & Business Advisors at our contact page. Nischay Rawal, a licensed insurance agent, will walk through the options with you.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
What Shapes the Cost of $1,000,000 in Coverage
Age at the time of application
Life insurance is generally priced using the age of the person being insured. Applying at a younger age often leads to lower premiums for the same face amount.
Health and underwriting
Insurers review health history to determine how a policy is issued and priced. Health questions are part of the process, and the issue of a policy may depend on insurability.
Type of policy
Term life insurance and whole life insurance are built differently. Term coverage runs for a set period, while whole life insurance is designed to last for the insured's lifetime and includes cash value.
Purpose of the coverage
Key person insurance, buy-sell agreement insurance and estate planning life insurance each serve a different purpose, and the structure you choose affects the cost.
Compare the Full Policy, Not Just the Monthly Figure
A lower premium can come with fewer benefits, shorter coverage or more exclusions. Before comparing prices, ask for the insurer's name, the policy form number, the face amount, the premium, the payment period, the limitations and exclusions, and whether the policy can be renewed or cancelled and whether premiums change with age.
How a Coverage Review Helps
Start with your goals
We discuss who depends on your income, what the coverage needs to accomplish and how long you need it to last.
Review the cash flow
As a CPA firm, we look at how premiums fit into your budget and how a policy may interact with your tax and business planning.
Compare like with like
We walk through term life insurance and whole life insurance side by side, using the same face amount and the same terms, so the differences are clear.
Plan for ownership and transfer
For business owners and families, we review key person insurance, buy-sell agreement insurance and estate planning life insurance in the context of the wider plan.


