



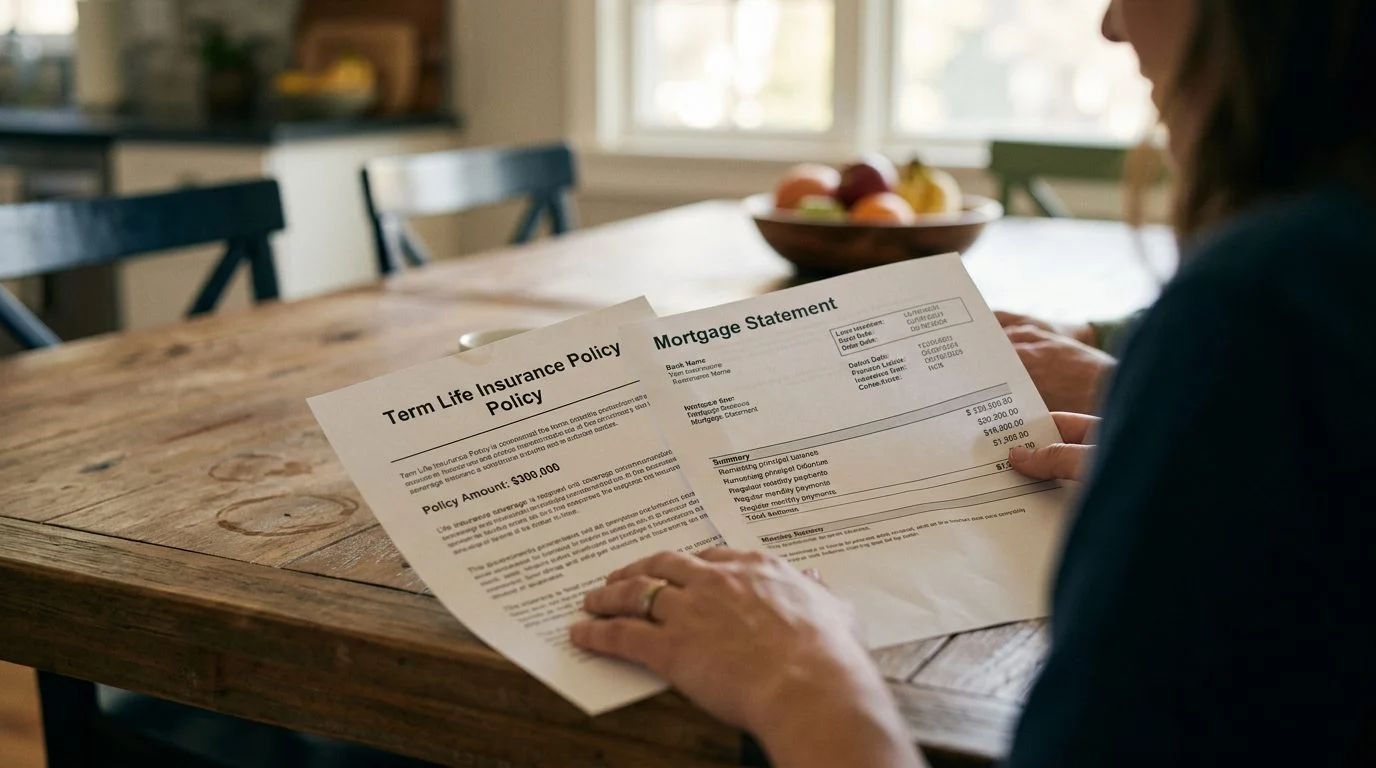
Term Life Insurance | Florida
What Shapes the Cost of a $300,000 Term Life Insurance Policy
Age, health, and the length of the term all affect the price. Here is what to understand before you compare figures, and how a coverage review with NR CPAs & Business Advisors can help you protect your loved ones.
By Nischay Rawal · Published October 18, 2026
How Much Does a $300,000 Term Life Insurance Policy Cost Per Month?
A $300,000 term life insurance policy does not have one monthly price. An insurer sets the monthly figure for a specific applicant and a specific policy, so the same face amount can cost different amounts for different people. This page explains what sets that number, how term length and age change it, and what a written monthly figure must show. It does not quote a premium.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Why there is no single monthly price for a $300,000 term policy
There is no single monthly price because each insurer prices each applicant through its own underwriting. Underwriting is the review an insurer uses to decide whether to issue a policy and at what cost.
Rate tables and online ranges show typical figures. They are not a quote. A quote is a written figure for a named insurer, a named policy form, and a named applicant. Only that written figure tells you what the policy would cost you.
The monthly amount is an output of underwriting. It is not a fixed price printed on the policy. Two people who ask for the same $300,000 face amount can receive different offers, and the offer can also change if the insurer learns new facts during underwriting.
What sets the monthly figure
The main inputs are the applicant’s age at application, sex, and tobacco or nicotine use. Insurers also look at health history, current medications, height and weight, and the underwriting class they assign. Each insurer weighs these factors in its own way.
Health questions are part of underwriting. Issue and the premium may depend on insurability, which means the insurer’s view of your health can change the offer or whether you receive one.
The term length you pick and any riders added to the base policy also change the cost. A longer level period usually adds to the monthly figure, and each rider adds its own charge.
Age also matters after the policy starts. If an insurer finds the age or sex of the insured was misstated, the benefit is adjusted. Under Fla. Stat. § 627.456, the benefit becomes what the premium would have bought at the correct age or sex, using the insurer’s rate at the date of issue.
How term length, age and renewal change the payment
A term policy has a set term, such as 10, 20 or 30 years. The premium is level for that term. Coverage ends when the term ends unless the policy has another provision that continues it.
Check your written figure for what happens when the level period ends. Ask whether the premium changes, whether the policy is renewable, and whether any age-based change applies. Some term policies also include a conversion option, so check the written terms for that feature too.
The same face amount generally costs more at older ages. For a 60-year-old man or a 70-year-old man, the monthly figure is usually higher than it would be at a younger age. Whether term coverage still makes sense after 50 depends on your debts, your dependents, and the coverage you already have, not on age alone.
Older policyowners have an added protection in Florida. A life insurance policy issued, or issued for delivery, in Florida on or after October 1, 1997, that covers a natural person aged 64 or older and has been in force for at least one year generally may not lapse for nonpayment unless the insurer has mailed a notice to the policyowner and any designated secondary addressee once the grace period has ended and at least 21 days before the lapse would take effect. If the policy’s grace period is longer than 51 days, the insurer must instead mail that notice at least 21 days before the grace period ends. Under Fla. Stat. § 627.4555, the insurer must mail a notice of impending lapse to the policyowner and to a secondary addressee designated in writing. This rule has exceptions, including some monthly premiums collected by a licensed agent or paid by automatic debit. Fla. Stat. § 627.4555 reads: “This section does not apply to any life insurance contract under which premiums are payable monthly or more frequently and are regularly collected by a licensed agent or are paid by credit card or any preauthorized check processing or automatic debit service of a financial institution.”
How term compares with whole life in monthly cost
A whole life insurance policy for the same face amount usually costs more each month. Colorado’s insurance regulator states that term life insurance is typically less expensive than cash-value policies, because whole and other cash-value premiums also fund the cash value.
Term life covers a specified number of years and has no cash value. Oregon’s regulator explains that permanent life insurance stays in force while premiums are paid and has a cash-value account that can be borrowed against or withdrawn. The South Carolina Department of Insurance describes the same difference in its life insurance guide.
Term life insurance does not build cash value. Describe each product by its generic name only. Do not treat either one as an investment or a savings plan.
When you compare a term figure with a whole life figure, look at the guaranteed values and the non-guaranteed values separately. Participating policies may pay dividends, and dividends are not guaranteed. FINRA notes that comparing term and permanent coverage also involves surrender charges and policy replacement considerations.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
How to read any written monthly figure
A written figure should name the insurer and the policy form number. It should also name the licensed insurance agent who prepared it. Under Fla. Stat. § 626.9531, when soliciting or selling insurance products, an agent must clearly indicate to prospective insureds that they are acting as an insurance agent with regard to the insurance products and the identified insurers.
Check these items on every figure:
- The face amount, which is the death benefit.
- The monthly premium and the payment period.
- Whether the face amount or the premium changes over time.
- The limitations and exclusions.
- The renewability and cancellability terms.
- Any age-based change in premium.
Compare two figures only when the payment mode is the same. An annual payment and a monthly payment can total different amounts over a year.
Fitting the payment into your household budget
Set the monthly premium against your household cash flow, your existing employer or other coverage, and the obligations the policy would need to address. Think about the coverage amount in terms of those obligations, not as a fixed rule of thumb.
From a CPA’s view, the tax treatment matters too. Under IRC § 101(a)(1), except as otherwise provided in paragraphs (2) and (3), subsection (d), subsection (f), and subsection (j), gross income does not include amounts received under a life insurance contract if such amounts are paid by reason of the death of the insured. Interest paid on proceeds left with the insurer is taxable. Your own tax position depends on your facts, so review it with your tax preparer.
Florida’s standard policy terms also give a grace period. Under Fla. Stat. § 627.453, a grace period of not less than 30 days applies to payment of any premium after the first. Missed payments still need a plan.
Insurance is offered by the licensed agent, separately from the accounting practice.
Talk through your situation in a coverage review
The monthly figure for your situation comes from a coverage review, not from this page. You may be comparing this number for a spouse or parent while a mortgage or a new health question is on your mind. That is a common place to start, and it is reasonable to ask questions before you decide.
Nischay Rawal is a licensed insurance agent who offers coverage reviews. Contact us to set up a coverage review and we will walk through the figure with you, along with the questions above.
Frequently asked questions
Does this page give a monthly premium for a $300,000 term policy?
No. The page explains what sets the figure and what a written quote must show.
Is the monthly cost the same for everyone?
No. Age, sex, tobacco use, health history, and underwriting class all affect the offer.
Does a term policy build cash value?
No. Term life covers a set period and has no cash value.
Does Florida give extra protection to older policyowners?
Yes. Where a life insurance contract covers a natural person aged 64 or older, was issued or issued for delivery in this state on or after October 1, 1997, and has been in force for at least one year, the insurer generally has to mail a lapse notice once the grace period has ended and no later than 21 days before the lapse would take effect. If the policy provides a grace period longer than 51 days, that notice has to be mailed at least 21 days before the grace period ends, and other exceptions also apply.
Factors That Affect the Price
Age and sex
Insurers generally price term coverage based on the age and sex of the person insured. Premiums for the same face amount usually rise as age increases.
Health history and tobacco use
Insurers review health information and tobacco use during underwriting. The results help determine the underwriting class offered, and the issue of a policy may depend on insurability.
Length of the term
A longer level-premium period generally means a different premium than a shorter one. Each term option should be reviewed against your household's needs and budget.
Underwriting class
Two people of the same age can receive different offers. The class assigned by the insurer shapes the premium you would pay.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
What a Written Quote Should Show
The insurer and policy form
A quote should name the insurer that would issue the policy and the policy form number, so you know exactly what is being offered.
Face amount and premium
The face amount, the premium, and the payment period should appear together, with any future changes in face amount or premium clearly stated.
Limitations and exclusions
Every limitation and exclusion that applies to the policy should be listed, not only the features that make the offer look attractive.
Renewability and age-based changes
The quote should explain whether the policy can be renewed, whether it can be cancelled, and how the premium may change with age.
A Figure Here Is Not a Quote
This page does not provide a monthly premium for a $300,000 term policy. Your rate depends on your own age, health, and underwriting. Insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors.
Protect Your Loved Ones With the Right Coverage
Related practice areas
- How Much Does a $1,000,000 Term Life Insurance Policy Cost?


