



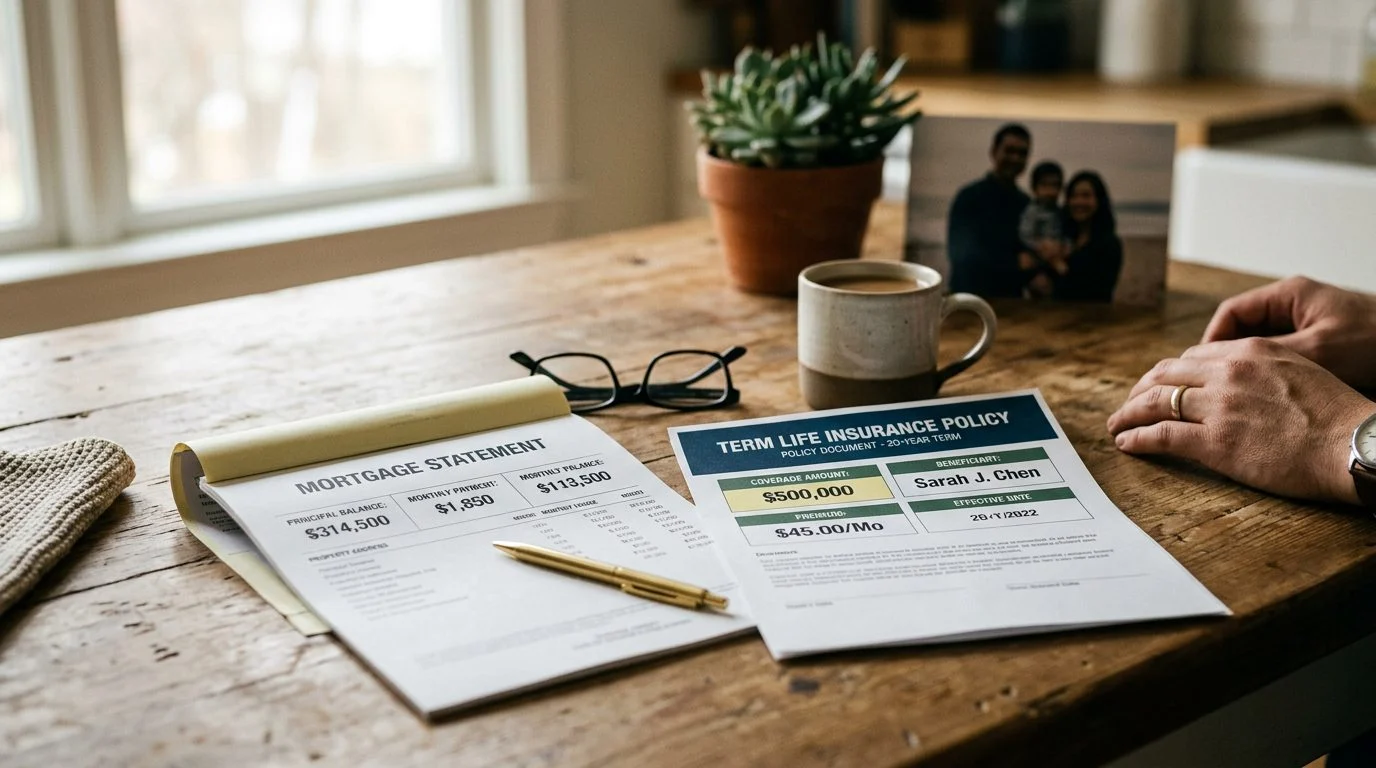
Term Life Insurance
How Much Term Life Insurance Coverage Do You Need?
A practical cash-flow method to calculate the right amount for your family's future.
By Nischay Rawal · Published October 07, 2026
How Much Term Life Insurance Coverage Do You Need? A CPA’s Cash-Flow Approach
The answer isn’t a multiple of your salary—it’s the total amount your family would need to maintain their lifestyle and meet their obligations if you were gone. Most people hear the generic advice: buy 10 times your income. But that shortcut works for some and fails for others. A more reliable method starts with your actual cash flow: your family’s expenses, debts, income sources, and the timeline they’ll need coverage.
This page walks you through a step-by-step approach that CPAs use to think about financial risk. It’s concrete, defensible, and built on your real situation—not a formula.
If your family inherits taxable investments or retirement accounts, they may owe income tax. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Why the “Multiple of Salary” Rule Misses the Real Picture
A common guideline is to consider 5 to 10 times your annual income in term life insurance coverage. The logic is simple: if you earn $75,000 a year, buy $375,000 to $750,000 in coverage.
The problem: that range ignores what your family actually spends and owes.
A single person with no dependents and a paid-off home needs far less than a parent with a mortgage, two children in private school, and a spouse who left the workforce to raise kids. A business owner with key employees depending on them may need more than an employee with a stable employer group policy. A household with significant savings and Social Security survivor benefits coming in may need less coverage than one with high debt and low other income.
The income multiple is a starting point, not a destination. It works as a rough screen—if you have no coverage at all, buying some multiple of your income is better than nothing. But it doesn’t account for your specific obligations, timeline, or other resources.
A CPA’s approach is different: start with cash flow, not a number. What does your family actually need to survive and thrive if you’re not there to earn?
What Is a Good Amount for Life Insurance?
The right coverage amount is the total your family would need to cover all their financial obligations for the years they’ll face them—without you.
Break this into five categories:
1. Housing and utilities. If you have a mortgage, your family would need to either pay it off or continue making monthly payments. If you rent, they’d need to cover rent. Add property taxes, insurance, maintenance, and utilities. How long? Until the mortgage is paid off or the kids are independent.
2. Childcare and education. If your spouse works or wants to work, they’d need childcare. If your children attend private school or you plan to help with college, those costs are real obligations. Calculate the annual cost and the number of years.
3. Daily living expenses. Groceries, transportation, insurance, healthcare, clothing, and everything else. Your family’s lifestyle won’t change overnight. What does it cost per year to maintain it?
4. Debt repayment. Credit cards, car loans, student loans, personal loans—anything your family would inherit. Some debts (like a mortgage) might be covered under category 1, but list everything.
5. Income replacement. If your spouse works part-time or stays home, your income is the primary household income. Your family would lose it. How many years would they need that income replaced? Until the youngest child finishes college? Until your spouse reaches retirement age?
The right amount also depends on other income sources. Your spouse may earn income. Social Security provides survivor benefits to your children and spouse. You may have employer group life insurance. Savings and investments can bridge gaps. These reduce the amount of term life insurance you need to buy.
The Cash-Flow Method: Building Your Coverage Number from the Ground Up
Here’s the step-by-step approach:
Step 1: List all financial obligations your family would face if you were not there.
Write down: – Mortgage balance (or annual rent × years) – Car loans – Credit card debt – Student loans – Childcare costs per year – Private school tuition per year – College savings goals – Annual household expenses (groceries, utilities, insurance, transportation, healthcare, etc.)
Step 2: Calculate the years those obligations will continue.
When would each expense end? Your mortgage might run 25 more years. Childcare might end in 8 years. College costs might span 18 years (if you have young children). Your spouse might need income replacement for 20 years (until they reach retirement age). Write down the timeline for each.
Step 3: Estimate the annual cash shortfall your family would experience.
Add up your annual household expenses. Subtract the income your spouse would earn, Social Security survivor benefits your children would receive, and any employer group life insurance your family would get. The difference is the annual shortfall.
For example: – Annual household expenses: $80,000 – Spouse’s income: $30,000 – Social Security survivor benefits: $20,000 – Employer group coverage: $50,000 (one-time, not annual) – Annual shortfall: $30,000
Step 4: Multiply the annual shortfall by the number of years to find the total coverage needed.
If your family needs $30,000 per year for 20 years, you need $600,000 in coverage to replace that income. But you also have one-time costs (funeral, final expenses, debt payoff). Add those separately.
Step 5: Add a buffer for inflation and unexpected costs.
Inflation will erode the purchasing power of your coverage over time. Inflation compounds year over year, so a fixed coverage amount buys less as time goes on. Add a buffer to your number to account for this and for costs you didn’t anticipate (medical emergencies, home repairs, helping aging parents).
Why this method is more reliable: It’s built on your actual obligations and timeline, not a generic formula. It accounts for your spouse’s income, Social Security, and other resources. It’s specific enough to defend to your family and to yourself.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
A Simple Example
Let’s walk through a scenario to illustrate the method.
Sarah is a mid-career project manager. She is the household’s primary earner. Her spouse, Alex, works part-time as a consultant and earns a modest income. They have a 15-year mortgage with a balance still owed. They have two children, ages 8 and 11. They want to help with college costs. They have savings and an employer group life insurance policy through Sarah’s job.
Step 1: List obligations. – Mortgage balance – Car loan – Credit card debt – Annual household expenses – Childcare (until youngest is 13) – College savings goal (for both children)
Step 2: Calculate timelines. – Mortgage: 15 years – Car loan: 4 years – Credit card debt: 1 year (assume paid off quickly) – Household expenses: 18 years (until youngest finishes college) – Childcare: 5 years – College: 10 years (ages 8 and 11 now, college in 10–13 years)
Step 3: Estimate annual shortfall. – Annual household expenses – Childcare (for 5 years) – Alex’s part-time income – Social Security survivor benefits (estimate) for children and spouse – Employer group coverage (one-time) – Annual shortfall (years 1–5): household expenses + childcare − Alex’s income − survivor benefits – Annual shortfall (years 6–18): household expenses − Alex’s income − survivor benefits
Step 4: Multiply by years. – Years 1–5: annual shortfall × 5 – Years 6–18: annual shortfall × 12 – One-time costs: mortgage + car loan + credit card + college + funeral/final expenses – Total before buffer: the sum of the above
Step 5: Add buffer. – A buffer for inflation and unexpected costs applied to the total – Total coverage needed: the buffered total
Sarah might round to a coverage amount near her total.
The generic “10 times income” rule would suggest a figure based on her salary alone. In some cases, it happens to land in the same ballpark. But the cash-flow method shows why a given number works for Sarah—and it would produce a very different answer for someone with different obligations, income sources, or timeline.
How Long Should You Get Term Life Insurance For?
Term length should match your obligations, not your age.
Common term lengths are 10, 15, 20, and 30 years, according to the NAIC Life Insurance Buyer’s Guide. Choose the term that covers your family’s biggest financial obligations.
For a young parent with a 30-year mortgage and children who won’t finish college for 18 years, a 20 or 30-year term makes sense. For someone in their 50s with a paid-off home and adult children, a 10 or 15-year term may be enough.
The relationship between term length and coverage amount matters. A shorter term with higher coverage may be more efficient than a longer term with lower coverage. Why? Because term premiums are lower in the early years and rise as you age. If you need $1,000,000 in coverage for the next 15 years, a 15-year term at that face amount will cost less per month than a 30-year term at a lower face amount—and you’ll have the full coverage when your family needs it most.
Other Sources of Income and Assets to Consider
Your coverage calculation should account for income and resources your family would have access to:
Social Security survivor benefits. If you die, your spouse and dependent children may qualify for benefits. Life insurance proceeds and Social Security benefits are treated separately for tax purposes, and a coverage review can help you understand how each may fit into your planning. Estimate your family’s benefits at ssa.gov or ask the Social Security Administration.
Employer group life insurance. Many employers offer group coverage, often 1–3 times your salary. This is typically included in your benefits package. It’s valuable but often not enough on its own, especially if you leave that job.
Savings and investments. If you have savings, your family could use it to cover immediate expenses or debt. This reduces the amount of term life insurance you need to buy. But don’t assume your family will spend down savings quickly—they may need it for emergencies.
Retirement accounts. IRAs, 401(k)s, and other retirement accounts can pass to beneficiaries. A CPA can help you understand how these assets fit into your family’s financial picture.
Your spouse’s earning potential. If your spouse could increase their income or return to full-time work, that’s an income source. But it’s not guaranteed, and it may take time. Don’t assume it away—but do factor it in if it’s realistic.
What Does Life Insurance Term Length Mean?
Term length is the period during which the policy will pay a death benefit if you die. If you buy a 20-year term policy today, it will pay the full death benefit to your beneficiary if you die at any point in the next 20 years. If you die after 20 years, there’s no benefit—the coverage has expired.
Term length is separate from how long you need coverage. You might need coverage for 18 years (until your youngest finishes college), but you might buy a 20-year term to have a small buffer. Or you might need coverage for 25 years, so you’d buy a 30-year term.
Longer terms cost more per month because the insurer is taking on more risk. A 30-year term is more expensive than a 20-year term at the same face amount. But the premium is locked in for the entire term, so you know what you’ll pay each month.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
What’s Left Out of the Calculation?
The cash-flow method is thorough, but a few costs often get overlooked:
Estate settlement costs. Probate, attorney fees, and accounting fees to settle your estate can run into the thousands. Add $5,000–$15,000 depending on your state and the complexity of your estate.
Taxes on inherited assets. If your family inherits taxable investments or retirement accounts, they may owe income tax. This is complex and depends on what they inherit. A CPA can model this for you.
Household help. Your family might need a housekeeper, lawn care, or handyperson services you currently handle yourself. Budget for this.
Childcare or eldercare. If you’re caring for aging parents or adult children with special needs, factor in the cost of replacing that care.
Life insurance itself. The premiums you pay for coverage are an expense. But they’re typically small compared to the benefit, and they help provide security for your family.
Why a CPA’s Perspective Matters
A CPA thinks in cash flow and tax impact. Insurance is often sold by focusing on mortality risk—the chance you’ll die and leave your family without income. That’s real and important. But a CPA also asks: How does this insurance fit into your overall financial picture? What are the tax consequences? How does it interact with your estate plan, your retirement savings, and your spouse’s income?
Here’s what changes when you add a CPA’s view:
This means your family receives the full amount tax-free. For most families, this won’t matter—the basic exclusion amount for federal estate tax in 2026 is $15,000,000, so estates below that threshold owe no federal estate tax. But it’s worth understanding.
After-tax income replacement. When you calculate your family’s annual shortfall, you’re looking at expenses. But if your spouse returns to work or takes on more income, that income is taxable. A CPA helps you think through the net (after-tax) income your family would have, not just the gross number.
Coordination with other insurance. If you have employer group coverage, disability insurance, or other policies, they all interact. A CPA can help you see the full picture and avoid gaps or overlaps.
Cash flow over time. Your family’s needs change. As your children grow, childcare costs drop. As your mortgage is paid off, housing costs drop. As you get closer to retirement, your earning years shrink. A CPA helps you think about these shifts and whether your coverage should change.
Next Steps: From Calculation to Coverage
You now have a method to calculate how much term life insurance your family needs. Your calculation is a starting point, not a final answer.
Review your calculation as your life changes. When you get married, have children, buy a home, change jobs, or experience a major financial event, recalculate. Your needs shift, and your coverage should too.
A coverage review is the next step. Once you’ve done the math, it’s worth talking through your situation with someone who understands both insurance and accounting. They can help you confirm your number is right, explore whether term life insurance is the best fit for your situation (or whether whole life or other options make sense), and make sure your coverage aligns with your overall financial plan.
What to expect. When you reach out, you’ll have a conversation about your family’s obligations, timeline, and other resources. We’ll help you think through whether your calculation is complete and whether your coverage strategy makes sense. This is a coverage review, not a sales pitch—it’s a chance to make sure you’re protected. Insurance is offered through our licensed insurance agent, separately from the firm’s accounting practice.
If you’re weighing how much coverage your family actually needs and want to talk through your specific situation, reach out to discuss a coverage review with our team.
About This Page
Term life insurance is offered by Nischay Rawal, a licensed insurance agent in Florida, separately from NR CPAs & Business Advisors' accounting practice. Issuance of a term life policy depends on insurability and health questions required during underwriting. The amounts and scenarios discussed here are illustrative only and do not constitute a recommendation for your specific situation.
Why a Cash-Flow Approach Works
Based on Real Numbers
Start with your family's actual expenses, debts, and income sources—not generic salary multiples.
Accounts for Your Timeline
Coverage needs change. This method shows how long your family would need support and what that costs.
A CPA's Perspective
We think in terms of cash flow and tax impact, which matters when you're planning for your family's financial security.
The Four Steps to Your Coverage Amount
1. List Your Family's Annual Expenses
Add up housing, food, utilities, insurance, education, childcare, and other regular costs. This is what your family would need each year.
2. Account for Major Debts
Include mortgage balance, car loans, credit cards, and student loans. Term coverage can help pay these down so your family isn't burdened.
3. Factor in Income Replacement
If your spouse works, consider how long they'd need to maintain the household alone. If they don't, think about how long they'd need full support.
4. Add a Buffer for Inflation and Emergencies
Costs rise over time. A modest cushion protects your family against unexpected expenses they may face.
Key Point: It's Not About Your Salary
The common advice—buy 10 times your income—is a rough starting point, but it misses your actual situation. A teacher and a business owner earning the same salary may need very different coverage amounts based on their family's expenses, debts, and other income sources.
What Happens Next
Schedule a Coverage Review
Talk with Nischay Rawal, a licensed insurance agent, about your family's situation, expenses, and timeline.
Work Through Your Numbers
We'll walk through the cash-flow method together so you understand exactly what coverage makes sense.
Explore Your Options
Term life insurance offers affordable protection for a set period. We'll explain how it works and what to expect during underwriting.


