



Term Life Insurance | Miami and Florida
What Shapes the Cost of a $1,000,000 Term Life Policy?
A plain-language guide from NR CPAs & Business Advisors on the factors that affect term life premiums, and how a coverage review can help you plan to protect your loved ones.
By Nischay Rawal · Published October 18, 2026
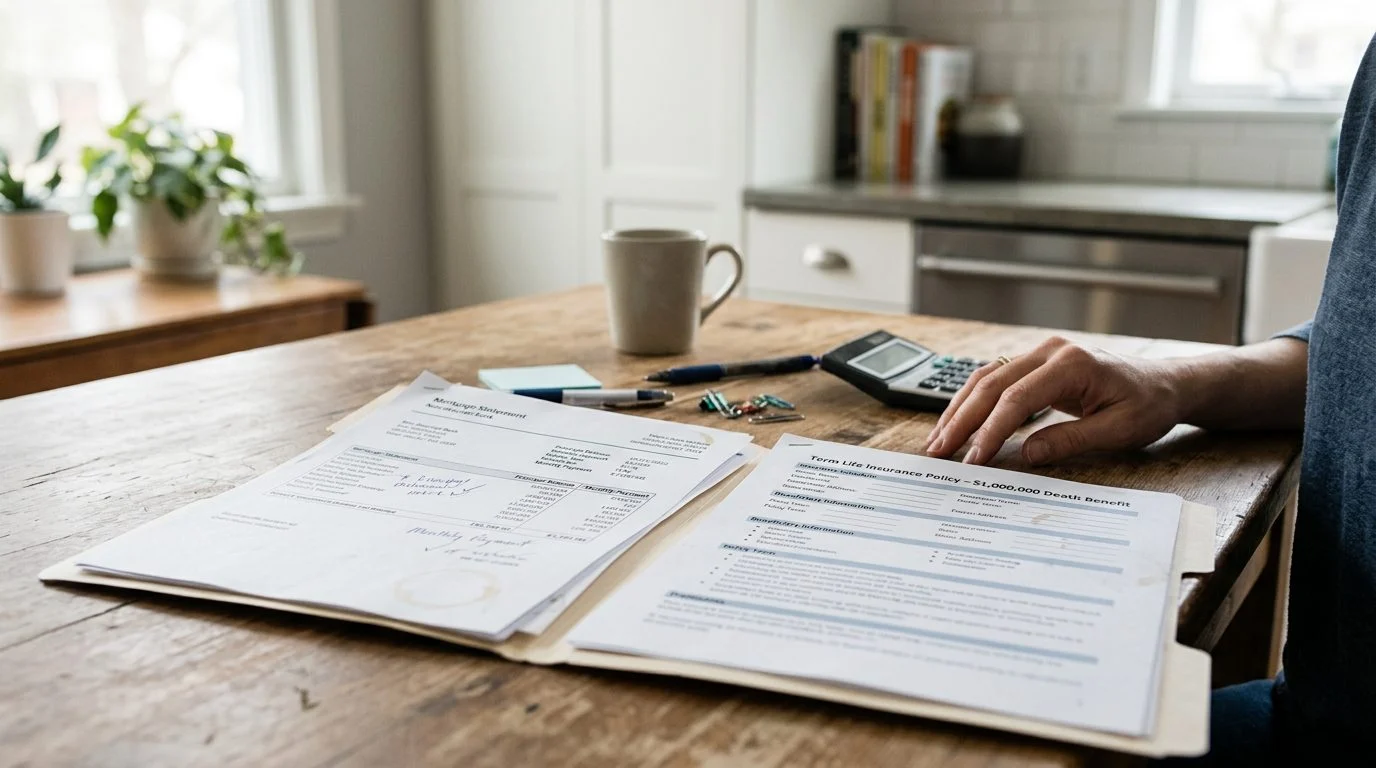
How much does a $1,000,000 term life insurance policy cost? There is no single answer. The premium depends on the insured’s age, health, tobacco use, sex, the term length chosen, and the insurer’s own underwriting rules. Two people can ask for the same $1,000,000 and receive different premiums.
This guide explains each factor, so you can read any quote and understand what it is built on. It is written for families, professionals, and business owners in Florida, including Indian-American households and nonresident Indians with family or business ties in the state.
NR CPAs & Business Advisors is a Miami CPA firm. Life insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the accounting practice.
What a $1,000,000 Term Life Insurance Policy Is
A $1,000,000 term life insurance policy pays a $1,000,000 death benefit to the named beneficiaries if the insured dies during a set number of years. That $1,000,000 is the face amount. The premium is the regular payment you make to keep the coverage in force.
The Oregon Division of Financial Regulation explains that term life insurance covers a specified number of years and has no cash value. That fact drives the cost. You pay for protection during the term. You are not building a savings account.
A term policy is not an investment or a savings plan. When the term ends, coverage ends unless the policy includes a renewal or conversion option. Review those options before you buy, because they affect what you pay later.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What Drives the Price of a $1,000,000 Term Policy
The main price drivers are the insured’s age, health, tobacco use, and sex, plus the term length you pick. Each one changes the risk the insurer takes on. Each one changes the premium.
Age at application usually sets the starting point. A younger applicant generally starts at a lower premium than an older one for the same term and face amount. Health and tobacco use work the same way, because they affect how likely a claim is.
A larger face amount raises the premium. The cost per $1,000 of coverage is not always the same at every coverage level, so ask the insurer how its rates change between amounts.
Each insurer uses its own underwriting rules. Two insurers can rate the same applicant differently. One quote is rarely the full picture.
A coverage review turns these factors into a figure for a specific person. A coverage review can apply these factors to your facts.
How Term Length Changes the Cost
A longer level-premium period usually comes with a higher starting premium. Common choices are 10, 20, and 30 years. A 10-year level period starts lower than a 30-year one for the same face amount, but it ends sooner.
The Alabama Department of Insurance explains that term policies have set durations and may include renewal or conversion options. After the level period, the premium may change. Check renewability and any age-based change before you buy, not after.
The cash-flow view matters here. Count the years a mortgage, children at home, or a business loan still depends on your income. Those years are the period that protection needs to cover.
Buying a shorter term to save money now can leave a gap you did not plan for. Florida law also sets a grace period: under Fla. Stat. § 627.453, a life policy must allow at least 30 days to pay any premium after the first.
Health Questions, Underwriting, and the Medical Exam
The insurer’s review of your health sets your risk class. The risk class drives much of the premium. The process can include health questions, a paramedical exam, lab tests, and a review of medical records, depending on the policy and the insurer.
A policy with a simpler application still asks health questions. Issue may depend on insurability. Do not assume the process is skipped because the application looks short.
Health can change between applying and issue. A change can change the result. Tell the agent about any new diagnosis, medication, or hospital stay before the policy is issued.
Two Florida rules protect you after the policy is issued. Under Fla. Stat. § 627.455, once a life insurance policy has stayed in force for two years from its issue date while the insured is living, the insurer can no longer contest it, except for nonpayment of premiums and, at the insurer’s option, provisions on disability benefits and additional accidental-death coverage. The statute also allows the insurer to contest disability and accidental-death provisions. Incontestable means the insurer generally cannot challenge the policy’s validity after that point.
If the insured’s age or sex was misstated, Fla. Stat. § 627.456 says the benefit is what the premium would have bought at the correct age or sex. Check the application details before you sign.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Whole Life Insurance Costs for Comparison
A whole life insurance policy generally costs more in premium than term for the same death benefit. It is built to last for life and includes a cash value. The South Carolina Department of Insurance explains that whole life and other permanent policies build cash value that the owner may borrow against or receive by surrendering the policy. A policy loan accrues interest, and any unpaid loan balance reduces the death benefit. A surrender may involve surrender charges and taxable gain. Under Florida rules, borrowing more than 25% of a policy’s loan value is treated as a replacement (Fla. Admin. Code 69O-151.002(5)).
Compare values carefully. Guaranteed values and non-guaranteed values should be shown separately. Dividends, where a policy offers them, are not guaranteed.
Compare on the same basis: the premium, the length of coverage, and the purpose the coverage serves. A term policy and a whole life policy solve different problems, so the cheaper premium is not always the better fit.
If you are considering replacing a policy you already own, a Florida replacement must follow the state’s replacement rules, including submitting Form OIR-B2-312 with the application (Fla. Admin. Code 69O-151.007 and 69O-151.010). The FINRA guidance on exchanging life insurance covers surrender charges, cash value, and replacement considerations. Review those before you act.
A whole life policy is not an investment, and it is not a promise of returns. Whether it fits your household or business depends on the facts.
Riders and Options That Affect the Premium
A convertible term rider lets you switch some or all of a term policy to a permanent policy within a set period. The premium on the new policy follows that policy’s terms, not the original term rate.
Many riders increase the cost of a policy. Each rider has its own limitations and exclusions. Read them before you buy, and ask how each rider changes the total premium.
Conversion timing and limits matter most. For the full discussion, see our convertible term life insurance guide.
Where a $1 Million Term Policy Fits in Business and Estate Planning
A $1,000,000 policy can fund a business need or support an estate plan. The purpose changes the questions you ask before you apply.
Key-person insurance covers an owner or essential employee. The business is typically the owner and beneficiary. Under Fla. Stat. § 627.404, a business may insure its owners and key persons if it has an insurable interest in their lives and obtains their written consent before the insurance is bought. Federal employer-owned life insurance rules under IRC § 101(j) also require notice and consent, and without them key-person death proceeds can become taxable above basis.
Buy-sell agreement insurance can fund the purchase of a deceased owner’s interest under a written agreement. The face amount should match what the agreement requires.
Ownership matters for estate planning. Under IRC § 2042, insurance receivable by other beneficiaries is included in the gross estate to the extent that the decedent possessed at death any incidents of ownership in the policy, exercisable alone or in conjunction with any other person. Under IRC § 101(a)(1), gross income does not include amounts received under a life insurance contract if such amounts are paid by reason of the death of the insured, subject to the exceptions the statute provides. Tax treatment still depends on the facts and the ownership structure.
If you are a nonresident Indian with Florida or U.S. family obligations, ask about residency, underwriting, and beneficiary details before you apply.
Frequently Asked Questions About Life Insurance Costs
What are the different types of life insurance?
Term life insurance covers a set number of years and has no cash value. Whole life insurance lasts for life and builds cash value.
What is whole life insurance?
Whole life insurance is permanent coverage that stays in force while premiums are paid. It builds a cash value, and guaranteed and non-guaranteed values are shown separately.
Is whole life insurance the same as an investment?
Whole life insurance is a life insurance policy, not an investment. Whether it fits your household or business depends on the facts.
Does health affect the price of a term policy?
Yes. Health and underwriting help set the risk class, and the risk class helps set the premium.

Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Talking Through Your $1,000,000 Question
If you are weighing a $1,000,000 policy, you do not have to sort out the numbers alone. Our team can walk through your facts in a coverage review with Nischay Rawal at nrcpas.com/contact.
Insurance is offered by Nischay Rawal, a licensed insurance agent in Florida, separately from the accounting practice of NR CPAs & Business Advisors. For the parent guide, see term life insurance.
Factors that influence term life premiums
Age and health
Insurers generally consider your age and health history when setting premiums. Health questions are required, and issue may depend on insurability.
Length of the term
A term policy covers a set number of years. The length you choose affects the premium, as does the period over which you need coverage.
Policy terms and features
Riders, conversion options and renewal provisions can change the premium. Review the policy form and its limitations and exclusions before you decide.
Insurer and policy form
Premiums differ among insurers and products. Your agent can explain the specific policy, insurer and form number under consideration.
Compare coverage, not just price
A lower premium is only useful if the policy fits your needs. Term life insurance has no cash value. Ask for a clear explanation of the coverage period, renewal terms, age-based premium changes and exclusions before you decide.
How to approach your coverage decision
Define the coverage need
Consider who relies on your income and what obligations the coverage should address, such as a mortgage or education costs.
Review the policy details
Look closely at the face amount, premium payment period, renewability, cancellability and any change in premiums tied to age.
Coordinate with your tax and cash flow picture
NR CPAs & Business Advisors considers how life insurance premiums fit into your broader budget and financial planning.
Start with a coverage review
Contact our office to schedule a coverage review with Nischay Rawal, a licensed insurance agent in Florida.


