



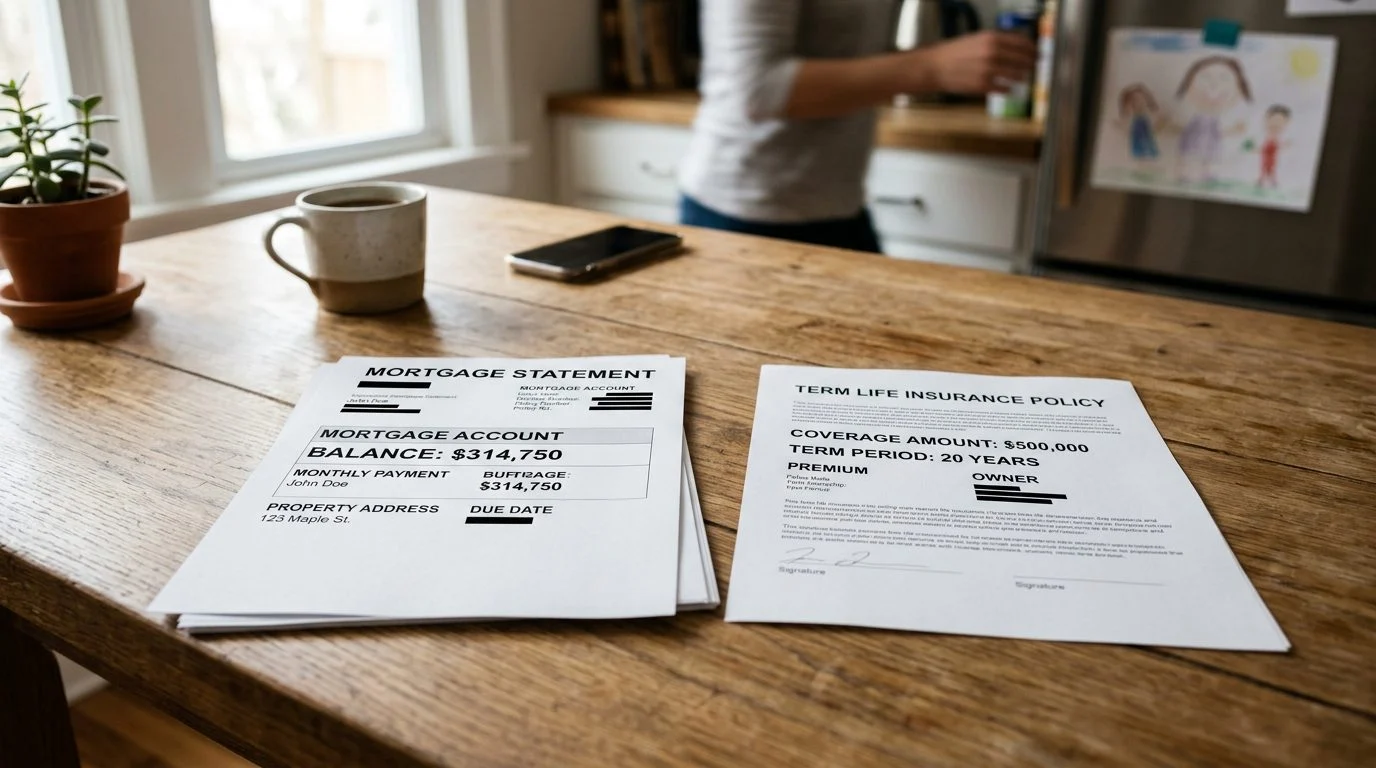
Term and Whole Life Insurance | Florida
What Really Sets the Monthly Cost of $100,000 Life Insurance
Your age, health, policy type, and term length all shape the monthly premium. Learn what drives the cost, then talk through your family's needs with us. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from our accounting practice.
By Nischay Rawal · Published October 18, 2026
How much does a $100,000 life insurance policy cost a month? The answer depends on who is insured, their health classification, the policy type, and the length of the term. The $100,000 is the death benefit, not the monthly bill. Two households can seek the same coverage and see very different monthly premiums.
This guide explains each factor in plain words. It is written for Florida families, including households in Miami, Fort Lauderdale, West Palm Beach, Orlando, Tampa, and Jacksonville, and for Indian-American households and NRIs. NR CPAs & Business Advisors is a Miami CPA firm. Nischay Rawal offers life insurance as a licensed insurance agent, and the policies are issued by the insurers he represents.
What a $100,000 Policy Pays and What the Monthly Figure Covers
The face amount is the death benefit your beneficiaries receive. The premium is the amount you pay to keep the policy in force. Those are two different numbers.
The monthly payment does not change the $100,000 benefit. A lower premium does not mean less coverage. A higher premium does not add a bigger payout. Depending on the policy terms, the death benefit generally remains at the face amount as long as coverage is in force, although policy loans, withdrawals, a decreasing-benefit design or added riders can change the amount paid.
The same factors apply at other face amounts, such as $500,000. The premium generally rises as the face amount rises. The factors below work the same way at any face amount.
If you want help understanding a monthly figure in your household or business budget, you can contact our office to schedule a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Age at Application and Why It Moves the Monthly Premium
Age at application is one of the largest drivers of the monthly premium. Insurers may set premiums using the insured’s age under the convention they apply, such as age nearest birthday or age last birthday. Premiums generally rise as that age rises.
A term policy’s premium may stay level for the term you pick, depending on the policy design; annual renewable term does not. Age-based change usually applies later, at renewal or after the level period ends. Waiting to apply means the insured is older at issue, which can raise the premium.
Accuracy matters here. Florida law covers a wrong age on an application. Fla. Stat. § 627.456 says the amount payable is what the premium would have bought at the correct age, using the insurer’s rate at the date of issue. Check the date of birth on your application before you sign.
Health Classification, Records, and Medical History
Your health classification is the insurer’s rating of your risk, and it shapes the premium. The insurer assigns it after reviewing your health questions, medical records, and, in some cases, a medical exam.
Health questions are part of the process for most policies. Some policies skip the exam but still require health questions, and issue depends on insurability. Family history, tobacco use, prescriptions, and recent lab results can also come into underwriting.
A common mistake is answering quickly or leaving out a condition. The insurer reviews the application when it decides whether to issue the policy and again when it reviews a claim. Answer every question carefully, and keep a copy of what you submitted.
Term Length: How the Monthly Cost Changes Over 10, 20, or 30 Years
A longer level-premium term usually costs more each month than a shorter one. Term life insurance covers a set number of years and has no cash value. South Carolina’s Department of Insurance explains term duration and the lack of cash value in plain terms.
Match the term to the obligation, not only to the monthly figure. A mortgage, a child’s education, or a business loan each ends on its own date. A term that ends too early leaves a gap. A term that runs far past that date may cost more than the need requires.
Read renewability and cancellability in the written terms. Age-based change can apply after the level period ends. Ask what the premium will be at that point. If you may want a different policy type later, ask whether the term policy is convertible.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Term vs. Whole Life: Why the Monthly Cost Is Different
Whole life insurance usually costs more each month than term for the same $100,000 face amount. Part of the premium funds the cash value, the account that builds inside the policy. Oregon’s Division of Financial Regulation describes permanent life as remaining in force while premiums are paid, with a cash-value account that can be borrowed or withdrawn.
Cash value is not the same as the death benefit. Surrender charges, loans, and withdrawals can change what the policy pays and what it is worth. FINRA’s guidance on exchanging a life insurance policy covers surrender charges and cash value, along with policy replacement.
Guaranteed values and non-guaranteed values should be shown separately. Dividends, where a policy offers them, are not guaranteed. A whole life insurance policy is a life insurance contract, not an investment or a promise of returns. Treat the higher premium as the cost of permanent coverage, and test whether the household can keep paying it for many years.
Putting the Monthly Premium Into a Household or Business Cash-Flow Budget
A monthly premium fits a budget when it’s a steady expense you can keep paying for the full term. A CPA’s view of tax and cash flow helps you test that fit before you commit.
For a household, start with the monthly figure. See how it sits beside fixed bills, savings, and debt. Federal law generally excludes life insurance death proceeds from gross income. Internal Revenue Code section 101 provides that, except as otherwise provided in paragraphs (2) and (3), subsection (d), subsection (f), and subsection (j), gross income does not include amounts received (whether in a single sum or otherwise) under a life insurance contract if such amounts are paid by reason of the death of the insured. How tax applies to your premiums and proceeds depends on the facts, so bring those facts to the CPA side of our practice.
For a business, key person insurance and buy-sell agreement insurance are cash outlays the company must plan for. The insured’s profile and the policy terms set each premium. Test that premium against the company’s own budget before a policy is issued. Households with family or property abroad can also ask about NRI life insurance.
What to Ask for in Writing Before You Weigh Any Monthly Figure
Ask for every monthly figure in writing, with its terms attached. A useful written quote shows the insurer, the policy form number, and the type of plan. It also shows the face amount, the premium, and the payment period. Look for any change in the face amount or premium, the limitations and exclusions, renewability, cancellability, and any age-based change.
Read the exclusions in full. Fla. Stat. § 627.455 provides that, during the lifetime of the insured, a life policy becomes incontestable after it has been in force for 2 years from its date of issue, except for nonpayment of premiums; at the insurer’s option, provisions on disability benefits and provisions granting additional coverage against accidental death may also be excepted from that rule. The incontestability clause blocks challenges to the policy’s validity only. Under Fla. Stat. § 627.463, a policy provision that excludes or restricts liability for death caused in a specified manner, or occurring while the insured has a specified status, is permitted only in the circumstances the statute lists.
Missed premiums have a grace period. Fla. Stat. § 627.453 requires a grace period of not less than 30 days for a premium after the first. The policy continues in force during that period.
Fla. Stat. § 473.3205 and Rule 61H1-21.003 require written disclosure of commissions before the engagement, in an engagement letter the client signs with complete details of the compensation. Under the statute and AICPA 1.520.001, no commission may be taken on a product recommended to a client for whom the firm performs an audit, review or examination of prospective financial information. The same bar applies to a compilation of a financial statement only when the licensee expects, or reasonably might expect, that a third party will use that statement and the compilation report does not disclose a lack of independence.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Talk Through Your Situation With Nischay Rawal
If you want help understanding a monthly figure in your household or business budget, you can contact our office to schedule a coverage review. Nischay Rawal acts as a licensed insurance agent in Florida when he offers life insurance. Under Fla. Stat. § 626.9531, a licensed agent must clearly indicate that he is acting as an insurance agent. Insurance is offered through that licensed agent, separately from the accounting practice of NR CPAs & Business Advisors.
Frequently asked questions
Does a higher premium mean a bigger death benefit?
No. The face amount is set by the policy, and the premium pays to keep the policy in force.
How long is the grace period for a missed premium in Florida?
Florida law requires a grace period of not less than 30 days for a premium after the first.
Does a $100,000 policy cost the same for everyone?
No. Age, health classification, policy type, and term all change the premium.
Who offers the insurance?
A licensed insurance agent offers it, separately from the accounting practice.
Our team can set up a coverage review that looks at the factors in this guide, the policy types that fit your goals, and how the premium fits your cash flow. Fee terms are disclosed in writing before any work begins. When you’re ready, contact NR CPAs & Business Advisors through our contact page to request a coverage review with Nischay Rawal.
The main factors behind your monthly premium
Your age when you apply
Insurers generally price coverage based on age at application, so the same $100,000 policy often costs more the older the applicant is.
Your health history
Health questions are part of the underwriting process, and issue may depend on insurability. Your answers help determine the rate class offered.
Term length or whole life design
A term policy covers a set number of years, while a whole life insurance policy is designed to last for the insured's lifetime. Each design is priced differently.
Policy type and riders
Additional features added to a policy change its premium, so compare the same coverage features when you review options.
Ownership and purpose
Key person, buy-sell, estate planning, and NRI life insurance each serve a different purpose, and the structure you choose affects both cost and tax treatment.
A lower premium is not always the better policy
The face amount is set by the policy, and the premium pays to keep the policy in force. A cheaper monthly payment can mean fewer features, shorter coverage, or limitations and exclusions you should read carefully before you decide.
Questions to bring to your coverage review
What coverage does my family need?
Start with your income, debts, and the people who depend on you, then decide how much coverage fits your plan.
Term or whole life?
We walk through how each type of policy is structured, how premiums are set, and how each fits your long-term goals.
How will the cost change over time?
Ask whether renewability, cancellability, and any age-based change in premium apply to the policy you are considering.
How does this fit my tax and cash flow picture?
As a CPA firm, we look at how premiums and policy values interact with your broader finances, while insurance itself is offered through our licensed agent.


