



Miami, Florida | Life insurance guide
Can a Green Card Holder Get Life Insurance? Key Factors to Know
General information on how residency status fits into insurer underwriting, and how a coverage review with NR CPAs & Business Advisors can help you plan.
By Nischay Rawal · Published October 17, 2026
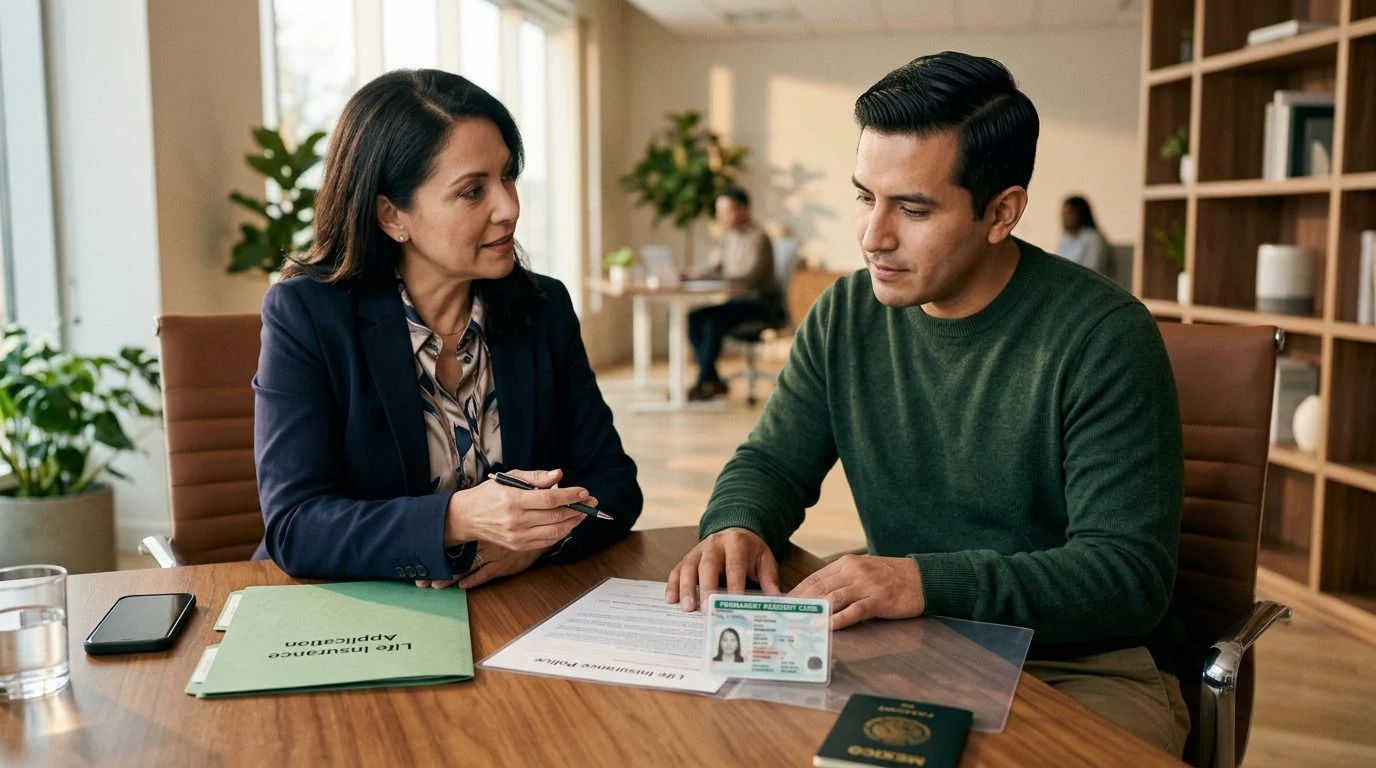
Can a green card holder get life insurance? In many cases, yes. Many insurers accept applications from green card holders. Approval, premiums and coverage depend on each insurer’s underwriting, the policy and the applicant’s circumstances. This page is general information about how residency status fits into that process.
Short answer: can a green card holder apply for life insurance?
Many insurers accept applications from green card holders. A green card holder is a lawful permanent resident, meaning a person who lives in the United States legally on a permanent basis without being a citizen. Residency status is one of several facts an insurer reviews. It is not a separate test that decides the outcome on its own.
Approval, premiums and coverage all depend on the issuing insurer’s rules, the policy you choose and your own facts, such as age, health and the amount you apply for. Two applicants with green cards can get different answers from two insurers. Think of the green card as one piece of the file. The rest of the file is the application, the health information and the policy terms.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What the green card does and does not change
The green card mostly changes the documents you show, not how the application works. Insurers often ask for proof of residency status and identity during the application. The accepted documents vary by insurer, so ask which ones the insurer takes before you start.
Otherwise, the process looks much like any other application. You answer the same health questions, name a beneficiary and receive policy terms that set out premiums, benefits and exclusions. The insurer reviews the file before it issues any policy.
Status can still matter. Each insurer sets its own rules on residency, visa category and time in the country. A green card does not remove those rules. If your status or travel history is unusual, the insurer may ask more questions. Keep your residency papers organized so you can answer quickly.
Can immigrants and other non-citizens apply for life insurance?
Many non-citizens apply for life insurance, and each application is reviewed case by case. Visa category, documents and time spent in the United States can all come up. A reader whose status differs from a green card should not assume the answer is the same. Eligibility depends on the insurer and the facts of the application.
Florida law sets a basic rule. Fla. Stat. § 627.404 says any individual of legal capacity may buy an insurance contract on his or her own life, for the benefit of any person.
Family members and sponsors face another rule. The same section says a person may not buy a contract on another person’s life unless the benefits are payable to that insured, or to someone with an insurable interest when the contract was made. The insured must also apply for or consent in writing to the contract and its terms, with listed exceptions. If a relative is considering a policy for you, the insurable interest question comes first.
Does a life insurance policy cover you if you live or travel abroad?
Whether a policy covers time outside the United States depends on the policy language and the insurer’s terms. Some policies set territory, residence or travel terms. Others handle the question differently. The contract itself is the only reliable answer.
Read the territory, residence and travel provisions as written before you apply. Look for limits on where the insured lives, how long they can be away and what the insurer must be told about a move. Bring those questions to us so they are answered in the context of your application.
If the insured moves abroad after a policy is issued, the result depends on the contract and the insurer’s rules. No outcome should be treated as certain. Do not assume a policy follows you wherever you go.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
How term life insurance fits a green card holder’s situation
Term life insurance covers you for a set period. A death benefit is paid only if the insured dies during that term, under the policy’s terms. The FINRA insurance guidance describes term coverage as coverage for a limited period. It describes whole or permanent coverage as lasting for life, with a cash-value feature.
Premium terms depend on the specific policy and contract. The level-premium period, meaning how long the premium stays the same, is set by the policy. Ask what happens when that period ends. The answer depends on the contract. Renewability and cancellability also depend on the policy.
Some term policies can be converted to permanent coverage. Whether conversion is available, and on what conditions, depends on the policy, the insurer and your insurability at that time. Whole life insurance may build cash value under the contract. That value includes guaranteed and non-guaranteed amounts. Loans or withdrawals can reduce both the cash value and the death benefit, and the terms depend on the policy.
For premium structure, read our level term life insurance guide. For conversion terms, see convertible term life insurance. A reader on an H-1B visa faces a different situation with its own facts, so see H-1B term life insurance.
Health questions, underwriting and what affects issue
A fully underwritten application asks health questions. Issue depends on insurability, which the insurer decides.
Age, health history, occupation and the amount you apply for can affect the premium and the decision. How each factor counts depends on the insurer and the policy. Florida law says that if the insured’s age was misstated, the benefit is what the premium would have bought at the correct age, using the insurer’s rate at the date of issue. Answer accurately, because a mistake can change the benefit. See Fla. Stat. § 627.456.
The insurer reviews the application before any policy is issued. Approval is not guaranteed. Under Fla. Stat. § 627.455, a life policy must provide that it becomes incontestable once it has been in force during the insured’s lifetime for a period of two years after its issue date. The statute excepts nonpayment of premiums and, at the insurer’s option, provisions on disability benefits or additional accidental-death benefits, and how this applies depends on the specific policy’s terms. See Fla. Stat. § 627.455. That clause does not stop defenses based on provisions that exclude or restrict coverage. Florida law also requires a grace period of not less than 30 days for paying any premium after the first, as set out in Fla. Stat. § 627.453.
Beneficiaries, claims and what to ask before you apply
Your beneficiary designation names who receives the death benefit. How and when a claim is paid depends on the policy terms and the insurer’s review. Keep the designation current and make sure names and details match your records.
Under federal tax law, amounts received under a life insurance contract because of the insured’s death are generally not included in gross income. Exceptions apply, such as the transfer-for-value rule and interest paid on proceeds held by the insurer. Tax treatment depends on the policy and your situation. This is general information, not tax advice.
Questions to ask before you apply:
- Which residency and identity documents does the insurer accept?
- What does the policy say about residence and travel?
- How long is the level-premium period, and what happens after it ends?
- Is the policy renewable and cancellable, and on what terms?
- How does the 14-day review period work under this policy?
Can a green card holder get life insurance during a pending immigration case?
It may be possible. The insurer’s rules on documents and status decide the answer for each application.
Does a life policy have a review period?
Life policies carry a 14-day review period after delivery, under the policy’s terms.
Are death benefits taxable?
Tax treatment of life insurance proceeds depends on the policy and your situation, and exceptions apply.
Talk with us about your situation
Many people read about this topic while a family member’s immigration process is underway, or after a move they did not plan. You may not be ready to decide anything yet. That is a reasonable place to be.
Our first meeting is a coverage review. We can talk through your residency status, the documents you have and what you want coverage to do for your family or business. Fees are explained in writing before you decide anything. If you’d like to talk through your situation, contact NR CPAs & Business Advisors.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Important disclosures
Insurance is offered through Nischay Rawal, a licensed insurance agent. States of licensure: Florida. Under Fla. Stat. § 626.112, an agent must be currently licensed and appointed. Under Fla. Stat. § 626.9531, an agent must clearly indicate that he or she is acting as an insurance agent.
Insurance is offered separately from the accounting practice of NR CPAs & Business Advisors. Coverage, premiums and benefits depend on the issuing insurer’s underwriting and the policy’s terms. Life policies carry a 14-day review period under the policy’s terms. If any policy has dividends, dividends are not guaranteed.
This page is general information. It is not tax, legal or immigration advice.
Factors that can affect an application
Residency documentation
Requirements vary by insurer and policy.
Health questions and underwriting
Most applications include health questions. Approval, rating and coverage depend on each insurer's underwriting decisions.
Policy type
Term life, whole life, key person, buy-sell and estate planning life insurance each serve different purposes and follow different terms.
Coverage needs
Rules of thumb can be a starting point for discussion, but the right amount depends on what you need to protect and your own circumstances.
How we approach the first step
A coverage review
We start with a coverage review to talk through your situation, your family or business goals, and the questions you need answered.
Plain-language explanations
We explain insurance terms in plain words so you can understand how each policy works before you decide.
A CPA's view of tax and cash flow
Our CPA firm considers how premiums may affect your cash flow. Tax treatment depends on the policy and your situation, and this is general information, not tax advice.
Support from our team
Our team supports you through scheduling, document collection and follow-up.
Important
Approval, premiums, coverage and benefits depend on the issuing insurer's underwriting, the policy terms and your individual circumstances. Health questions are required for most policies. This page is general information and is not an offer or a recommendation for any particular policy.


