



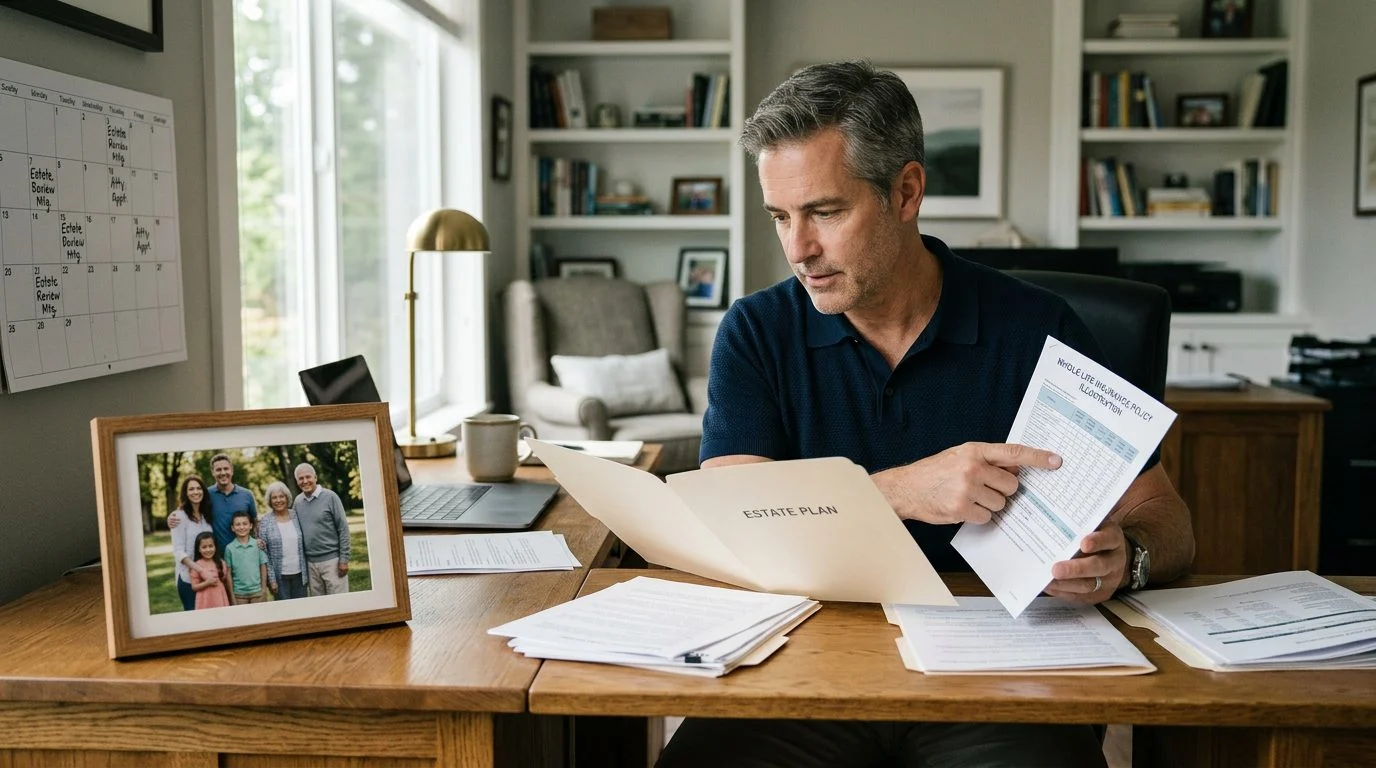
Estate Planning Life Insurance | Florida
Choosing the Right Owner for Life Insurance in Your Estate Plan
Who holds the policy can shape how the death benefit is taxed, who controls it, and how it reaches your family, so the decision deserves a careful look.
By Nischay Rawal · Published November 19, 2026
Deciding who should own life insurance in an estate plan can feel tangled, especially when you’re doing it for a parent or after a loss. It gets simpler once you separate the roles.
The short answer: there is no single right owner. The owner controls the policy, the insured is the person whose life is covered, and the beneficiary receives the death benefit. Those three roles can belong to one person or to several.
These choices decide who can change the policy, who gets the money and whether the proceeds count toward the insured’s estate. This guide walks through the common options in plain words. Your family’s facts matter, so use it as a starting point.
Why owner, insured and beneficiary are separate decisions
Each role answers a different question, so each deserves its own decision. The owner asks who controls the policy. The insured is whose life is covered. The beneficiary is who gets the money.
Take a common example. A husband buys a policy on his own life, owns it himself and names his wife as beneficiary. The setup is simple, but the policy still ties back to his estate in ways worth checking.
Another family might have a wife own a policy on her husband, with their children as beneficiaries and a trust holding the funds. Each setup works differently, and the differences show up later.
A policy set up well on day one can still need review. Marriage, divorce, a new child, a move or a death in the family can each change who should hold which role. Plan to check the policy at those points.
If you're sorting out a parent's policy after a loss, you don't have to work out the owner and beneficiary choices alone; contact NR CPAs & Business Advisors for a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Does life insurance count toward the estate?
Generally, yes, when the insured held certain control over the policy at death. Federal law pulls death benefits into the gross estate when the insured had “incidents of ownership,” such as the right to change the beneficiary, borrow against the policy or surrender it. IRC § 2042 sets that rule.
The federal regulations say “insurance” means life insurance of every description (26 C.F.R. § 20.2042-1).
Estate inclusion is a separate question from income tax. Under IRC § 101(a), amounts paid by reason of the insured’s death generally are not included in the beneficiary’s gross income, subject to listed exceptions. The IRS notes that interest on those proceeds is taxed (IRS life insurance proceeds FAQ).
Under IRC § 2010(c)(3)(A), the basic exclusion amount is $15,000,000, and the inflation adjustment in § 2010(c)(3)(B) applies only to decedents dying in a calendar year after 2026 (IRC § 2010). Check current figures and the estate’s actual facts when you review the plan.
Who can own a policy: the insured, a spouse, an adult child, a business or a trust?
Any of these can be the owner. Each choice moves control to a different place.
- The insured as owner is the simplest setup. The insured keeps control, and the proceeds generally count in the insured’s estate.
- A spouse as owner can keep control within the household. It raises questions about who controls the policy after death or divorce.
- An adult child as owner takes the policy out of the insured’s direct control. Transfer rules apply, as covered in the three-year section below.
- A business as owner is common with key person and buy-sell arrangements. The company or co-owners hold the policy for a business purpose.
- A trust as owner holds the policy under a written trust agreement. A trustee then follows that agreement’s terms.
Ask one question for each option: who can make changes, and who has to agree?
Who should not be named as a beneficiary?
Naming the estate, a young child or a person facing money problems often causes trouble. These choices need extra thought.
Naming the estate sends the proceeds into the estate. Florida law says that when insurance is payable to the insured, the insured’s estate or their executors, the proceeds become part of the insured’s estate and are handled under probate (Fla. Stat. § 222.13). Fla. Stat. § 222.13 reads: “Notwithstanding the foregoing, whenever the insurance, by designation or otherwise, is payable to the insured or to the insured’s estate or to his or her executors, administrators, or assigns, the insurance proceeds shall become a part of the insured’s estate for all purposes and shall be administered by the personal representative of the estate of the insured in accordance with the probate laws of the state in like manner as other assets of the insured’s estate.” Many families don’t intend that result.
A young child can’t manage a large sum directly. Many families name a trust, a custodian or another adult to hold the money until the child is older. Set up those arrangements in advance.
A beneficiary who is going through a divorce or facing debt collection may need a different structure. A trust can add guardrails on how and when money is paid.
Name contingent beneficiaries too. If the first named person dies before the insured, a backup receives the money. Review the form whenever a beneficiary moves, dies or changes circumstances.
How do beneficiary designations work alongside a will?
The beneficiary form on the policy is the document the insurer follows when it pays. You change a beneficiary by filing a new form with the insurer. You don’t change it by editing your will.
Under federal estate tax rules (26 C.F.R. § 20.2042-1), if life insurance proceeds are receivable by or payable to the insured’s estate, they are included in the gross estate; proceeds payable to another named beneficiary are also included if that beneficiary is legally bound to pay taxes, debts, or other charges enforceable against the estate, up to the amount needed for that payment. Florida law also says that once payments are made as directed, the insurer is discharged from further liability and isn’t responsible for how the money is applied.
Outdated forms cause real problems. A form that still names a former spouse can lead to disputes. Keep the will and the policy forms consistent, and check both after any major life change.
How does an irrevocable life insurance trust work?
An irrevocable life insurance trust, called an ILIT, owns the policy and is named as its beneficiary. The person who created it generally can’t change it. The trust pays premiums, holds the policy and distributes proceeds under its written terms.
Premiums usually reach the trust as gifts from the insured. The IRS lists the 2026 gift tax annual exclusion as $19,000 per donee (IRS gift tax FAQs). Many trusts use beneficiary withdrawal rights to support that exclusion, and those rights must be handled correctly each year.
The three-year rule matters when an existing policy moves into a trust. If the insured transfers a policy and dies within three years, IRC § 2035 can pull the proceeds back into the gross estate if the policy would have been included under section 2036, 2037, 2038, or 2042 had the insured kept it; a bona fide sale for adequate and full consideration is excepted.
The trust needs a trustee who is separate from the insured. The trustee pays premiums, keeps records and distributes proceeds. The trust can also pay in installments or for education and support, which is a common reason families choose it.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What are the downsides of putting life insurance in a trust?
The main downside is control. Once an irrevocable trust owns the policy, the insured usually can’t change the beneficiary, borrow against it or surrender it personally.
Setup and upkeep take time and money. Drafting, trustee duties, premium gift records and possible gift tax filings all add work over the years.
Trust terms can be hard to change when a family’s situation shifts. A new child, a move or a changed relationship may not fit the original terms.
A trust also doesn’t replace an updated will, and it doesn’t reduce income tax on its own. It has to fit with the rest of the plan.
Changing or replacing a policy carries its own risks. FINRA notes that surrender charges, cash value and replacement are factors to weigh before any change (FINRA on exchanging a life insurance policy).
A trust isn’t the right answer for every household. Families who want flexibility often prefer ownership that’s easier to change.
Which type of life insurance fits an estate plan?
Term life covers a set period, while whole life covers the insured’s lifetime and includes a cash-value feature (FINRA on insurance products).
Term coverage can fit an obligation that ends on a known date. Whole life can fit a lifetime need, but its premiums usually cost more and must be funded for years.
With participating whole life, dividends are not guaranteed. Illustrations show guaranteed and non-guaranteed values separately, and each one carries its own assumptions and limits. Read both parts together before deciding.
Funding matters too. The premium amount, how long premiums are paid and the cash value all shape how an owner or trust pays for the policy over time. The right type depends on the facts of your family.
How do NRI and cross-border families handle ownership?
Families with relatives abroad, or assets in more than one country, should check payment paperwork and trust terms before a policy is bought.
Where the insured lives, where the beneficiary lives and how payments travel can each change the paperwork. A beneficiary outside the United States may require extra documents before a payment goes out. A trust can set a clear payment path for the family.
If a spouse is not a U.S. citizen, gifts to that spouse follow a separate limit.
Rules in other countries can add steps to the process, and those steps vary by country. Life insurance for NRI households is offered through the licensed agent named below, who is licensed in Florida.
Next step: book a coverage review with the licensed agent
A coverage review is the first meeting. It looks at who owns each policy, who is named on it and how that fits the estate plan.
You may be reading this for a parent after a diagnosis, for a spouse after a death, or for a relative whose plan hasn’t been updated in years. Helpful documents include the policy, the beneficiary forms, the will and any trust papers.
This review doesn’t promise any particular result. It shows what is in place and what may need to change.
Life insurance is offered through Nischay Rawal, a licensed life and health insurance agent in Florida (license G066337, NPN 22274975), separately from the accounting services of NR CPAs & Business Advisors. Any commission the licensed agent earns from an insurer is disclosed to you in writing before any engagement, in an engagement letter that gives the compensation details.
If you’re sorting out a parent’s policy after a loss, you don’t have to work out the owner and beneficiary choices alone. Contact NR CPAs & Business Advisors for a coverage review.
Frequently Asked Questions
Who should own life insurance in an estate plan?
Often the policy is owned by a trust or by another person, not the insured, because when the insured owns the policy, the death benefit is generally counted in their taxable estate. Whether this matters depends on the size of the estate and current tax rules, so the choice should be reviewed with a licensed agent.
What is an irrevocable life insurance trust, and when is it used?
An irrevocable life insurance trust is a trust that owns a life insurance policy and is named as beneficiary of the death benefit, and the insured generally gives up control of the policy. Transferring an existing policy into the trust can pull the proceeds back into the estate if the insured dies within three years of the transfer.
Can a spouse or adult child own a policy on the insured’s life?
Yes, a spouse or adult child can own a policy on your life if they have an insurable interest in you, which generally means a financial or family relationship that makes the policy valid. The owner controls the policy, so ownership should be decided together with the beneficiary and the rest of the estate plan.
Should the policy owner and the beneficiary be the same person?
Not always, because the owner controls the policy while the beneficiary receives the death benefit. Naming a trust or the estate as beneficiary can change how and when the money is paid, so these choices should be coordinated with the estate documents.
What a coverage review looks at
Who owns the policy
We compare owner choices, including the insured, a spouse, a trust or a business, and how each one affects control of the death benefit.
Estate size and tax exposure
We look at the size of the estate and how the death benefit could be counted in it, so the ownership choice fits your situation.
Protecting your loved ones
We help you think through who should receive the benefit, when, and under what terms, so the plan supports the people you care about.
Cash flow and premiums
We review how premium payments fit your budget and cash flow, alongside the tax picture from our CPA practice.
Review before you change anything
Do not cancel, replace or transfer an existing policy or change its owner until it has been reviewed, because changes can carry tax and coverage consequences. Life insurance is offered through Nischay Rawal, a licensed life and health insurance agent in Florida (license G066337, NPN 22274975), separately from the accounting services of NR CPAs & Business Advisors.
Common owner choices
The insured
Owning the policy yourself is simple to set up, but the death benefit can be counted in your taxable estate.
A spouse
A spouse may be considered as owner in some plans, which can change who controls the policy and how it is handled later.
An irrevocable life insurance trust
A trust can own the policy and name a trustee to manage the proceeds for beneficiaries under the terms you set.
A business entity
Key person and buy-sell policies are often owned by the business or by the owners, tied to the business succession plan.


