



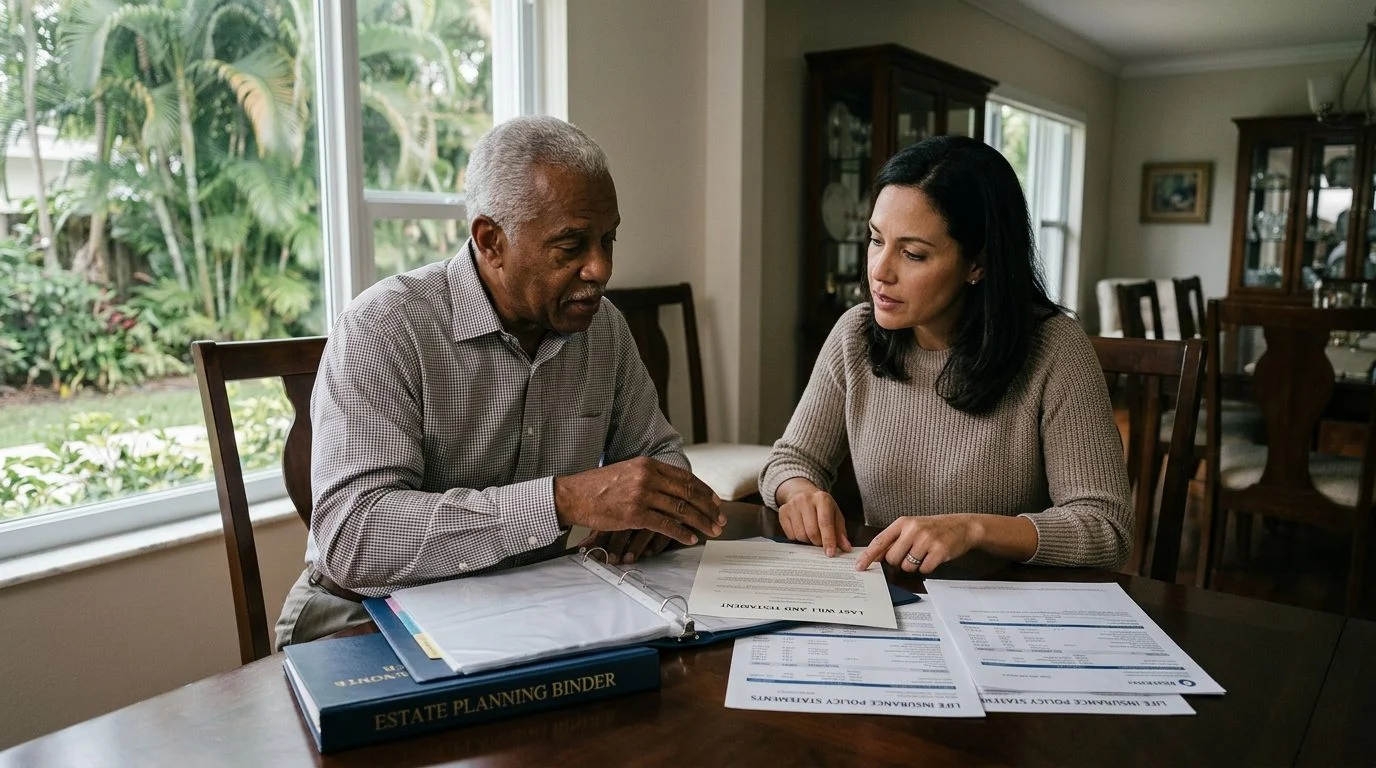
Estate Planning Life Insurance | Miami, Florida
Plan how your loved ones receive life insurance proceeds
Talk with a licensed agent about naming beneficiaries, coordinating your policy with the rest of your estate plan, and how a death benefit can reach your family.
By Nischay Rawal · Published November 15, 2026
If you are planning an estate in Miami, you likely want to know who receives a life insurance payout and when. Estate planning life insurance pays a death benefit to the beneficiary named in the policy, so it can support a will or trust. This guide explains the key pieces in plain words, so your family can be protected with fewer surprises.
How estate planning life insurance works in Miami-Dade
Estate planning life insurance is a policy whose death benefit supports the goals of a will, a trust or a business agreement. The policy is a contract between you and an insurer. The insurer named on the policy is the company that pays the benefit, so check that name on every document.
Miami-Dade households use this planning in several common situations. Homeowners may want cash to cover a mortgage. Parents with young children may want funds set aside for a trust. Business owners may need money to fund a partner’s share. Families with property or relatives in more than one country may want clear payment rules.
The right policy type, death benefit amount and owner depend on your facts. A household with adult children and a modest estate faces different choices than a business owner with a partner. A plan can also drift out of date. Marriage, divorce, a new child or a change in business ownership can change who should receive the benefit.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Does life insurance go to next of kin?
No, not automatically. A death benefit is paid to the beneficiary named in the policy, not to next of kin by default. Under Fla. Stat. § 222.13, insurance proceeds on a Florida resident’s life are exempt from the insured’s creditors unless the policy or a valid assignment provides otherwise.
The same statute gives a different result when the policy names the insured, the insured’s estate or the executors. In that case, the proceeds become part of the estate. A personal representative then administers them under the probate laws, like other estate assets.
This is why a blank or outdated beneficiary line matters. If no living beneficiary is named, the payout may end up in the estate, depending on the policy’s terms. Review beneficiary designations after a marriage, divorce, birth or death in the family.
Does life insurance create an immediate estate?
Life insurance proceeds can become part of the insured’s estate. Under Fla. Stat. § 222.13, proceeds payable to the insured, the insured’s estate or the executors become part of the insured’s estate for all purposes. Fla. Stat. § 222.13 reads: “Notwithstanding the foregoing, whenever the insurance, by designation or otherwise, is payable to the insured or to the insured’s estate or to his or her executors, administrators, or assigns, the insurance proceeds shall become a part of the insured’s estate for all purposes and shall be administered by the personal representative of the estate of the insured in accordance with the probate laws of the state in like manner as other assets of the insured’s estate.” It adds a death benefit that a named beneficiary can receive when the insured dies.
The main value here is cash, often called liquidity. The proceeds can give heirs or a trustee money for final expenses, debts or the cost of holding property. What the money covers depends on the plan’s terms and the estate’s needs.
Cash on hand may reduce pressure to sell a home or a business share quickly. It does not guarantee that a sale will never be needed. A common planning mistake is naming no contingent beneficiary. If the first beneficiary dies before the insured, the payout has no clear path without one.
Whole life and term: guaranteed and non-guaranteed values
Term life insurance covers the insured for a set period. Whole life insurance covers the insured for life and includes a cash-value feature. FINRA publishes general investor information about insurance products on its insurance guidance page.
For whole life, keep guaranteed and non-guaranteed values apart. Guaranteed values are amounts the contract states. Dividends are not guaranteed. They depend on the insurer’s results, and they can change.
An illustration of future cash value is not a promise. It is shown with the policy’s limitations and exclusions, and those limits matter as much as the numbers. Before you change an existing policy, weigh surrender charges, cash value and the cost of replacing it. FINRA’s guidance on exchanging a policy covers questions to consider before exchanging a life insurance policy.
Premiums, renewability and any age-based change depend on the policy form and your facts. Ask the insurer for the policy documents, and read the limits and exclusions before you decide.
Trusts, policy ownership and coordinating with your estate attorney
Three roles matter in every plan. The insured is the person whose life is covered. The owner controls the policy. The beneficiary receives the benefit. Naming each one correctly is the core of the plan.
Under 26 U.S.C. § 2042, proceeds receivable by beneficiaries other than the executor can count in the insured’s gross estate. That applies when the insured held any incident of ownership in the policy at death. IRC § 2042 reads: “For purposes of the preceding sentence, the term “incident of ownership” includes a reversionary interest (whether arising by the express terms of the policy or other instrument or by operation of law) only if the value of such reversionary interest exceeded 5 percent of the value of the policy immediately before the death of the decedent.”
An irrevocable life insurance trust can hold a policy. An estate attorney sets it up, not the insurance agent alone. The coverage review covers the insurance side, and the trust documents come from the attorney.
Timing also matters. Under 26 U.S.C. § 2035, property transferred within the three years before death can still be included in the gross estate if it would have been included in the decedent’s gross estate under section 2036, 2037, 2038, or 2042 had the transferred interest been retained. The 2026 basic exclusion amount for estate and gift tax is $15,000,000. Whether federal estate tax affects your family depends on the facts.
Business owners: key person and buy-sell coverage in the estate plan
Key person insurance is a policy on an owner or essential employee. The business usually owns and pays for it. It can help the company manage the financial effect of that person’s death.
Buy-sell agreement insurance funds the purchase of a deceased owner’s share. The surviving owners and the estate then have clear terms. Under 26 U.S.C. § 2703, an option, agreement or other right to buy property for less than its fair market value, or a restriction on the right to sell or use it, is disregarded for valuation unless each of three requirements is met. It must be a bona fide business arrangement, not a device to transfer property to family for less than full value, and it must have terms comparable to arm’s-length deals.
Link each policy to the owner’s personal plan. Ask who owns the policy, who pays premiums and who receives the proceeds. Those answers can differ for the company and the owner’s family. How the proceeds are used depends on the agreement and the facts of the company.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
NRI and Indian-American families with relatives abroad
NRI life insurance covers a person living outside the United States, or a family whose beneficiaries live abroad. Plan around both the insured’s residence and the beneficiary’s access to funds.
Before a policy is issued, confirm with your agent how a beneficiary living abroad would receive payment, which currency a payout uses and what paperwork a claim requires. Put these questions to the insurer in writing before you buy.
Federal tax treatment can differ for nonresidents. Under 26 U.S.C. § 2105(a), the amount receivable as insurance on the life of a nonresident not a citizen of the United States is not deemed property within the United States. That rule covers nonresident non-citizens only, so confirm your family’s status with the relevant advisers.
Eligibility, underwriting and policy terms depend on the insured’s residence and the insurer’s rules. Check cross-border tax and legal points with the relevant advisers before you act.
How the coverage is offered, how the agent is paid, and the next step
Insurance is offered through a licensed agent, separately from the accounting practice. Life insurance is offered through Nischay Rawal, a licensed life and health insurance agent in Florida (license G066337, NPN 22274975), separately from the accounting services of NR CPAs & Business Advisors.
Florida law requires an agent to say clearly that they act as an insurance agent when selling insurance. See Fla. Stat. § 626.9531. The agent is paid a commission on insurance sold. Under Fla. Stat. § 473.3205, a CPA firm engaged in the practice of public accounting that accepts a commission for the sale of a product or service to a client must disclose that fact to the client in writing in accordance with rules adopted by the board. Compensation details are disclosed in writing before any engagement. Fees for the coverage review and for any accounting work are set out in writing before work begins.
Readers in Fort Lauderdale, West Palm Beach, Orlando, Tampa and Jacksonville can contact the firm about a coverage review.
Does life insurance go to next of kin in Florida?
Usually not. The death benefit goes to the named beneficiary. If the policy names the insured, the insured’s estate or the executors, the proceeds shall become part of the estate for all purposes and are administered under the probate laws.
Is estate planning life insurance subject to estate tax?
It can be counted in the gross estate, depending on ownership. Estate tax questions depend on the specific circumstances of each family.
Can NRI life insurance cover a relative abroad?
It may be possible. Eligibility depends on residence and the insurer’s rules.
If a recent marriage, a new child or a change in your business has you unsure who would receive your policy’s benefit, contact NR CPAs & Business Advisors today to schedule a coverage review.
What a coverage review covers
Protecting your loved ones
We look at who would receive the death benefit and whether your policy supports the plan you want for your family.
Beneficiary and ownership choices
Naming the beneficiary and the policy owner are decisions that shape how proceeds are paid out. We walk through the options in plain terms.
Coordination with your estate plan
We review how life insurance fits alongside your wills, trusts and other arrangements so the pieces work together.
A CPA's view of tax and cash flow
Our accounting perspective helps you weigh premium costs, tax considerations and cash flow before you decide.
Who offers this insurance
Life insurance is offered through Nischay Rawal, a licensed life and health insurance agent in Florida (license G066337, NPN 22274975), separately from the accounting services of NR CPAs & Business Advisors.
Questions to bring to your coverage review
Who should receive the proceeds?
Decide on the primary and backup beneficiaries, and consider how the named person would receive and use the funds.
Who should own the policy?
The owner controls the policy's changes and values. Choosing the owner is a planning decision, not just a formality.
How does insurance fit with your estate?
Compare the policy with your existing estate documents, so the death benefit supports your goals rather than working against them.
What will it cost over time?
Review the premium, the payment period and the policy's terms, including any limitations and exclusions, before you commit.


