



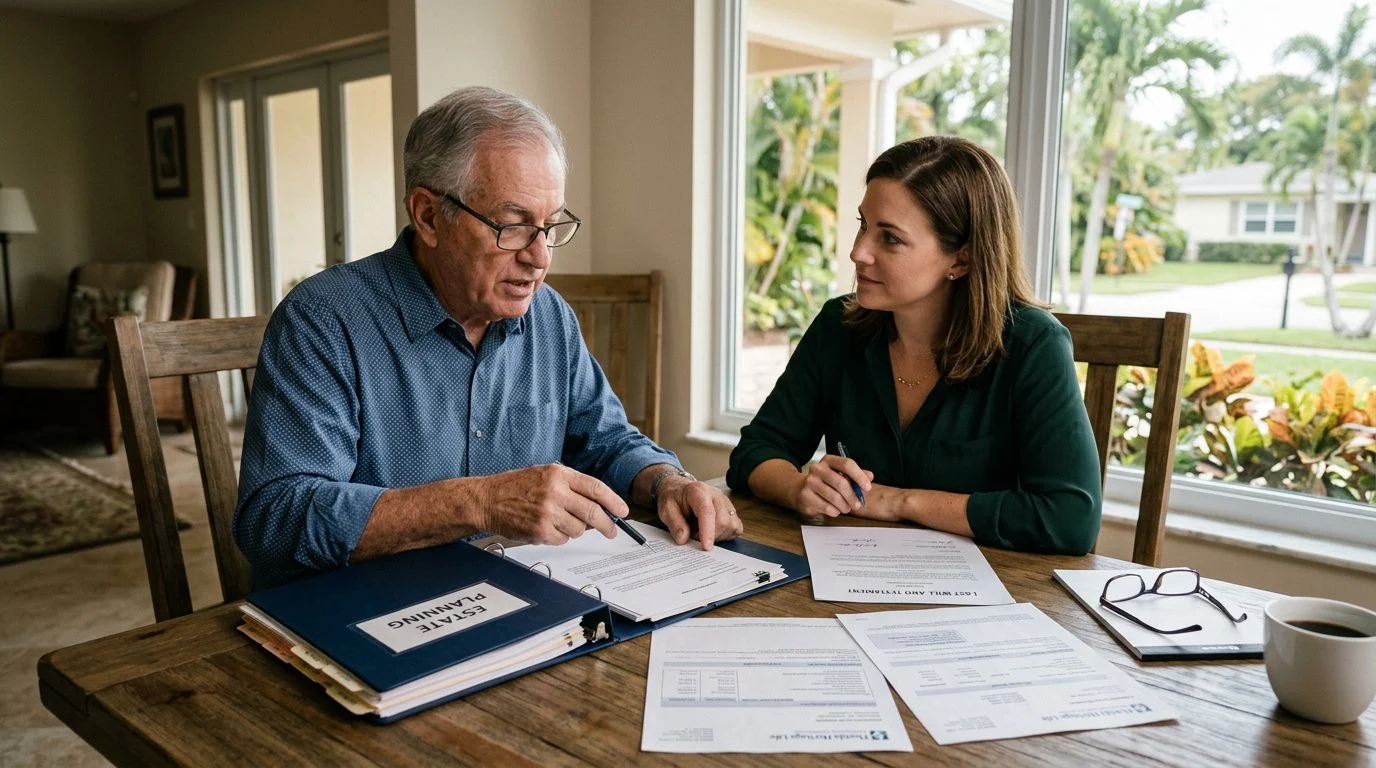
Fort Lauderdale, Florida | Estate Planning Life Insurance
Protect the Plan You Have Built for Your Family
Life insurance can work alongside your wills, trusts and cash flow. Here is how a licensed agent and a CPA-led firm approach that planning for Fort Lauderdale households.
Licensed in Florida
G066337
Florida life insurance agent license
22274975
National Producer Number (NPN)
By Nischay Rawal · Published November 19, 2026
If you’re reviewing an estate plan in Fort Lauderdale, you probably want to know where the life insurance money goes. When a named beneficiary is alive at the insured’s death, the death benefit generally goes to that person under the policy, not to the estate.
Does Life Insurance Go to an Estate in Fort Lauderdale?
Usually not, when a living beneficiary is named on the policy. The beneficiary form and the policy contract control the result, not the will alone.
For a Florida resident, life insurance proceeds are exempt from the insured’s creditors unless the policy or a valid assignment provides otherwise. That exemption does not apply when the insurance, by designation or otherwise, is payable to the insured, to the insured’s estate, or to his or her executors, administrators, or assigns; then the proceeds become part of the insured’s estate for all purposes. That protection comes from Florida’s statute on life insurance proceeds.
The estate may receive the policy proceeds when the policy names the estate itself as beneficiary. In both cases, the proceeds become part of the insured’s estate, and the personal representative handles them under probate law. Fla. Stat. § 222.13 reads: “Notwithstanding the foregoing, whenever the insurance, by designation or otherwise, is payable to the insured or to the insured’s estate or to his or her executors, administrators, or assigns, the insurance proceeds shall become a part of the insured’s estate for all purposes and shall be administered by the personal representative of the estate of the insured in accordance with the probate laws of the state in like manner as other assets of the insured’s estate.”
A common mistake is an old beneficiary form that names someone who has died, with no backup named. That can send the money into the estate, where court steps and delays follow.
If a parent's policy still names an estate as beneficiary, we can help you review it and plan the next step with you, so the money reaches the right people. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
How Beneficiary Designations and Probate Work Together
A named beneficiary usually receives the death benefit directly, outside the probate process.
Life insurance with a living beneficiary usually sits outside that process, so the beneficiary form does most of the work.
Name a contingent beneficiary too. This is the backup who receives the benefit if the first beneficiary dies before the insured. Without one, the proceeds may end up in the estate.
Review your forms whenever the family changes. Common triggers include a remarriage, a new child, or a parent who moves to Florida from abroad. A parent who relocates from India, for example, may hold a policy whose beneficiary form predates the move. Check that the will and the policy tell the same story.
Using an Irrevocable Life Insurance Trust for Estate Planning
An irrevocable life insurance trust, often called an ILIT, is a trust that owns the policy. The insured gives up ownership rights, so the insured holds no incidents of ownership at death. Federal law includes life insurance in the gross estate when those incidents are held, so the setup matters (IRC § 2042).
The trustee pays the premiums. The insured usually transfers money to the trust to cover them. For 2026, the IRS gift tax FAQ lists the annual exclusion at $19,000 per donee.
Timing matters when an existing policy moves into a trust. If the insured transfers a policy and dies within three years, the proceeds can still be pulled back into the gross estate if the policy would have been included under section 2036, 2037, 2038, or 2042 had the insured kept it (IRC § 2035). A bona fide sale for full value is an exception. IRC § 2035 reads: “Subsection (a) and paragraph (1) of subsection (c) shall not apply to any bona fide sale for an adequate and full consideration in money or money’s worth.”
An estate attorney drafts the trust document with the family. Our role covers the policy, the premium cash flow and the tax view.
Life Insurance as Estate Liquidity for Florida Families
Estate planning life insurance can give an estate cash when it is needed most. That matters when most of the estate is not cash.
An estate can hold a home, a business interest or investments that take time to sell. Meanwhile, debts, final expenses and settlement costs come due in cash. A cash death benefit can give the personal representative or trustee money to pay those bills without a forced sale of the family home or business shares.
Florida adds a timing point. A lump-sum death payment must include interest from the day the insurer receives written due proof of death. The rate must be at least equal to a Moody’s corporate bond index (Fla. Stat. § 627.4615).
Households in Broward County may hold Fort Lauderdale real estate, a closely held business or assets in more than one country. Each of those can change how much cash the estate needs.
Term or Whole Life: Choosing the Policy Type for an Estate Plan
Term life covers a set period, while whole life covers the insured’s lifetime and includes a cash-value feature. FINRA’s overview of insurance products describes that difference.
Term coverage often fits a need that ends, such as a mortgage or a business loan. Whole life often fits a need that lasts, such as estate liquidity or a planned gift to heirs.
Dividends, where a policy pays them, are not guaranteed. An illustration should show guaranteed and non-guaranteed values separately, with equal care for each limit and assumption.
If an insurance agent recommends surrendering a life insurance policy or annuity that has a cash value, and does not recommend using the proceeds to fund or purchase another annuity or life insurance policy, Florida law requires the agent to provide written information about that policy before the surrender. The information includes, but is not limited to, the estimated surrender charge, the possibility of tax consequences and the amount of any forfeited death benefit (Fla. Stat. § 627.4553).
Florida and Federal Tax Context for Life Insurance in an Estate
Death benefits are generally excluded from the beneficiary’s federal income tax. Interest paid on those proceeds is taxable (IRS life insurance proceeds FAQ).
The benefit can still count in the insured’s taxable estate. The gross estate includes insurance receivable by the executor, and insurance receivable by other beneficiaries when the insured held incidents of ownership at death (IRC § 2042). A reversionary interest counts only if its value exceeded 5 percent of the policy’s value just before death.
Under IRC § 2010, the basic exclusion amount is $15,000,000, and that amount is adjusted for inflation for decedents dying in calendar years after 2026 (26 U.S.C. § 2010). A surviving spouse may take a deceased spouse’s unused exclusion amount into account only if the deceased spouse’s executor files an estate tax return that computes that amount and makes the election on that return, and no election may be made if that return is filed after the time prescribed by law (including extensions) for filing such return. Tax results depend on the facts of each estate, including lifetime gifts.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Start a Coverage Review with NR CPAs & Business Advisors
A coverage review looks at your current policies, owners, beneficiaries and estate goals before anything changes. Our team checks each policy form, the premium payments and who holds ownership rights. Then we compare those facts with the family’s estate plan and cash needs.
Fees for a coverage review are disclosed in writing before any work begins.
Life insurance is offered through Nischay Rawal, a licensed life and health insurance agent in Florida (license G066337, NPN 22274975), separately from the accounting services of NR CPAs & Business Advisors.
NR CPAs & Business Advisors is a CPA firm based in Miami. We help families, professionals and business owners in Florida, including Indian-American households and NRI family members with U.S. estate interests.
Frequently asked questions
Does life insurance go to the estate in Florida?
Not when a living beneficiary is named.
Do life insurance proceeds avoid probate?
A named beneficiary generally receives them directly.
Are life insurance death benefits taxable?
The death benefit is generally excluded from federal income tax. Interest paid on the proceeds is taxable.
If a parent’s policy still names an estate as beneficiary, contact our team to schedule a coverage review and protect your loved ones.
What a coverage review covers
Protecting loved ones
We look at who depends on your income and how a policy could help them keep their home and plans in place.
Fitting the estate plan
We review how beneficiary designations and policy ownership line up with the rest of your estate documents.
Cash flow with a CPA view
Premium payments are compared with your budget and tax picture so the plan stays practical over time.
Plain-language answers
Insurance terms are explained in everyday words, so you know what each option does and does not do.
Who offers the insurance
Life insurance is offered through Nischay Rawal, a licensed life and health insurance agent in Florida (license G066337, NPN 22274975), separately from the accounting services of NR CPAs & Business Advisors.
Ways a policy can support your estate
Providing liquidity
Life insurance proceeds may help cover settlement costs so heirs are not forced to sell property quickly.
Naming beneficiaries
Beneficiary designations on a policy can be set to match your wishes and your overall estate plan.
Balancing inheritances
A policy can help even out gifts among heirs when one asset, such as a family business, is hard to divide.
Reviewing over time
Your coverage review can be revisited as your family, property and tax situation change.


