What Is Section 179 and How Much Can You Claim?

Section 179 is a provision of the tax code that lets a business deduct the full purchase price of qualifying equipment and property in the year it is placed in service, instead of depreciating that cost across several years. For 2026, the maximum deduction is $2,560,000, and it phases out dollar for dollar once total qualifying property placed in service passes $4,090,000. Property must be used more than 50% for business, and the deduction cannot exceed your active trade or business income for the year.
The sections below cover the current limits and phase-out points, which property qualifies and which does not, how vehicles are treated under their own separate caps, the calculation worked at real dollar figures, how Section 179 stacks with bonus depreciation, when declining the election is the better decision, the mistakes that trigger recapture, and the filing steps and deadlines involved.
Key Takeaways
- The 2026 Section 179 deduction limit is $2,560,000 of qualifying property placed in service during the year.
- The deduction shrinks dollar for dollar above $4,090,000 of total qualifying purchases and disappears entirely at $6,650,000.
- Property has to be placed in service by December 31, not merely purchased or ordered.
- Business use must exceed 50%, and the deduction is prorated by the business use percentage.
- Section 179 cannot create or increase a net operating loss. It is capped at active trade or business income, with unused amounts carried forward indefinitely.
- Heavy SUVs rated between 6,001 and 14,000 pounds gross vehicle weight are capped at $32,000 of Section 179 deduction for 2026.
What Is Section 179?
Section 179 is an election that allows a business to expense the cost of qualifying property immediately rather than recovering that cost through annual depreciation deductions. The provision sits in Section 179 of the Internal Revenue Code, and it exists to encourage small and mid-size businesses to invest in equipment.
Standard depreciation spreads a purchase across a recovery period set by the asset class. A $60,000 piece of machinery on a seven-year recovery schedule produces a deduction of a few thousand dollars in year one and continues trickling into the eighth calendar year. Section 179 collapses that schedule into a single deduction in the year the machinery starts working.
Collapsing the schedule changes cash flow rather than total deductions. The full cost of the asset gets deducted either way, and Section 179 simply moves the benefit forward, which matters most to a business that needs the cash now or expects to sit in a higher tax bracket this year than next.
The election is not automatic. A business has to affirmatively claim it on the return, asset by asset, and can elect a partial amount on any given purchase rather than expensing the whole thing.
What Are the Benefits of the Section 179 Deduction in 2026?
The benefits of the Section 179 deduction in 2026 are immediate cash flow from a first-year write-off, a deduction limit more than doubled from where it stood two years ago, and permanent inflation indexing that removes the annual uncertainty businesses used to face. The One Big Beautiful Bill Act rebuilt the provision, raising the deduction cap from $1.25 million to $2.5 million and the phase-out threshold from $3.13 million to $4 million, effective for tax years beginning after December 31, 2024.
Permanence is the underrated part of that change. Both figures are now fixed features of the code with annual inflation adjustments, which is why the 2026 numbers arrived at $2,560,000 and $4,090,000 rather than reverting. Businesses planning multi-year capital purchases can now model the deduction forward with reasonable confidence instead of waiting on year-end legislation.
The cash flow effect compounds for growing companies. A business that expenses a $200,000 equipment package in the year of purchase frees the tax savings for the next hire, the next location, or debt service, rather than waiting seven years to collect the same total deduction in slices.
How Much Can I Depreciate With Section 179?
You can deduct up to $2,560,000 of qualifying property under Section 179 for tax years beginning in 2026, according to IRS Revenue Procedure 2025-32. That ceiling applies per taxpayer rather than per asset, so it covers the combined cost of everything you elect to expense during the year.
Item202420252026Maximum Section 179 deduction$1,220,000$2,500,000$2,560,000Phase-out begins at$3,050,000$4,000,000$4,090,000Deduction fully eliminated at$4,270,000$6,500,000$6,650,000Heavy SUV cap (6,001 to 14,000 lbs GVWR)$30,500$31,300$32,000Minimum business use requiredMore than 50%More than 50%More than 50%
Sources: IRS Revenue Procedure 2025-32 (2026 inflation-adjusted amounts under Section 179(b)); One Big Beautiful Bill Act, Public Law 119-21 (2025 statutory increase); IRS inflation adjustments for prior years.
The phase-out mechanism is where most published guidance stops short. Every dollar of qualifying property placed in service above $4,090,000 reduces the available deduction by one dollar, so a business placing $5,000,000 in service sees the ceiling drop to $1,650,000. Cross $6,650,000 in total placements and the Section 179 deduction reaches zero, which is the deliberate design that confines the provision to small and mid-size businesses.
Entity structure never limits eligibility, though it does shape how the deduction lands. Sole proprietorships, partnerships, S corporations, C corporations, and LLCs all qualify, but the dollar limit and the income limit apply at the owner level for pass-through entities, meaning a partner receiving Section 179 allocations from two partnerships still faces one combined ceiling. Getting that structure right during business formation avoids allocation problems later.
Can You Deduct 100% Under Section 179?
You can deduct 100% of a qualifying asset's cost under Section 179, provided the asset is used entirely for business, total placements stay under the phase-out threshold, and your active trade or business income covers the deduction. Those three conditions all have to hold at once.
Partial business use produces a partial deduction. An asset used 70% for business yields 70% of its cost as the Section 179 base, and business use at or below 50% disqualifies the asset from Section 179 entirely. Careful tax planning around business use percentages before the purchase closes is usually easier than reconstructing usage records after the fact.
Who Qualifies for the Section 179 Deduction?
Any business that purchases, finances, or leases qualifying property and places it in service during the tax year qualifies for the Section 179 deduction. There is no revenue floor, no employee count requirement, and no industry restriction.
The practical gate is the income limitation rather than the entity. A business with no active trade or business income for the year cannot use the deduction currently, though it can carry the amount forward. Nonprofits and other entities without taxable business income face the same constraint.
What Qualifies for a 179 Deduction?
Tangible personal property purchased for use in a trade or business qualifies for a 179 deduction, along with off-the-shelf computer software and certain improvements to nonresidential real property. The property can be new or used, as long as it is new to your business and was not acquired from a related party.
Qualifying categories include machinery and manufacturing equipment, computers and peripherals, off-the-shelf software, office furniture and fixtures, business vehicles subject to the separate limits below, tools, medical and dental equipment, agricultural equipment, single-purpose agricultural and horticultural structures, storage facilities used in connection with distribution, and property used to furnish lodging in limited circumstances.
Equipment-heavy operations reach the ceiling faster than most owners expect. A single kitchen build-out can consume six figures of qualifying property between refrigeration, ventilation, ranges, and point-of-sale hardware, which is why we run capital purchase timing separately in restaurant accounting engagements.
Software-driven businesses qualify on a different mix of assets. Off-the-shelf software licensed for general commercial use is eligible, while custom-developed internal software generally is not, and the distinction matters for the tech companies whose largest capital line is rarely physical equipment.
Does Section 179 Apply to Building Improvements?
Section 179 applies to specific building improvements on nonresidential real property, including roofs, heating and air conditioning systems, fire protection and alarm systems, and security systems. According to the IRS, these fall under the qualified real property category added to the eligible list.
Qualified improvement property also qualifies. That category covers interior improvements to an existing nonresidential building placed in service after the building itself, excluding enlargements, elevators, escalators, and changes to the internal structural framework. The building shell never qualifies, no matter how the improvements are financed.
Does HVAC Qualify for Section 179?
HVAC systems qualify for Section 179 when installed on nonresidential real property used in a trade or business. Heating, ventilation, and air conditioning equipment was added to the qualified real property list and can be expensed in the year placed in service rather than depreciated over 39 years.
Residential rental property is excluded from this treatment. An HVAC replacement in an apartment building follows standard depreciation rules, while the same unit installed in a retail storefront or office suite is eligible.
How Do I Know if My Asset Qualifies for the Section 179 Expense?
Your asset qualifies for the Section 179 expense if it is tangible, depreciable, purchased for business use, used more than 50% for business, acquired from an unrelated party, and placed in service during the tax year. Failing any single test disqualifies the asset.
The related-party rule catches more purchases than people anticipate. Property bought from a spouse, sibling, ancestor, descendant, or a controlled entity is ineligible regardless of price paid or arm's-length documentation. Inherited property and gifted property are ineligible for the same structural reason: neither involves a purchase.
What Assets Are Not Eligible for Section 179?
Assets not eligible for Section 179 include land, buildings and their structural components, inventory, property held for investment, property acquired from related parties, property used outside the United States, and property used 50% or less for business. Air conditioning and heating units were historically excluded but now qualify as noted above.
Land carries the clearest exclusion, and it flows from a basic depreciation principle rather than from Section 179 specifically. Land does not wear out, become obsolete, or get used up, so it has no determinable useful life and no depreciation schedule for Section 179 to accelerate.
What Type of Property Cannot Be Depreciated?
Property that cannot be depreciated includes land, inventory held for sale, property placed in service and disposed of in the same year, equipment used to build capital improvements, and most intangible assets such as leases and franchise rights. Personal-use property is also excluded, since depreciation requires business or income-producing use.
Intangibles follow a separate recovery system. Purchased goodwill, going concern value, and certain acquired intangibles are amortized over 15 years under Section 197 rather than depreciated, and none of them are Section 179 eligible.
What Assets Never Depreciate?
Land never depreciates, and neither do collectibles, fine art, antiques held for display, or inventory. Each fails the same test: depreciation requires an asset that loses value through use, wear, or obsolescence over a determinable period.
Land improvements are a separate matter and do depreciate. Parking lots, fencing, landscaping, and drainage systems carry a 15-year recovery period even though the land beneath them carries none, and some of those improvements qualify for Section 179 treatment.
How Many Years Can a Property Be Depreciated?
Property is depreciated over recovery periods set by asset class, ranging from three years to 39 years. Computers and vehicles run five years, office furniture and most equipment run seven years, land improvements and qualified improvement property run 15 years, residential rental property runs 27.5 years, and nonresidential real property runs 39 years.
Those recovery periods are what Section 179 and bonus depreciation compress into year one. A 39-year recovery period on a $150,000 building improvement produces roughly $3,800 of annual deduction under standard rules, which is the comparison that makes immediate expensing so attractive to owners making improvement decisions.
What Vehicles Can You Write Off Using Section 179?
Vehicles follow the general rules above and then add several of their own, so this section handles them separately before the calculation section returns to rules that apply to every asset class.
Vehicles you can write off using Section 179 include those with a gross vehicle weight rating above 6,000 pounds, work vehicles with no personal-use potential, and passenger cars subject to strict annual dollar caps. Gross vehicle weight rating, printed on the driver's door jamb sticker, is the number that determines which set of limits applies.
Three tiers govern the outcome. Vehicles rated at 6,000 pounds or less fall under the Section 280F passenger automobile limits. SUVs rated between 6,001 and 14,000 pounds face the $32,000 Section 179 cap for 2026. Vehicles rated above 14,000 pounds, along with certain work vehicles, escape both restrictions and can be expensed up to the full Section 179 limit.
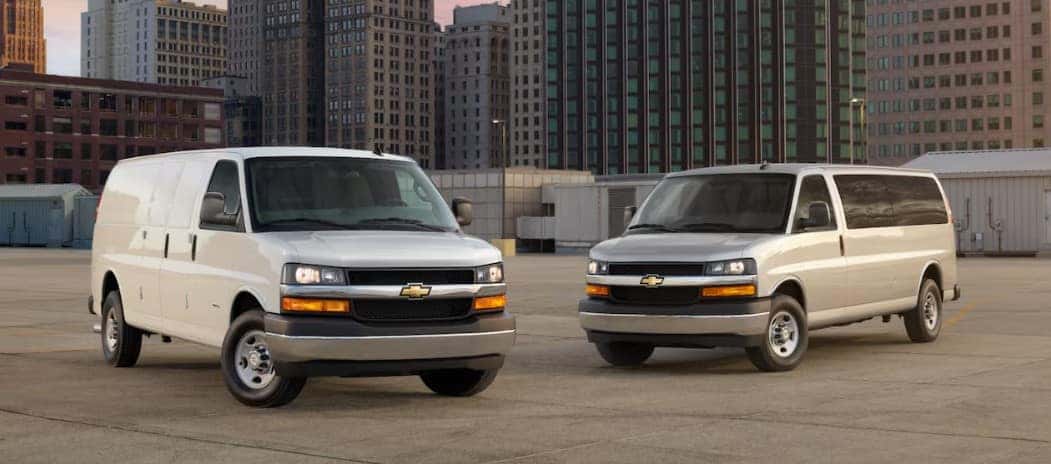
The work vehicle exemption covers specific configurations rather than general utility. Cargo vans with no seating behind the driver's row and no body section extending more than 30 inches ahead of the windshield qualify, as do pickups with a cargo bed of at least six feet that is not readily accessible from the passenger compartment, and vehicles designed to seat more than nine passengers behind the driver.
Can You Write Off 100% of a 6000 lb Vehicle?
You can write off 100% of a vehicle rated above 6,000 pounds gross vehicle weight, but not through Section 179 alone. Section 179 caps the deduction on an SUV in the 6,001 to 14,000 pound range at $32,000 for 2026, according to IRS Revenue Procedure 2025-32, and bonus depreciation covers whatever remains.
A worked example shows the interaction. A $95,000 SUV rated at 6,500 pounds and used 100% for business yields $32,000 under Section 179, and the remaining $63,000 of basis is eligible for 100% bonus depreciation, producing a full first-year write-off. Reduce business use to 80% and both figures scale down against a $76,000 deductible base.
Passenger vehicles at or below 6,000 pounds cannot reach anything close to that result. Revenue Procedure 2026-15 caps first-year depreciation on a passenger automobile placed in service in 2026 at $20,300 when bonus depreciation applies and $12,300 when it does not, with succeeding-year limits of $19,800, $11,900, and $7,160 thereafter. Those caps apply to trucks and vans as well as cars, and they override any larger Section 179 amount the arithmetic would otherwise produce.
Do Used Vehicles Qualify for Section 179?
Used vehicles qualify for Section 179 as long as the vehicle is new to your business and was not acquired from a related party. The provision has never required a first-time-ever purchase, only first use by the taxpayer claiming it.
Bonus depreciation now follows the same standard. Used equipment and used vehicles are eligible for 100% bonus depreciation provided the business had no prior use of the asset, which removed one of the historical reasons to favor Section 179 over bonus on secondhand purchases.
Can You Take Section 179 on a Leased Vehicle?
You cannot take Section 179 on a vehicle under a true operating lease, because you do not own the asset. Lease payments are deducted as an operating expense instead, reduced by a lease inclusion amount published annually by the IRS for higher-value vehicles.
Capital leases produce the opposite answer. A lease structured as a financing arrangement, where ownership transfers at the end or a bargain purchase option exists, is treated as a purchase for tax purposes and does support a Section 179 election. The label on the contract matters far less than its substance.
How Long Do You Have to Keep a Vehicle Under Section 179?
You have to maintain more than 50% business use of the vehicle for its entire recovery period, which is five years for most vehicles. Selling the vehicle or dropping business use to 50% or less before that period ends triggers recapture.
Recapture reverses the benefit rather than penalizing it outright. The excess of the Section 179 deduction claimed over what standard depreciation would have produced becomes ordinary income in the year business use fails, reported on Form 4797. A vehicle expensed in year one and converted to mostly personal use in year three can generate a substantial income pickup at exactly the moment the owner expected none.
How Do I Calculate My Section 179 Expense?
You calculate your Section 179 expense by totaling qualifying property placed in service, adjusting for business use percentage, applying the phase-out reduction, and capping the result at your active trade or business income. The sequence runs in that order, and each step can reduce the amount the previous step produced.
- Total the cost of qualifying property placed in service. Include everything eligible, whether purchased outright or financed, and use the full cost rather than amounts paid during the year.
- Multiply each asset by its business use percentage. An asset used 80% for business contributes 80% of its cost. Assets at or below 50% business use drop out entirely.
- Compare total placements to the phase-out threshold. Subtract $4,090,000 from total qualifying property placed in service. A negative result means no reduction applies.
- Reduce the $2,560,000 ceiling by any excess. Place $4,500,000 in service and the excess is $410,000, so the ceiling drops to $2,150,000 for the year.
- Elect the amount you want to expense. The election is per asset and can be partial, which gives you precise control over how much taxable income the deduction absorbs.
- Cap the deduction at active trade or business income. Any amount above that income carries forward to future years without expiring.
Step five is the one most owners overlook. Section 179 is a dial rather than a switch, and expensing exactly enough to reach a target taxable income, while leaving the remaining basis for bonus depreciation or standard depreciation, is frequently a better outcome than maximizing the first-year deduction.
Can Section 179 Create a Loss?
Section 179 cannot create a loss, because the deduction is limited to your aggregate active trade or business income for the year. A business with $90,000 of income and $150,000 of qualifying equipment can elect Section 179 treatment on the full $150,000, but only $90,000 becomes deductible in the current year.
Active trade or business income is broader than the profit of the single business making the purchase. It includes W-2 wages earned by the taxpayer, income from other active businesses, and for a married couple filing jointly, the spouse's active income as well. That aggregation frequently rescues a deduction that looked unusable when viewed against one entity's profit alone.
What Is Section 179 Carryover?
Section 179 carryover is the portion of an elected deduction that exceeded your business income and rolls forward to future tax years. The carryforward has no expiration and no annual limit on how long it persists.
Carryover amounts stack behind current-year elections. In a later year, the carryover competes with new equipment purchases against the same income limitation, so a business that carries forward $60,000 and then buys another $200,000 of equipment has to allocate limited income across both. Tracking the carryover across years is one of the routine functions of accurate financial statements and depreciation schedules.
Is It Better to Take Bonus Depreciation or Section 179?
Neither is universally better, because Section 179 and bonus depreciation stack rather than compete, and most businesses use both in the same year. Section 179 is applied first, bonus depreciation applies to whatever basis remains, and standard depreciation covers anything still left.
The two differ in four ways that determine which one carries more weight in a given year. Section 179 has a dollar cap and a phase-out; bonus depreciation has neither. Section 179 cannot create a loss; bonus depreciation can. Section 179 is elected asset by asset with partial amounts allowed; bonus depreciation applies to an entire asset class unless you elect out of that class. Section 179 covers certain real property improvements; bonus depreciation is limited to property with a recovery period of 20 years or less.
Those differences point toward a practical rule. Businesses with strong income and a need for surgical control over taxable income lean on Section 179, while businesses in a loss year or with very large purchases lean on bonus depreciation, and companies with both circumstances use each where it fits.
What Is Eligible for 100% Depreciation?
Property with a recovery period of 20 years or less is eligible for 100% bonus depreciation, including equipment, computers, vehicles, furniture, and qualified improvement property. The One Big Beautiful Bill Act made the 100% rate permanent for property acquired and placed in service after January 19, 2025.
One acquisition-date detail catches businesses with long lead times. Revenue Procedure 2026-15 confirms that property acquired before January 20, 2025 and placed in service during 2026 receives only 20% bonus depreciation under the previous phase-down schedule, not 100%. Equipment ordered in 2024 that finally arrives and starts working this year falls into that category, and the difference on a large order is substantial.
When Not to Use the Section 179 Deduction?
You should not use the Section 179 deduction in a low-income year, when you expect materially higher tax rates in future years, when your state decouples from the federal limits, or when the asset's business use is likely to fall below 50% during the recovery period. Each situation converts a deduction that looks valuable into one that costs more than it delivers.
- Low-income or startup years. A deduction taken against income in the 10% or 12% bracket is worth far less than the same deduction taken against income in the 32% or 35% bracket two years later.
- Anticipated bracket increases. A business expecting substantially higher profit next year often does better preserving depreciation for the higher-rate year.
- State decoupling. Several states cap Section 179 far below the federal amount, which creates a permanent difference between the federal and state returns and additional recordkeeping in every subsequent year.
- Uncertain business use. Any asset that might shift toward personal use, especially vehicles, carries recapture exposure that can exceed the original benefit.
- Assets likely to be sold early. Disposing of expensed property before the end of its recovery period produces ordinary income rather than the capital treatment an owner might expect.
- Loan covenant and financial statement effects. Aggressive first-year expensing depresses book profit and can strain debt covenants or complicate a lending relationship.
The last two items are where the tax answer and the business answer diverge most often. A deduction that lowers this year's tax bill while breaching a covenant or weakening a balance sheet ahead of a financing round is a poor trade, and modeling that tension is exactly the kind of question a fractional CFO engagement resolves before the purchase rather than after.
Capital purchases also compete with each other for the same limited income. Sequencing equipment across two or three years frequently produces a better total outcome than concentrating everything into one, which is a recurring theme in business profitability work.
What Is the Downside of Section 179?
The downside of Section 179 is that it borrows deductions from future years, exposes the business to recapture if usage changes, and can waste deduction value when claimed against low-bracket income. The provision accelerates timing without increasing the total amount you eventually deduct.
Recapture is the sharpest edge. Business use dropping to 50% or less at any point during the recovery period reverses the excess deduction as ordinary income, and that income arrives in a year the owner did not plan for it. Deliberate year-round planning weighs that exposure against the first-year benefit rather than treating the deduction as free.
What Are Common Section 179 Mistakes?
The most common Section 179 mistakes are confusing the purchase date with the placed-in-service date, keeping inadequate business use records, exceeding the taxable income limitation, and failing to make the election on the return. Each one is preventable with documentation created at the time of purchase rather than at filing.
The placed-in-service error costs the most. Equipment ordered and paid for on December 20 but delivered and installed on January 8 belongs to the following tax year, and no amount of payment timing changes that. The asset has to be ready and available for its intended use before the year closes.
Mileage and usage logs fail more often than any other category of support. Business use percentage drives the entire vehicle deduction, and a reconstructed log built months later carries little weight if the return is examined. Contemporaneous records showing date, destination, purpose, and mileage remain the standard.
Businesses that receive correspondence about a depreciation deduction should read the response deadline first, since the various IRS notices touching business returns each carry their own timeline and the window closes quickly.
What Is Section 179 Recapture?
Section 179 recapture is the reversal of a previously claimed deduction when business use of the property drops to 50% or less before the end of its recovery period. The recaptured amount equals the Section 179 deduction claimed minus the depreciation that would have been allowed under standard rules through that year.
Recaptured amounts are reported as ordinary income on Form 4797 in the year the usage test fails. Selling or otherwise disposing of expensed property before the recovery period ends produces a similar result, with gain up to the amount of depreciation and Section 179 previously claimed treated as ordinary income rather than capital gain.
How Do You Claim the Section 179 Deduction?
You claim the Section 179 deduction by completing Part I of Form 4562, Depreciation and Amortization, and attaching it to your business tax return for the year the property was placed in service. The election has to be made on a timely filed return, including extensions.
Documentation supports the election rather than accompanying it. Retain the purchase invoice, the date placed in service, evidence of business use, and financing documents where applicable, since none of that gets filed but all of it becomes the record if the deduction is questioned later.
What Form Is Used for Section 179?
Form 4562 is used for Section 179, with the election reported in Part I and listed property such as vehicles detailed in Part V. The completed form attaches to Schedule C for sole proprietors, Form 1065 for partnerships, Form 1120-S for S corporations, or Form 1120 for C corporations.
Pass-through entities file at two levels. The partnership or S corporation reports the Section 179 amount on its own Form 4562 and passes it through on the Schedule K-1, and each owner then applies their individual dollar limit and income limitation on their own return.
Is Section 179 a Federal or State Deduction?
Section 179 is a federal deduction, and states vary widely in whether and how much of it they allow. Some states conform fully to the federal limits, others cap the deduction at a far lower amount, and a few disallow it entirely, requiring an addback and separate state depreciation schedules.
Florida businesses avoid this problem at the individual level, since the state imposes no personal income tax and pass-through owners face no state addback on their own returns. Owners operating across multiple states rarely have that luxury, and a deduction that produces clean federal savings can generate years of state-level tracking in a decoupled jurisdiction.
When Does Property Have to Be Placed in Service?
Property has to be placed in service by December 31 of the tax year for which you claim the Section 179 deduction. Placed in service means ready and available for its intended use, which is a functional test rather than a payment test or a delivery test.
Equipment sitting in a crate on the loading dock has not been placed in service. Equipment installed, connected, tested, and available to operate has been, even if no work has yet run through it. That distinction decides which tax year the entire deduction belongs to, and it is the single most common point of failure in year-end purchases.
Year-end timing pressure is real for the Miami businesses we work with, and the better decisions get made in October rather than the last week of December. Building capital purchases into a documented plan removes the scramble, which is one reason equipment sequencing sits inside capital planning rather than in a year-end conversation.
Does Financed Equipment Qualify for Section 179?
Financed equipment qualifies for Section 179 in full, based on the total purchase price rather than on payments made during the year. A business that finances a $180,000 machine with $9,000 down and places it in service in December can deduct the entire $180,000 for that year, subject to the usual limits.
That mismatch between deduction and cash outlay is the provision's strongest cash flow feature. Coordinating the financing structure, the placed-in-service date, and the income limitation across the same tax year is the practical work behind an effective tax strategy for any capital-intensive business.
Frequently Asked Questions
Is Section 179 Worth It?
Section 179 is worth it for a profitable business that needs the cash flow now and expects stable or declining tax rates in future years. It is worth considerably less for a business in a low-income year, since the deduction offsets income taxed at a low rate and forfeits the same deduction against higher-rate income later. The answer depends on your current bracket, your projected bracket, and your state's conformity rules.
Can Trusts Take Section 179?
Trusts and estates generally cannot take the Section 179 deduction. The Internal Revenue Code excludes estates and trusts from the provision, and a trust that receives a Section 179 allocation on a Schedule K-1 from a partnership or S corporation cannot use it. Grantor trusts are treated differently, since the grantor reports the activity on their own return.
Can You Use Section 179 Every Year?
You can use Section 179 every year, with the dollar limit resetting annually. A business placing qualifying property in service in consecutive years claims a fresh $2,560,000 ceiling each year for 2026, subject to that year's phase-out threshold and income limitation. There is no lifetime cap and no limit on how many years you may elect it.
Does Section 179 Reduce Self-Employment Tax?
Section 179 reduces self-employment tax for sole proprietors and partners, because it lowers net business profit on Schedule C or the distributive share flowing to Schedule SE. That makes the deduction more valuable to a sole proprietor than to an S corporation shareholder, since the sole proprietor saves both income tax and the 15.3% self-employment tax on the same dollar of deduction.
What Happens to Section 179 Property When You Sell It?
Selling Section 179 property produces ordinary income to the extent of the deduction and depreciation previously claimed, rather than capital gain. Expensing an asset drives its adjusted basis to zero, so the full sale price generally becomes taxable, with the depreciation recapture portion taxed at ordinary rates on Form 4797.
Can a Business With a Loss Still Buy Equipment and Get a Deduction?
A business with a loss can still buy equipment and claim a deduction through bonus depreciation, which has no taxable income limitation. Section 179 would be capped at zero in that year, though the elected amount carries forward indefinitely. Bonus depreciation can increase a net operating loss, which may then be carried forward to offset future income.
The Bottom Line
Section 179 rewards businesses that decide early and document carefully. The 2026 limit of $2,560,000, the phase-out beginning at $4,090,000, the $32,000 heavy SUV cap, and the December 31 placed-in-service deadline are all published well in advance, which means the size of the deduction is set by choices you control: what you buy, when it starts working, how thoroughly you track business use, and whether the deduction lands in a year where it is worth taking at all.
The harder question is rarely how much you can claim. It is whether claiming the maximum this year serves the business better than preserving depreciation for a higher-rate year, and that answer changes with your income, your state, your financing, and your growth plans. The advisors at NR CPAs & Business Advisors hold CPA and Enrolled Agent credentials and work through these decisions with business owners nationwide. If you are planning an equipment purchase, weighing Section 179 against bonus depreciation, or facing a recapture question, we are glad to talk it through in a consultation.


Tax and Financial Insights
by NR CPAs & Business Advisors