IRS Currently Not Collectible (CNC) Status: How It Works

Currently Not Collectible (CNC) is an IRS designation that temporarily pauses all collection activity on your account when you cannot afford to pay anything toward your tax debt without failing to cover basic living expenses. According to the IRS, CNC status means the agency has determined that requiring any payment would cause you financial hardship. While your account is in CNC, the IRS will not levy your wages, seize your bank accounts, or garnish your income.
CNC status does not eliminate your tax debt. According to the IRS, you still owe the full balance, and penalties and interest continue to accrue while your account is in this status. The IRS may also file a Notice of Federal Tax Lien to protect the government's interest in your property, and it will apply any future federal tax refunds to your outstanding balance. CNC is a temporary measure, not a permanent resolution, but it can provide critical breathing room for taxpayers in severe financial hardship.
Who Qualifies For CNC Status
You may qualify for CNC status if your monthly income, after allowable living expenses, leaves you unable to make even a small payment toward your tax debt. According to the IRS, the agency uses national and local cost-of-living standards to evaluate your expenses, including housing, utilities, food, transportation, health insurance, and out-of-pocket medical costs. If your allowable expenses equal or exceed your income, and you have no significant assets the IRS could use to satisfy the debt, CNC status is typically approved.
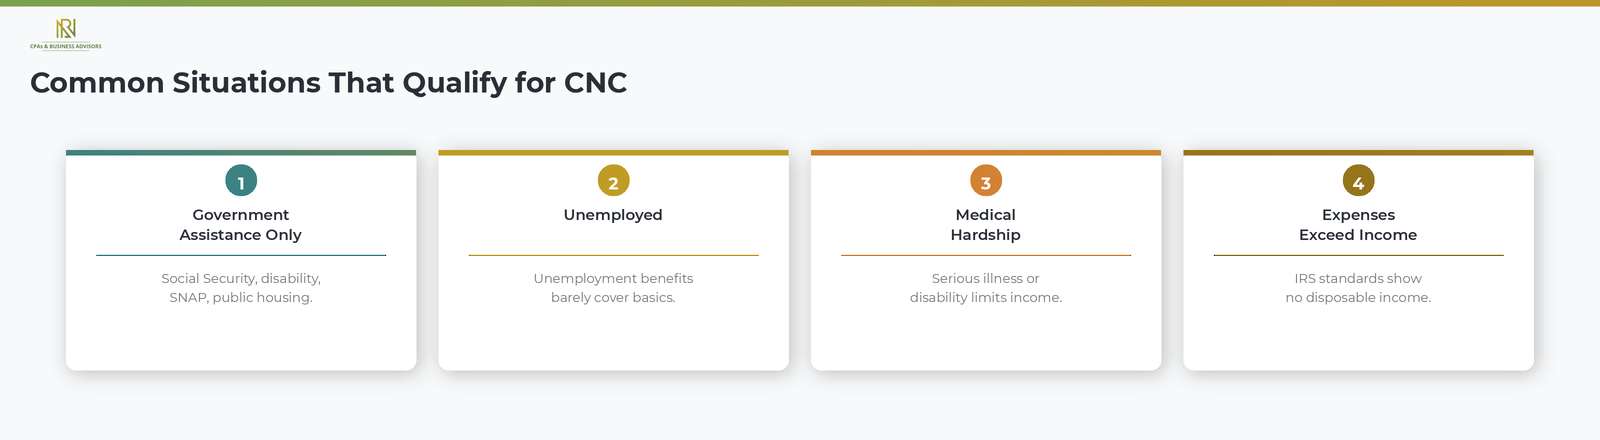
Common situations that support CNC eligibility include the following.
- Your only income is from government assistance. Social Security, disability benefits, unemployment compensation, or public assistance programs.
- You are unemployed with no other income. Especially when unemployment benefits barely cover basic expenses.
- You have a serious medical condition or disability. Particularly conditions that permanently limit your earning capacity.
- Your expenses exceed your income. Even after the IRS applies its own expense standards, there is no disposable income available for tax payments.
How To Request Currently Not Collectible Status
To request CNC status, call the IRS at 800-829-1040 or the phone number on your most recent notice and explain that you cannot afford to make any payments toward your tax debt. According to the IRS, the agent will ask you to provide financial information to verify your hardship. In most cases, you will need to complete Form 433-F, Collection Information Statement, which is a two-page form that documents your income, monthly expenses, debts, and assets.
For more complex financial situations, the IRS may require Form 433-A (for wage earners and self-employed individuals) or Form 433-B (for businesses). According to the IRS, you should be prepared to provide supporting documentation including pay stubs, bank statements, utility bills, rent or mortgage statements, and medical records if applicable. The IRS compares your reported expenses against its allowable expense standards to determine whether any payment is feasible.
When speaking with the IRS, be clear that you cannot afford any monthly payment, not just that you cannot pay the full amount. According to the IRS, if you can afford a small monthly payment, the agency will typically direct you toward an installment agreement or partial payment plan instead of CNC status.

What Happens While Your Account Is In CNC
While your account is in CNC status, the IRS suspends most active collection efforts but retains the right to take certain actions that protect the government's interest. According to the IRS, the following applies during CNC.
- No levies or garnishments. The IRS will not levy your wages, bank accounts, or other property.
- Tax refunds are still taken. The IRS will intercept and apply any federal tax refund you receive to the outstanding balance.
- A federal tax lien may be filed. According to the IRS, if you owe more than $10,000, the agency will generally file a Notice of Federal Tax Lien, which is a public record that can affect your credit and your ability to sell or refinance property.
- Penalties and interest continue. The balance grows while you are in CNC because the IRS does not stop charging penalties or interest during this period.
- Periodic reviews. The IRS may review your financial situation later and resume collection if your income improves.

When The IRS Can Remove CNC Status
The IRS can remove your account from CNC status and resume collection activity if your financial situation improves. According to the IRS, the agency assigns a closing code to each CNC account that corresponds to an income threshold. If your reported income exceeds that threshold, as indicated by W-2s, 1099s, or tax returns filed in subsequent years, the IRS may contact you to reassess your ability to pay.
If the IRS determines you can now afford payments, it will typically offer you the option to set up an installment agreement or pursue another resolution. If your income remains below the threshold indefinitely, your CNC status continues until the 10-year Collection Statute Expiration Date (CSED) expires, at which point the remaining debt is written off permanently.
How CNC Interacts With The 10 Year Collection Statute
One of the most important features of CNC status is that it does not pause or extend the IRS's 10-year collection clock. According to the IRS, the CSED continues to run while your account is in CNC. This means that if your income does not improve before the statute expires, the IRS loses its legal authority to collect the debt, and the balance is permanently written off.
This is a key distinction from other resolution options. Requesting an Offer in Compromise or an installment agreement suspends the CSED while the IRS evaluates your application, effectively giving the agency more time to collect. CNC status does not. For taxpayers with older tax debts and limited income prospects, CNC can be strategically advantageous because the clock keeps running in your favor.
However, CNC is not always the best long-term strategy. If your income is likely to improve, the IRS will remove you from CNC and resume collection, potentially with a larger balance due to accumulated penalties and interest. Taxpayers weighing CNC against other options like payment plans, Offers in Compromise, or penalty relief can compare all available paths in the IRS tax debt resolution overview.

Frequently Asked Questions About CNC Status
Does CNC Status Forgive My Tax Debt?
No, CNC status does not forgive or cancel your tax debt. According to the IRS, you still owe the full balance, and penalties and interest continue to accrue. The debt is only eliminated if the 10-year CSED expires while your account remains in CNC.
Will The IRS Take My Tax Refund While I Am In CNC?
Yes, the IRS will intercept and apply your federal tax refund to the outstanding balance even while your account is in CNC status. According to the IRS, refund offsets are one of the collection actions the agency continues during CNC.
How Long Can I Stay In CNC Status?
There is no fixed time limit on CNC status. According to the IRS, your account remains in CNC as long as your financial situation does not improve beyond the threshold the agency sets. The IRS may review your finances periodically, but CNC can last for years if your income remains at hardship levels.