



Term Life Insurance | Florida
What Happens If I Outlive My Term Life Policy?
Learn how standard term coverage ends, what happens to your premiums, and which options to review before your term runs out. Request a coverage review with NR CPAs & Business Advisors in Miami.
By Nischay Rawal · Published October 18, 2026
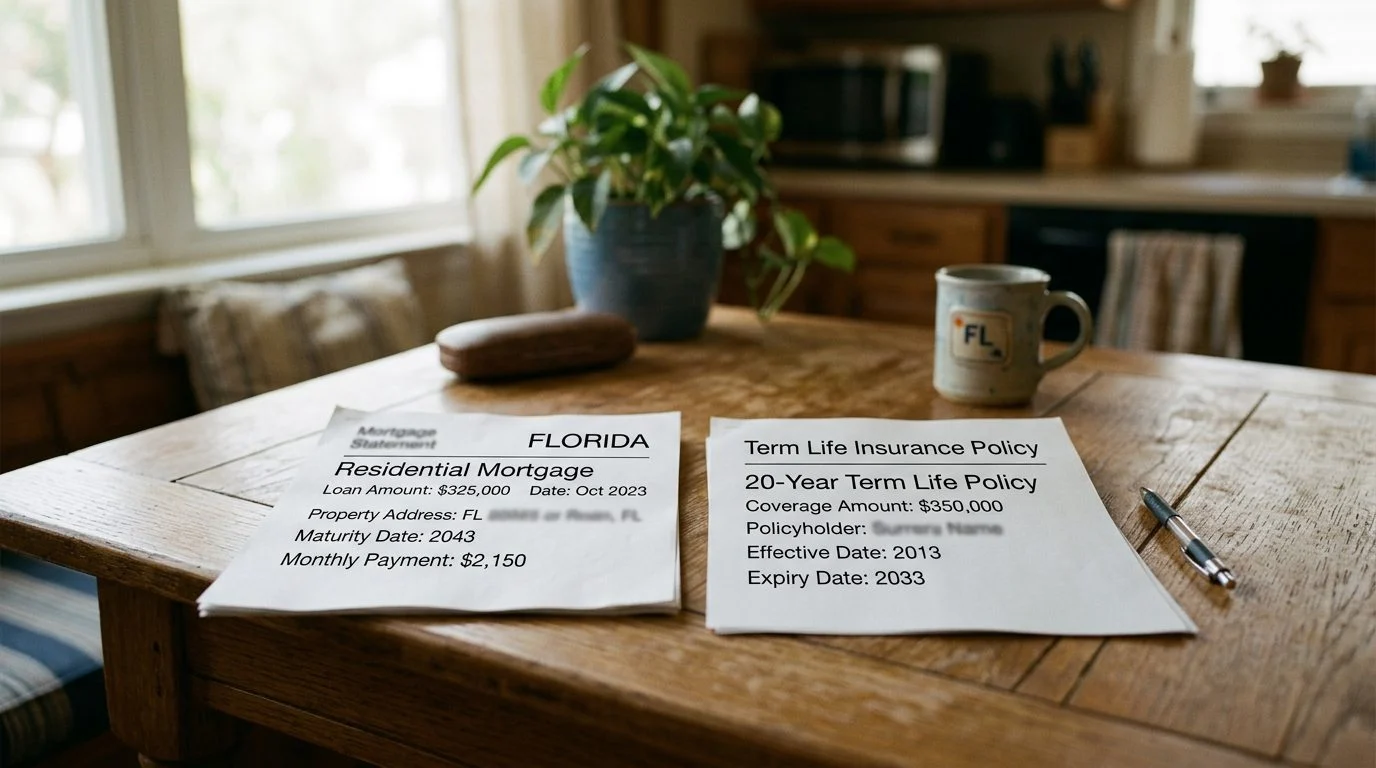
What happens if I outlive my term life policy? In most cases, the coverage simply ends. A standard term policy pays a death benefit only if the insured dies during the term. Once the term ends, premiums stop and no death benefit is paid. What comes next depends on your policy form, which may allow renewal, conversion or a refund feature.
This page explains what ends, what can continue, and what questions to ask about your own policy. It is written for Florida families, business owners and NRI households. NR CPAs & Business Advisors is a Miami CPA firm. Insurance is offered by a licensed insurance agent, separately from the accounting practice.
What happens to the coverage when the term ends
When the term ends, the death benefit ends too. A term policy has a level premium period. During that period, the premium and the face amount usually stay the same. Once the period ends, the policy’s own terms decide what happens next.
Premiums stop when the policy ends, unless you renew or convert the policy. The expiration date appears in your policy form. Find it first. Many people assume the policy simply continues, but that is not always the case.
Missing a premium is a different issue. Florida law requires a life insurance policy to provide a grace period for paying a premium after the first one, and the policy states the length of that period. The policy stays in force during that grace period. The Florida grace period statute sets this rule. Do not rely on the grace period to keep coverage going past the term.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Do I get my premiums back if I outlive a term policy?
Usually not. Standard term life insurance has no cash value. It does not refund premiums at the end of the term. You pay for the protection during the term, and that protection ends when the term does.
Some term policies have a return-of-premium feature. These policies refund some or all premiums if the insured outlives the term. The refund depends on conditions written into the policy and any rider. Those conditions can include exclusions and other requirements.
Do not assume the refund applies to your policy. Read the policy form, including the conditions for the refund. The feature is also built into the premium. You pay for it through the cost of the policy, so compare it with the standard term option before you buy.
Your options when the level-premium period ends
When the level period ends, you usually have four paths: renew, convert, buy a new policy or let the coverage end.
Renewal. Many term policies allow renewal for additional terms. The renewal premium is often higher and may rise with age. Your policy form states the renewal rules and any age-based changes.
Conversion. Many term policies include a conversion option. It lets you change to a permanent policy, such as whole life insurance. The policy sets the window for converting. Check whether conversion needs new health questions, because that varies by policy.
A new policy. You can apply for a new policy. A new application involves underwriting and health questions. The cost may be higher, or coverage may be unavailable, depending on your health and age at that time.
Letting it end. If you do nothing, coverage ends and premiums stop. No further death benefit is payable.
Be careful when you compare options. Using the cash or loan values of an existing policy to buy another policy from the same insurer can be a problem. Florida law calls that practice churning and treats it as an unfair or deceptive act when there is no objectively reasonable basis for believing it helps the policyholder. The Florida unfair trade practices statute sets out this rule. Ask for a written comparison before you decide.
Converting to whole life insurance: what changes
Converting to whole life insurance changes your coverage from temporary to permanent. Whole life insurance is permanent coverage. Its premiums are typically higher than term premiums at the same age, so review the cost before you convert.
A whole life illustration should show guaranteed and non-guaranteed values separately. Ask which numbers the insurer guarantees and which depend on future conditions. Dividends, where a policy pays them, are not guaranteed.
Cash value is the amount the policy states it holds. It is not an investment, and it is not a promise of any return. Read the policy form to learn how cash value works, how it changes over time, and how loans or withdrawals affect the death benefit. Ask your agent to explain each number in plain words.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Do I still need life insurance once my term policy ends?
It depends on the facts. Your debts, your income, the ages of your dependents and your business obligations all matter. Estate planning goals matter too.
Many families still need coverage when a term policy ends. A spouse may rely on your income. Children may still be young. A mortgage or other debt may remain. A business may depend on your work or on a partner’s agreement.
Business owners face a few specific points. Key person and buy-sell coverage have their own rules. The general rule in Internal Revenue Code section 264 states that no deduction shall be allowed for premiums paid on a life insurance policy, or on an endowment or annuity contract, when the taxpayer is directly or indirectly a beneficiary under that policy or contract. A business that keeps paying those premiums should plan for that cost.
Estate planning adds another layer. Section 2042 of the Internal Revenue Code provides that the value of the gross estate includes the amount receivable by all other beneficiaries as insurance under policies on the life of the decedent with respect to which the decedent possessed at his death any of the incidents of ownership. Ownership rules matter, so review who owns the policy before the term ends.
Planning before the term ends
Start your review well before the expiration date. Check four items: the expiration date, the renewal premium, the conversion deadline and any return-of-premium terms. Each one controls what you can do next.
Timing matters. Conversion windows and underwriting for a new policy can depend on dates and on health changes. A health change that happens after the term is near can affect your options. Both the policy form and the carrier’s rules set those limits.
The NAIC Life Insurance Buyer’s Guide covers term versus permanent coverage and questions to ask before buying. The Florida Department of Financial Services life insurance guide explains policy types, cash value and replacement.
New coverage is subject to health questions and underwriting. No new policy is assured. Plan for that possibility now, while your current policy still runs.
Talk through your term policy with a coverage review
Many readers reach this question during a hard time. A parent’s policy may be close to ending. A spouse may be left to decide alone. A business partner may need coverage that is about to change.
Nischay Rawal is a licensed insurance agent. He offers insurance separately from the accounting practice of NR CPAs & Business Advisors. Insurance is offered by the licensed agent, and tax and accounting work is handled by the firm.
Frequently asked questions
What happens if I outlive my term life policy?
Under a standard term policy, the coverage ends and premiums stop. No death benefit is paid after the term.
Do I get my money back if I outlive my term policy?
Usually not. Standard term has no cash value. Some policies have a return-of-premium feature with conditions in the policy form.
Can I convert term life insurance to whole life?
Many term policies include a conversion option. The policy sets the window and any health requirements.
Do I still need life insurance after my term ends?
That turns on your debts, income, dependents and business obligations.
If your term policy is nearing its end, call NR CPAs & Business Advisors to schedule a coverage review of your policy, your family’s needs and any business agreements that depend on it.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
What to know when your term period ends
Coverage ends
Under a standard term life policy, the coverage ends at the close of the term. No death benefit is paid after that.
Premiums stop
Because standard term has no cash value, premium payments stop when the coverage ends.
Read your policy form
Some term policies include a return-of-premium feature or a conversion option. The conditions are set out in your policy form, so read them carefully.
Plan ahead
Reviewing your options well before the end of the term gives you more choices, including whether to apply for new coverage.
Check the terms before you assume
Return-of-premium features, renewal terms and conversion rights vary from policy to policy. Confirm the details in your own policy form before you decide what to do next.
Options to review as your term nears its end
Reassess your need
Consider whether your family, mortgage, business or other obligations still need life insurance protection.
Ask about conversion
If your policy allows conversion, you may be able to move to a permanent form of coverage, such as whole life insurance, without new health questions. Ask how your policy handles this.
Plan for estate and business needs
Life insurance can play a role in estate planning and in business continuity, including key person and buy-sell arrangements.
Compare your alternatives
Review the cost and features of any new coverage against the policy you already hold, with the full terms in front of you.
Who you are speaking with
Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors.


