



Florida Life Insurance | Miami
Understand Term Insurance Before You Choose Coverage
A plain-language guide from NR CPAs & Business Advisors to how term life insurance works, what it covers, and how it fits into a Florida family's or business owner's plan to protect loved ones.
By Nischay Rawal · Published October 31, 2026
If you’re asking what is term insurance, here’s the short answer. Term life insurance pays a death benefit to the people you name, but only if the insured dies during a set period called the term. This guide explains how that period works, what affects cost, and how term differs from whole life. It’s general education for Florida readers, not an offer of any policy.
What term life insurance means in plain words
Term life insurance pays a death benefit to the beneficiaries you name if the insured dies during the term. The death benefit is the face amount written into the policy.
Term is a different plan type from whole life insurance. A policy is a whole life policy only if the insurer’s policy form says so. Read the form before you assume.
This page is general information, not an offer of a policy. Any term policy is offered by a licensed insurance agent and issued by a named insurer. Florida law requires an agent, when soliciting or selling insurance, to say clearly to prospective insureds that they act as an insurance agent with regard to insurance products and identified insurers (Fla. Stat. § 626.9531). Nischay Rawal, a licensed insurance agent, is the responsible agent for this page. Insurance is offered separately from our accounting practice.
If a family member's question about term coverage has you unsure what comes next, our team can review those details with you in a coverage review. Call us today. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
How the coverage period works
Term coverage lasts only for the term. If the insured dies after the term ends, no death benefit is paid unless the policy has its own renewal or conversion right. FINRA’s insurance investor page describes term coverage as lasting only for a limited period.
Many term policies keep the same premium for a chosen level period. After that, premiums may change, as the policy form states. Renewability, cancellability, and any age-based change depend on that form.
A common mistake is assuming coverage continues on its own. Find the end date in the policy and read the renewal terms before you rely on it.
How many years a term policy can last
The length of the term is chosen when you apply and written into the policy. Ask the insurer which term lengths it offers, because options differ by policy.
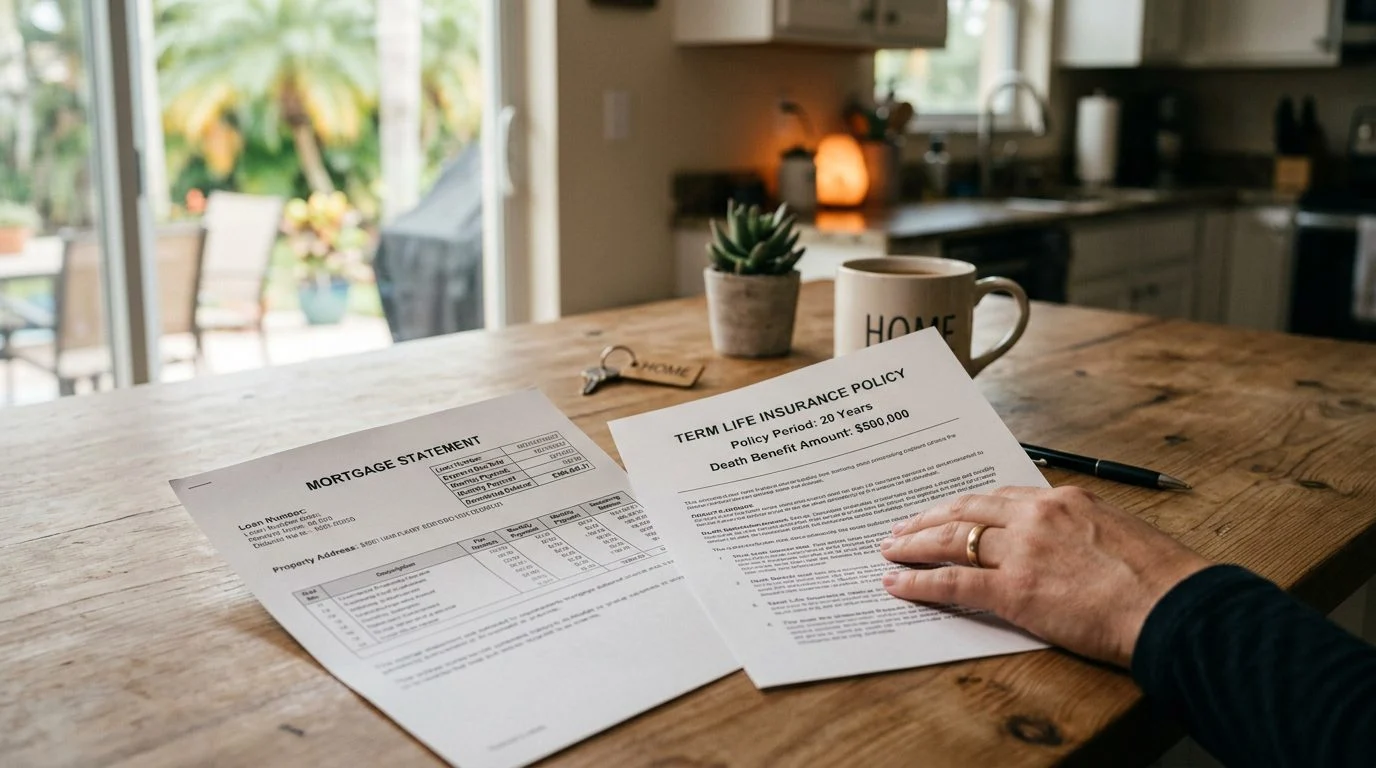
Families often match the term to a planning goal, such as the years until a mortgage is paid or children finish school. That is a planning idea, not a recommendation. A shorter term may end before the need does, so compare the end date to the years you need coverage.
The term length, the face amount, and the insured’s age and health at application all shape the terms offered. If the need is still there when the term ends, ask about renewal or conversion options in the policy form before the term runs out. The insurer’s rules decide the final result.
How term life insurance is issued and what affects cost
Term life insurance can be fully underwritten. That means health questions are required, and issue may depend on insurability. The insurer decides whether to issue the policy and on what terms.
Factors that commonly affect cost include age, health history, tobacco use, the length of the term, and the face amount. The insurer’s underwriting rules and the policy form set the actual terms. This page does not quote premiums, and the premium depends on the applicant and the policy issued.
Florida law also shapes policies after issue. Every insurance policy must be incontestable after it has been in force during the insured’s lifetime for 2 years from its date of issue, except for nonpayment of premiums and, at the insurer’s option, as to provisions relative to benefits in event of disability and as to provisions which grant additional insurance specifically against death by accident or accidental means (Fla. Stat. § 627.455). If the age or sex of the insured, or of any other individual considered in determining the premium or benefit, was misstated, the benefit is adjusted to what the premium would have bought at the correct age or sex (Fla. Stat. § 627.456).
How term differs from whole life insurance
Term covers you for a set period. Whole life insurance is designed to last for the insured’s lifetime and includes a cash value feature, according to FINRA. Term generally does not build cash value.
Whole life cash values are not all guaranteed. The policy illustration and policy form show which values are guaranteed and which are not. Review both sets of numbers side by side.
If you already own a policy, don’t change it based on a general page. Replacing a policy can involve surrender charges, changes in cash value, and new underwriting. Review the existing policy’s documents first, and ask whether replacement rules apply.
Questions to bring to a coverage review
Before you decide, write these questions down and ask for answers in writing:
- How long is the term, and when does it end?
- How long does the level premium last, and what happens after?
- Can the policy be renewed or converted, and on what terms?
- What exclusions and limitations are in the policy form?
- Which insurer issues the policy, and what is its form number?
- Are there age-based premium changes?
The NAIC Life Insurance Buyer’s Guide covers term versus permanent coverage and questions to ask before buying.
Frequently asked questions
What is term insurance?
Term insurance is life insurance that pays a death benefit only if the insured dies during a set term.
Does term life insurance build cash value?
Term life insurance generally does not build cash value. Whole life insurance is designed to include a cash value feature.
How long does term life insurance last?
It lasts for the term written into the policy. After that, coverage ends unless the policy’s renewal or conversion terms apply.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Next step: a coverage review with our team
You may be reading this because a family member asked about coverage, a policy’s term is close to ending, or a change in health made the question feel urgent. Each situation raises different questions about the term, the renewal rules, and the insurer’s terms.
Our team can work through those details with you in a coverage review. Nischay Rawal, a licensed insurance agent, offers insurance separately from our accounting practice. When you’re ready, call us today or use our contact page.
What to Look for in a Term Life Policy
Read the Policy Form
Review the insurer's name, the policy form number, the death benefit, and the premium before you decide. The policy document controls the terms.
Know the Term Length
Term policies cover a set number of years. Ask how long the coverage lasts and what happens when that period ends.
Understand the Exclusions
Every policy has limitations and exclusions. Learn what is not covered so there are no surprises when your family files a claim.
Match Coverage to Your Family
Consider income, debts, children, and obligations such as a mortgage or a business loan when you decide how much coverage fits.
Term Insurance Is Not a Savings Plan
Term life insurance generally does not build cash value. If you want a policy with a cash value feature, ask about whole life insurance, and compare the guaranteed and non-guaranteed values separately. Do not let any sales conversation rush you into replacing an existing policy.
Where Term Insurance Fits in a Plan
Family Protection
Term coverage can replace income for a spouse or children during the years they depend on you most.
Key Person and Buy-Sell Planning
Business owners often use term coverage to fund key person protection or a buy-sell agreement tied to the company's ownership.
Estate Planning
Life insurance can help provide liquidity for estate obligations. Coordinate it with your overall estate plan and tax picture.
NRI Coverage
Non-resident Indian families and business owners often need coverage that fits cross-border finances, family obligations, and U.S. tax considerations.


