



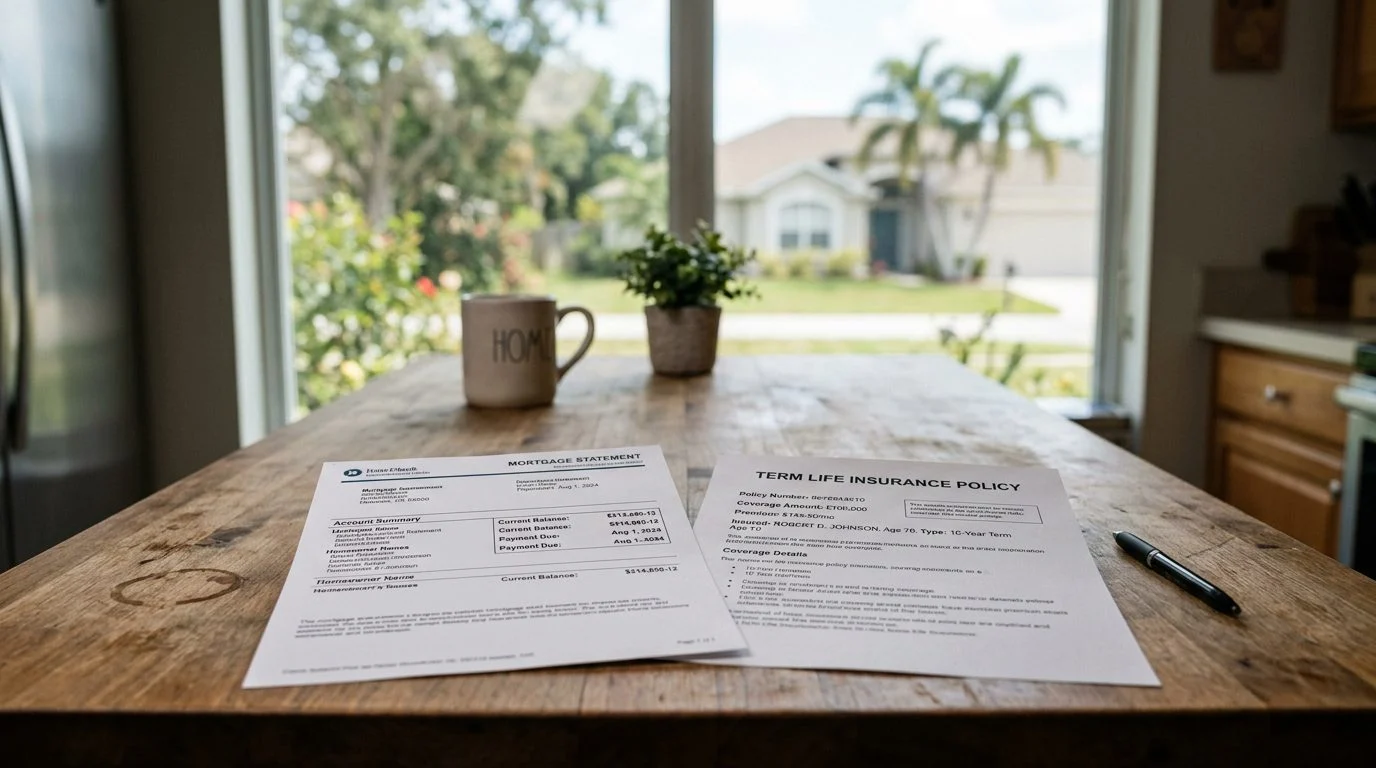
Life Insurance Cost | Florida
Planning Coverage at 70? Start With a Clear Picture of the Cost
Cost is only one part of the decision. See how age, policy type and your household's cash flow shape the choice.
By Nischay Rawal · Published November 11, 2026
If you’re trying to work out how much a $100,000 life insurance policy costs for a 70-year-old male, you may be doing it for a father, an uncle or a spouse. Families and business owners look into life insurance at many different points in life, and a coverage review can help clarify which options fit their situation.
There’s no single monthly figure that fits every man at 70. The cost depends on his age when the policy is issued, his health answers, the policy type, the coverage length and the insurer’s underwriting decision. This page explains how those pieces build the price. It doesn’t quote a premium for anyone.
Why a $100,000 policy at age 70 is hard to price with one number
A $100,000 policy at 70 has no standard price, because each offer is built from facts about one person. Insurers look at age, health history, tobacco use, medications and the type of policy. Whether a policy is offered, and in which rating class, depends on the facts of the applicant.
Numbers from different websites often don’t match. Each one may use a different age, health class or policy type, so they’re hard to compare side by side. For general background, the NAIC Life Insurance Buyer’s Guide covers term versus permanent coverage and questions to ask before buying.
If a parent has just had a diagnosis or a hospital stay, the pressure to decide fast is real. Slow down enough to learn which facts a figure is based on. Think of the monthly number as the last step in a chain. Age, health and product design come first.
If you're weighing a policy for a parent after a recent health change, our team can walk through the cost factors in a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.

How age 70 changes the price of life insurance
Life insurance generally costs more when the person is older at issue. Insurers price a policy around how long they expect coverage to last and how likely a claim is. At 70, the expected time before a claim is shorter than at 50, so the premium is usually higher.
For most applicants, the same $100,000 costs more at 70 than at 50. Each insurer starts from its own age-based rate table. The final offer then follows underwriting, so the table isn’t the whole answer.
Two terms matter here. The face amount is the death benefit, the sum paid to the beneficiary. The premium is what the buyer pays to keep the coverage in force.
Age on the application has to be right. If the age was misstated, Fla. Stat. § 627.456 says the amount payable is what the premium would have bought at the correct age, using the insurer’s rate at issue. A wrong age can shrink the benefit, so check it before signing.
Term life vs. whole life for a $100,000 policy at 70
Whole life generally costs more per month than term for the same face amount, because it’s designed to last for life. Term life covers a set period instead. At 70, term coverage may be offered for shorter periods, and its availability and cost vary by insurer and term length.
Each structure fits different goals. A family might look at term to cover a debt or a set period. Whole life is sometimes considered for final expenses or estate liquidity, meaning cash available to pay estate costs.
Cash value and dividends need careful reading. Guaranteed values are set out in the policy. Non-guaranteed values can change, and dividends are not guaranteed. Florida law requires any reference to dividends to say so.
A policy loan has limits too. Fla. Stat. § 627.458 allows a loan only after the policy has a cash surrender value and no premium is in default. Fla. Stat. § 627.458 reads: “The loan value of the policy shall be at least equal to the cash surrender value at the end of the then-current policy year, except that the insurer may deduct, either from such loan value or from the proceeds of the loan, any existing indebtedness not already deducted in determining such cash surrender value, including any interest then accrued but not due, any unpaid balance of the premium for the current policy year, and interest on the loan to the end of the current policy year.” That rule does not apply to term policies or to term insurance benefits provided by riders or supplemental policy provisions.
For more on how whole life works, read our whole life guide for families.
How health questions and underwriting shape the offer
Underwriting decides whether an insurer offers coverage and in which rating class. A fully underwritten policy requires health questions, and issue may depend on insurability.
Underwriters review medications, chronic conditions, recent hospital stays, tobacco use and family history. Each answer can shift the offer. Incomplete answers can cause problems with the policy later, so answer every question fully and accurately.
Some products take a different path. A guaranteed-issue policy has graded or limited benefits. Read those benefit terms closely before you choose one, and ask how the policy treats health history at issue and at claim.
Florida law says a life policy must become incontestable once it has been in force during the insured’s lifetime for 2 years from its date of issue, except for nonpayment of premiums and, at the insurer’s option, provisions for disability benefits and extra accidental-death coverage (Fla. Stat. § 627.455). That clause still does not stop defenses based on policy exclusions or restrictions (Fla. Stat. § 627.463). A health change can also move a person into a different rating class, so timing and full disclosure matter.
What changes the monthly cost besides age and health
Payment mode, riders and face amount each change the figure you see each month. Compare offers using the same inputs, or the numbers mean little.
Monthly, quarterly and annual payments show different periodic amounts. Riders such as an accelerated death benefit or a waiver of premium add cost, and each rider has its own limits.
Changing the $100,000 face amount changes the premium too. A lower face amount may fit a budget, but it also lowers the death benefit.
Before you buy, confirm three things. Find out whether the policy is renewable, whether it can be cancelled, and whether the premium changes with age. These terms set how the cost can move over time.
How to read an illustration before comparing numbers
An illustration shows how a policy’s values and premiums work over time. It is not a forecast of what the policy will do. The American Academy of Actuaries says illustrations explain policy mechanics, values and premium changes. It also says they aren’t reliable for projecting future performance or comparing policy costs.
Read guaranteed and non-guaranteed values side by side, with equal emphasis. Guaranteed values are fixed in the contract. Non-guaranteed values can change, so an illustration that shows them must make that clear.
Florida law says cost indexes are useful only for comparing two or more similar policies (Fla. Stat. § 626.99). The Florida DFS life insurance guide describes the period after delivery in which a policy may be returned. Check that period in your own policy before you pay the first premium.
The premium pays the insurer for the coverage. The premium pays the insurer for the coverage. It isn’t an investment, unless the policy is variable life insurance, where cash values vary with investments held in a separate account.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Key takeaways for a family researching this decision
Four factors shape the cost of a $100,000 policy at 70: age at issue, health and underwriting, policy structure, and riders and payment mode.
- Age at issue: the older the applicant, the higher the premium for the same face amount.
- Health and underwriting: answers decide the rating class and the offer.
- Policy structure: term and whole life price differently and carry different limits.
- Riders and payment mode: each one changes the monthly figure you see.
No single figure applies to every 70-year-old man. The offer follows underwriting, not a table alone.
Frequently asked questions
Is the death benefit taxable?
Death benefits are generally not gross income for federal income tax purposes.
What if a premium is paid late?
Florida law requires at least 30 days to pay a premium after the first, and the policy stays in force during that grace period (Fla. Stat. § 627.453).
Talk with our team about your family’s situation
If you’re weighing a $100,000 policy for a parent after a recent health event, a coverage review can help you sort through these factors for that person. Many families in this spot are trying to cover final expenses or a family obligation while still learning the terms.
Nischay Rawal acts as a licensed insurance agent when insurance is discussed. Insurance is offered separately from the firm’s accounting and tax practice.
To set up a coverage review, reach out to our team.
Why Families and Business Owners Work With Us
A CPA's view of cost
We look at premiums alongside tax and cash flow, so the cost fits the rest of your financial picture.
Built for diverse households
We help Indian-American families and business owners, as well as other households and professionals across the United States.
Coverage for the people who depend on you
Our work covers whole life, term life, key person, buy-sell and estate planning life insurance, plus NRI life insurance.
A coverage review first
Your first step is a coverage review with our team, where we discuss your goals before any policy is considered.
Important Information About Insurance Advice
Life insurance is offered by Nischay Rawal, a licensed insurance agent, separately from our accounting practice. Premiums depend on age, health, policy type and other factors, and every policy has limitations and exclusions. Ask us to explain any term in plain words before you decide.
What Shapes the Cost of a Policy
Your age at issue
Premiums are generally higher at older ages, which is why timing and policy type matter.
Policy type
Whole life and term life are priced differently, and each serves a different purpose.
Health and underwriting
Health questions are part of the process, and the issue of a policy may depend on your insurability.
Your cash flow
We review how a premium fits your budget and tax situation over the long term.


