



Life Insurance | Florida
Thinking About Canceling Your Life Insurance? Talk With Us First.
A coverage review helps you see what your current policy provides for your family and how a change would affect your coverage and cash flow.
By Nischay Rawal · Published November 9, 2026
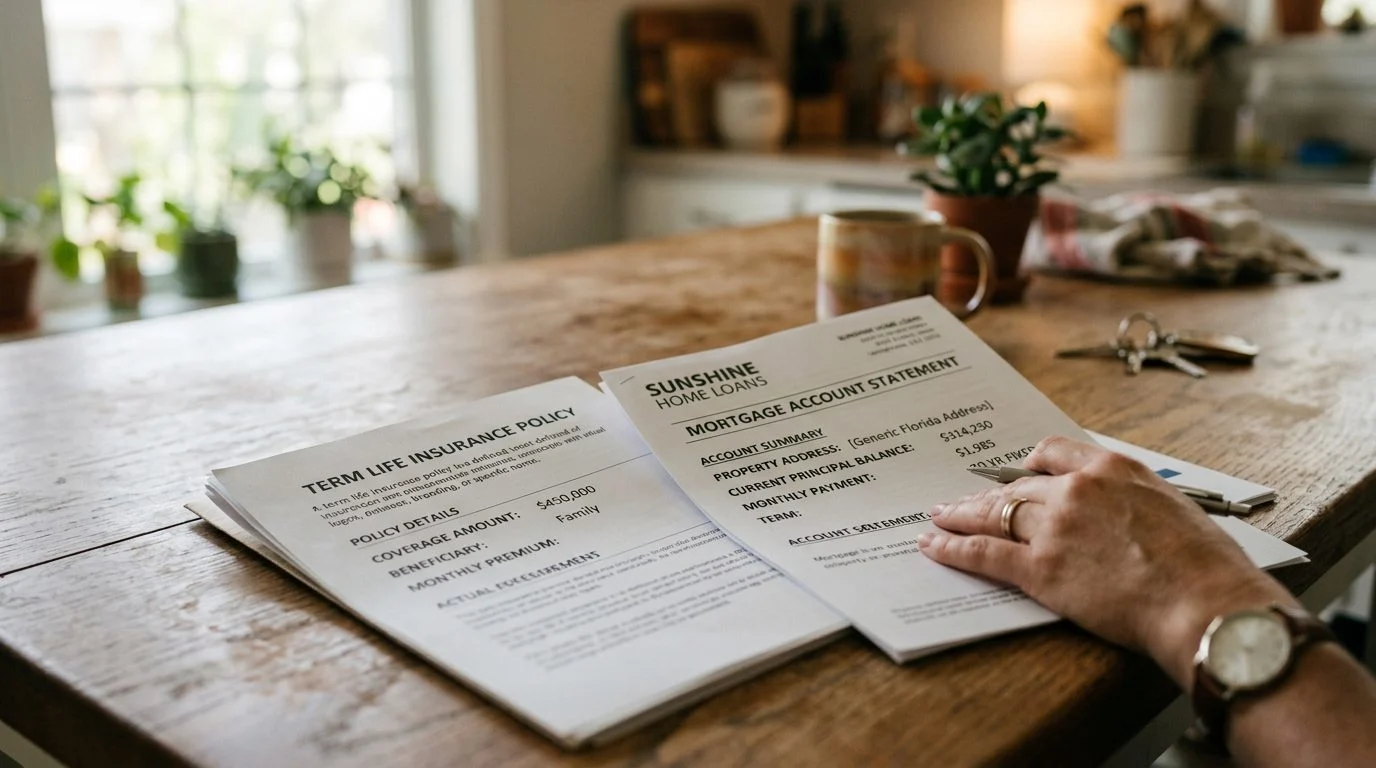
You may be asking how to cancel a life insurance policy because the premiums have become hard to pay, or because your family or business has changed. There is no single cancel button. A policy can end by surrender, by lapse, or by a cut in coverage, and each route changes the death benefit and any cash value in its own way. This page explains each option in plain words, the Florida rules that apply, and the checks to make first.
What cancelling a life insurance policy actually means
A policy ends in a few ways, and the owner’s choice decides which one happens. Surrender means you ask the insurer to end the policy and pay its cash surrender value. A lapse happens when premiums stop and the policy ends for nonpayment. A reduction keeps a smaller policy in force.
Some plain terms help here. The face amount is what the policy pays at death before any loan or unpaid premium is subtracted. The death benefit is what your beneficiary actually receives. Cash value is the savings part that builds inside some policies. The policy owner controls the policy, and the insured is the person whose life it covers. These roles can belong to different people.
Term life insurance usually has no cash value. Cancelling it often means stopping premiums and ending the coverage. Whole life insurance can return money, so the choice is more involved.
If you're weighing whether to cancel a policy for a parent or for your business, you don't have to sort through the options alone. Our team can walk through them with you in a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Check the review period first if the policy is new
If the policy is new, check whether you still have a period to return it. Read the delivery paperwork for any return rights and the dates they run.
Return periods often start on delivery, so the date on the delivery receipt can matter. Write that date down. The Florida Department of Financial Services guide explains how these periods work for life insurance, and it’s a useful read before you act.
Keep the policy, the delivery receipt, the application copy, and every letter from the insurer in one folder. These documents show what was bought and when. Ask the insurer in writing for its current figures before you send any request.
Surrendering a whole life policy for its cash surrender value
Surrender ends the policy and pays you its cash surrender value. That ending is permanent.
The cash surrender value is the accumulated cash value minus any surrender charges. Surrender charges are fees the insurer takes for ending a policy early, and they often shrink over time. So the figure can change a lot from one year to the next.
Illustrations show guaranteed and non-guaranteed values separately. Dividends are not guaranteed. Look at the insurer’s current statement rather than an old projection.
Surrender also ends the death benefit. Your beneficiary receives nothing from that policy later, and you can’t undo the step once the insurer processes it. You make the request on the insurer’s form, and the insurer sets the final payout.
If an agent recommends surrender without using the money to buy another policy, Florida law requires written information first. That information includes the estimated surrender charge and the amount of any forfeited death benefit, under Fla. Stat. § 627.4553.
Letting premiums lapse, reducing coverage, or borrowing against the policy
Stopping premiums doesn’t end the policy on day one. Florida law requires a grace period of not less than 30 days for any premium after the first, and the policy stays in force during that time. The insurer may charge interest of up to 8 percent per year for those days. See Fla. Stat. § 627.453.
Older policyowners get extra notice. For a policy issued in Florida on or after October 1, 1997, covering someone 64 or older that has been in force at least one year, the insurer must mail a notice of impending lapse at least 21 days before the lapse, after the grace period expires. The notice goes to the owner and any named secondary addressee. Premiums payable monthly or more frequently and collected by a licensed agent, paid by credit card, or paid by preauthorized check processing or automatic debit service of a financial institution are exempt. See Fla. Stat. § 627.4555.
A reduced face amount keeps some coverage with no further premiums, but the death benefit drops. Reduced paid-up options work in a similar way.
A policy loan lets you borrow against a whole life policy. Florida law lets the insurer advance the loan once the policy has cash surrender value and no premium is in default. Fla. Stat. § 627.458 reads: “The loan value of the policy shall be at least equal to the cash surrender value at the end of the then-current policy year, except that the insurer may deduct, either from such loan value or from the proceeds of the loan, any existing indebtedness not already deducted in determining such cash surrender value, including any interest then accrued but not due, any unpaid balance of the premium for the current policy year, and interest on the loan to the end of the current policy year.” If the total debt, including interest, reaches the loan value, the policy can terminate, but only after at least 30 days’ notice is mailed. See Fla. Stat. § 627.458. That section does not apply to term policies or to term insurance benefits provided by riders. Any loan still owed at death reduces what your beneficiary receives.
Each option carries its own trade-off, and none fits every household.
Tax and cash-flow questions to check before you cancel
Surrender can create taxable income. The answer depends on the policy’s history and your tax position.
Federal law generally excludes death proceeds from gross income, under 26 U.S.C. § 101(a). The IRS explains that whether life insurance proceeds are taxable depends on the facts.
A loan still owed when a policy ends can also raise tax questions. Ask about this before you request a surrender or let a loan run.
Gather your annual statements and premium history. These records show what you paid into the policy, which is the starting point for any taxable gain. A CPA’s review can also look at how a surrender or loan would affect your household or business cash flow over the next few years.
Special cases: key-person, buy-sell, and cross-border policies
Business-owned policies need their governing agreement reviewed before any cancellation.
A key-person policy belongs to the business. Cancelling it can affect loan covenants a lender may require, a succession plan, and the business’s ability to cover the loss of a key person.
Employer-owned life insurance carries its own federal reporting. Under 26 U.S.C. § 6039I, an applicable policyholder owning employer-owned life insurance contracts issued after the date of enactment of this section must file a return showing the insurance in force and keep the records needed to check compliance. Ending a policy changes the insurance those returns report.
A buy-sell agreement policy funds a contract among owners. If you cancel it without changing the agreement, the remaining owners may lack the money the agreement assumed.
For NRI life insurance, the owner, insured, and beneficiary may live in different countries. That can affect paperwork, signatures, and tax reporting. Check the insurer’s requirements for each party before sending anything.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Steps to take before you submit a cancellation request
Gather your documents first. Then ask the insurer in writing for exact figures before you submit anything.
Your checklist should include the policy number, the insurer’s name, the current statement, the loan balance, the beneficiary and owner designations, and any business or estate documents tied to the policy.
Ask the insurer, in writing, for the surrender or lapse figures, the effective date, and the tax reporting it will send. The insurer’s written figures govern the outcome, not estimates.
Under Fla. Stat. § 627.455, every insurance contract shall provide that the policy be incontestable after it has been in force during the lifetime of the insured for a period of 2 years from its date of issue, except for nonpayment of premiums and, at the option of the insurer, certain provisions relative to benefits in the event of disability and provisions that grant additional insurance specifically against death by accident or accidental means. A new policy has its own contract terms, which may differ from those of the policy it replaces. FINRA notes that comparing policies involves surrender charges, cash value, and replacement considerations. Compare the numbers in writing before you replace anything.
Talk through your situation with our team
If you’re weighing a cancellation, you may be carrying a policy you can no longer afford. You may also be making the call for a parent or a business partner. These are hard decisions to work through alone.
You can contact our team to arrange a coverage review, our first meeting. We’ll look at the policy’s type, ownership, beneficiaries, and tax position together. Any fee for a coverage review is explained before you decide to move forward.
Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice.
Can I cancel and get my money back?
Only a surrender returns cash value, and the amount depends on the insurer’s current figures.
Does stopping premiums end the policy right away?
No. Florida law requires a grace period of at least 30 days.
What to Look at Before You Cancel
Your family's protection
Start with who depends on the death benefit today and whether that need is likely to change.
Your policy's terms
Review the policy form, premium schedule, and any loans or riders that could be affected by a change.
Cash value, if any
Whole life policies can have cash value. Ask what the insurer's current figures show, since those figures can change.
Your cash flow and taxes
Premium payments, loan balances, and tax effects should be weighed together with the coverage itself.
Before you stop paying premiums
Missing premiums can lead to a lapse, and a lapse can end coverage you may not be able to replace on the same terms. Ask for a coverage review before you make any change.
How a Coverage Review Works
Share your policy details
Tell us about the policy, its premiums, and the people it protects so we can look at the full picture.
Review the alternatives
We walk through the choices available, such as keeping the policy as is, adjusting coverage, or reducing premiums, and what each one means.
Look at the tax and cash flow effects
As a CPA firm, we consider how a surrender, lapse, or loan could affect your taxes and household budget.
Decide with a clear view
You decide what happens next, with the facts laid out in plain words.


