



Life Insurance | Florida Families
How Much Life Insurance Could Your Parents Need?
A practical way to think about coverage for your parents, from the family's needs to the policy types that fit them.
By Nischay Rawal · Published November 11, 2026
Adult children often start asking this after a parent’s health changes, a new diagnosis, a move, or a family talk about who pays for final expenses. The short answer is that how much life insurance a parent needs depends on that parent’s situation, not on one standard figure. The death benefit (face amount) is built from the family’s real costs, and the insurer sets the premium after underwriting, which is its review of the application.
This guide covers the cost drivers, a simple way to estimate coverage, term and whole life for a parent, consent rules, and cross-border questions. NR CPAs & Business Advisors is a Miami CPA firm. Insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the firm’s accounting practice.
Why adult children ask how much life insurance a parent needs
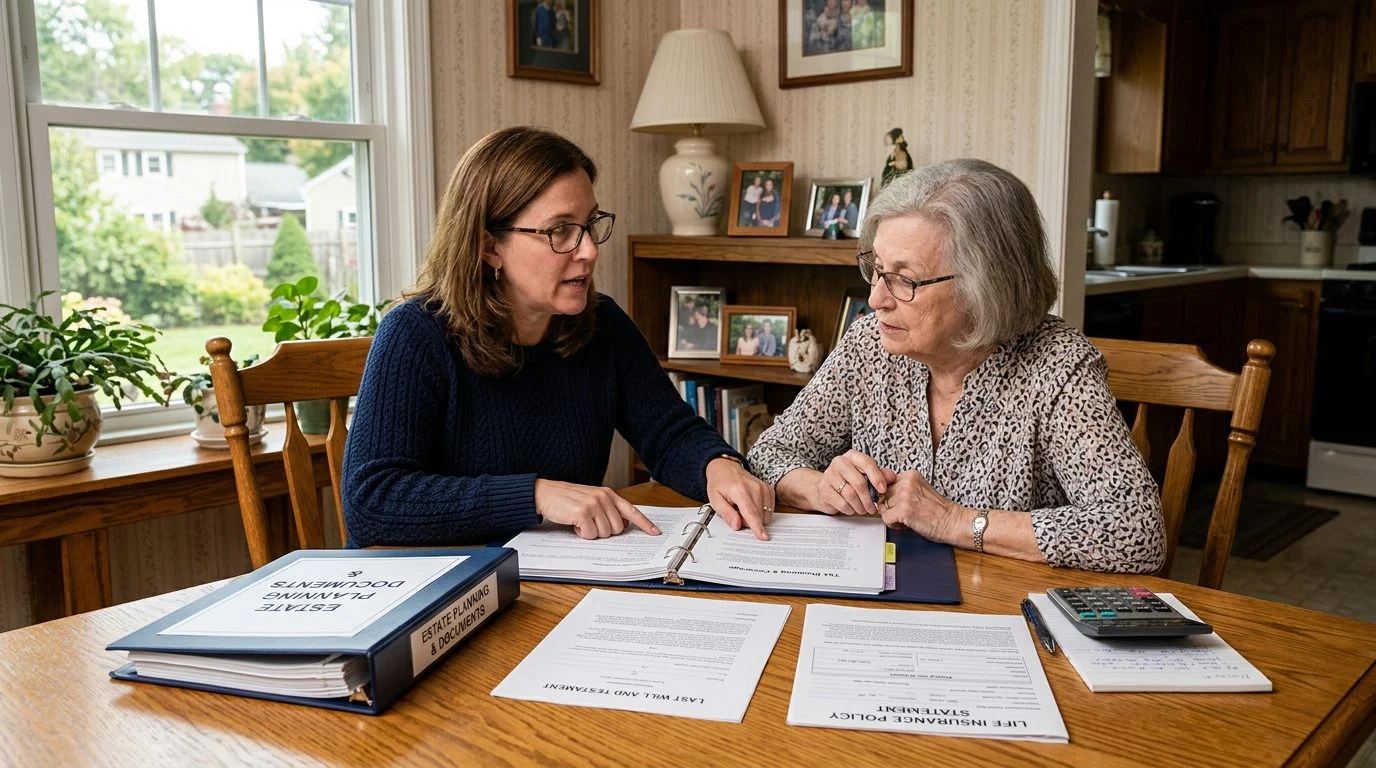
Usually the question comes from a family role, not a product choice. The adult child is often the one who pays bills, arranges a funeral and handles the parent’s paperwork. Two roles matter on any policy. The insured is the parent. The owner pays the premiums and controls the policy, and is often the adult child or a family trust. Who owns the policy affects who controls it, who gets paid and how the proceeds count in an estate.
A common mistake is treating this as one number before the family agrees on who owns the policy and who pays. Existing savings and income also belong in the picture, and they are easier to weigh once the costs are listed. This page is general education, not a recommendation of any one policy.
If a parent's diagnosis or move has you weighing final expenses on top of their care, you don't have to sort it out alone. Our team can walk through the facts with you in a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What drives the cost of life insurance for parents
Four main factors set the premium: the parent’s age, health, the face amount and the policy type. Premiums generally rise as the insured gets older, so waiting usually raises the price for the same coverage. Age on the application must be accurate. Florida law says that if the insured’s age was misstated, the benefit is what the premium would have bought at the correct age, under the insurer’s rate at issue (Fla. Stat. § 627.456).
Health and tobacco use are also rated. Insurers ask health questions, and the answers can change the premium or whether the policy is issued. The insurer assigns an underwriting class from the file, and the premium follows that class. Neither this page nor the firm sets it. A larger death benefit costs more, and a lifelong policy generally costs more than term coverage with the same face amount. Term and permanent coverage are different structures, and a coverage review with our team can explain how each may fit your situation.
How to estimate the coverage amount for a parent
Start by adding up four cost groups, then compare the total with money the family already has. Use this simple worksheet:
- Final expenses: funeral or cremation costs, burial costs, medical bills still open at death, and travel for family.
- Debts: a mortgage, a car loan, or a credit line the adult child co-signed with the parent.
- Household support: income the parent contributes, and how many years the household would need to replace it.
- Estate planning needs: possible estate tax, cash to settle the estate, and how the payout reaches heirs.
Under federal estate tax law, funeral and administration expenses may be deducted in determining the taxable estate, to the extent allowable under the laws of the jurisdiction where the estate is administered (26 U.S.C. § 2053). For 2026, the IRS sets the basic exclusion amount at $15,000,000 (IRS 2026 exclusion figure). Whether a parent’s estate may owe federal estate tax turns on its size compared with that amount. The total is a starting point for a coverage review, not a promise of what any policy will pay.
Term or whole life for a parent: how each works
Term life covers a set number of years, while whole life is designed to last for the insured’s lifetime. Term policies generally have no cash value at the end of the term, so the length of the need often drives the choice. Whole life includes a cash value component. Its guaranteed and non-guaranteed values should be shown separately. Dividends, where a policy pays them, are not guaranteed. Whole life usually costs more than term for the same face amount, so monthly cash flow is part of the decision. The Florida Department of Financial Services life insurance guide explains cash value and policy loans in plain terms.
Policy loans need careful planning. Florida law requires that, after a policy has a cash surrender value and while no premium is in default, the insurer will advance a loan on proper assignment or pledge of the policy. If unpaid interest pushes total debt to the loan value or higher, the policy may terminate, but only after at least 30 days’ notice is mailed (Fla. Stat. § 627.458). That loan rule does not cover term policies. Fla. Stat. § 627.458 reads: “(4) This section does not apply to term policies or to term insurance benefits provided by riders or supplemental policy provisions.”
Tax status also matters. A policy that meets the federal definition can still become a modified endowment contract if the accumulated amount paid under the contract at any time during its first 7 contract years exceeds the net level premiums that would have been paid for paid-up future benefits after 7 level annual premiums (26 U.S.C. § 7702A). That status can affect how the policy is taxed, so a CPA’s view of tax and cash flow belongs in this decision.
Consent, insurable interest and health questions
Before an insurer issues a policy on a parent, the consent and insurable interest rules must be met. Florida law says no one may buy coverage on another person’s life unless the benefit is payable to that person, the person’s personal representative, or someone with an insurable interest when the contract is made (Fla. Stat. § 627.404). An insurable interest can rest on a close family relationship by blood or law with a substantial interest engendered by love and affection, or on an expectation of a substantial pecuniary advantage from the person’s continued life, health, and safety and a consequent substantial pecuniary loss by reason of that person’s death, injury, or disability. Whether an adult child has one turns on the facts. The interest must exist when the contract is made, not after coverage starts.
The parent must also agree in writing. Except for a prepaid funeral contract, group life insurance, or group or blanket accident, health, or disability insurance, a contract on a person may not be carried out unless that insured, having legal capacity, applies for or consents in writing on or before the time the contract is entered into. So the parent’s signed consent belongs on the application from the start.
Fully underwritten policies ask health questions, and issue may depend on insurability. Underwriters may review medical records, medications and recent treatment. Incomplete or inaccurate answers can delay an application or change its outcome.
Parents living abroad and cross-border family situations
Coverage for a parent who lives outside the United States depends on the insurer’s underwriting and claims process in that country, so confirm it early. NRI life insurance is designed for non-resident relatives and for households that span the United States and another country. Residency, currency and paperwork can change the application. Start by confirming the parent’s country of residence, residency status, and whether the insurer can underwrite and pay claims there.
Tax treatment needs a second look. Under 26 U.S.C. § 101(a), amounts paid because of the insured’s death are generally excluded from gross income, subject to exceptions. The IRS guidance on life insurance proceeds says interest received on proceeds is taxable. Estate rules are separate. If the parent owns the policy, the proceeds can be part of the gross estate (26 U.S.C. § 2042). For cross-border heirs, ownership and beneficiary choices may point toward a trust or an estate plan, and a CPA reviews those structures alongside the insurance.
Insurance is offered through the licensed agent, separately from the accounting practice. Any tax or accounting services are described and priced in a separate written engagement.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Bringing your questions to a coverage review
A coverage review is the first meeting, where the family’s facts are gathered before any recommendation is made. Bring the parent’s age, health history and medications, current coverage and policy statements, debts, household support, and country of residence. Nischay Rawal, a licensed insurance agent, reviews term life, whole life, estate planning life insurance and NRI life insurance options with the family. Any commission the agent may earn is disclosed in writing before any engagement, along with the other compensation details. Our team can walk through each of these facts with you.
Can I buy life insurance on my parent without their consent?
Florida law generally requires the person insured, who must have legal capacity to contract, to apply for or consent in writing to the contract and its terms on or before it is entered into. The exceptions are a prepaid funeral contract, group life insurance, group or blanket accident, health, or disability insurance, a policy on a minor younger than 15 years of age obtained by a person with an insurable interest in the minor or on whom the minor depends for support, and any policy of life insurance to which s. 624.402(8) applies, since the section does not apply to those policies (Fla. Stat. § 627.404).
Is life insurance paid to a beneficiary taxable?
For purposes of the federal estate tax, IRC § 2053 sets the deductions used to determine the value of the taxable estate and does not address whether death benefits are included in gross income. Amounts received under a life insurance contract by reason of the insured’s death, whether in a single sum or otherwise, are generally excluded from gross income (IRS).
How much life insurance does a parent need?
There’s no single figure. Total final expenses, debts, household support and estate needs, then compare that total with resources the family already has.
If a parent’s recent diagnosis or move has you planning final expenses while you manage their care, you don’t have to work out every number alone. Contact NR CPAs & Business Advisors to set up a coverage review with our team.
How NR CPAs & Business Advisors Approaches Coverage
A CPA's View of Cash Flow
We look at how a policy's premiums fit the household budget and how the coverage fits the wider financial picture.
Built for Indian-American Households
We work with families and business owners across the United States, including Indian-American households that often support parents and extended family.
Coverage Review First
Our first step is a coverage review, a conversation about your parents' needs, your goals and the policy types that may fit.
Insurance Offered by a Licensed Agent
Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice.
Start the Conversation Early
Coverage is easier to plan before health changes. Gather your parents' current policies, their main sources of income and support, and any outstanding debts before you talk with us.
Factors That Shape the Right Amount
Who Depends on Your Parents
Consider whether they support children, grandchildren, a spouse or other relatives, and how that support would continue.
Debts and Final Expenses
Mortgages, loans and funeral or final expense costs are common reasons families look at the amount of coverage they carry.
Health and Underwriting
Fully underwritten policies ask health questions, and issue may depend on insurability. Your parents' health history will shape the options available.
Policy Type and Purpose
Term, whole life, estate planning life insurance and other policy types serve different goals, so the right amount often depends on the policy chosen.


