



Term Life Insurance | Florida
Protect your loved ones with the right amount of term coverage
Start with the people who depend on your income, then match the coverage to what they would need.
By Nischay Rawal · Published November 11, 2026
You may be asking this for your own family, or for a spouse, parent or business partner. The short answer is that the right amount of term life insurance replaces the money your family would need, then subtracts what they already have.
This guide shows how that number is built, what choices come with it, and what a coverage review involves.
What is term life insurance and who is it for?
Term life insurance pays a death benefit to the beneficiaries you name if the insured dies during a set term. Premiums are usually level for that term.
FINRA describes term life insurance as coverage for a limited period. Whole or permanent life insurance covers the insured for life and includes a cash-value feature.
The key parts are:
- Death benefit: the amount paid to beneficiaries.
- Term length: how many years the coverage lasts.
- Beneficiary: the person or entity you name to receive the payment.
- Premium: the amount you pay to keep the policy in force.
- Renewability: whether coverage can continue after the term, and on what terms, as stated in the policy form.
Term coverage often suits parents with young children, spouses who rely on a partner’s paycheck, and business owners whose company depends on one person. For the broader category, see term life insurance basics.
If you're weighing how much term coverage your family needs, our team can walk through your numbers with you in a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
If you are married with young children and make $75,000 per year, how much term life insurance should you have?
There is no single fixed amount for this household. The number comes from the family’s own income needs, debts, future costs and existing coverage. A common approach starts with the income the family would need replaced, then subtracts resources already in place.
Start with these building blocks:
- Income replacement: how many years the surviving spouse would need the lost income to cover household costs.
- Debts: the mortgage balance and other loans still owed.
- Education goals: future college costs, if you plan for them.
- Final expenses: funeral and estate settlement costs.
- The other spouse’s income: what the surviving spouse earns and could keep earning.
Then subtract what already exists: employer group coverage, personal policies in force, and savings the family could use.
Here is the method with a $75,000 income as an example only. Multiply the yearly income the family would need replaced by the number of years needed. Add debts and goals. Subtract existing coverage and savings. The result estimates need. It does not predict how the money would be used.
The insurer’s underwriting decides the amount it will issue and the premium. Neither can be promised in advance.
How long should you have life insurance?
Match the term to the years your family depends on your income. That often means until children are independent or a mortgage is paid down.
- Fixed term: the death benefit stays level for the chosen term.
- Decreasing term: the death benefit falls over time. A declining balance, such as a loan, may fit this design.
A longer term usually costs more per year than a shorter one. Age and health at application also affect the premium. See term life insurance rates by age.
Some designs return premiums if no claim occurs. The policy form states those terms.
If a premium is late, Florida law requires a grace period of at least 30 days for premiums after the first.
Does term life insurance build cash value?
No, term life insurance does not build cash value. It pays a death benefit only if the insured dies during the term.
Whole life insurance works differently. It includes a cash-value feature, as FINRA explains. It has different costs and terms, so compare the policy forms directly.
If the term ends without a claim, the coverage ends. Any renewal or conversion terms appear in the policy form. Read them before you choose a term.
How much term coverage do business owners need?
Business owners often size term coverage around the company’s obligations. These include losses from a key person, business loans, and funding for a buy-sell agreement.
- Key person insurance: a policy on an essential person in the business, with the business as owner and beneficiary.
- Buy-sell agreement insurance: policies that can help fund the purchase of a deceased owner’s interest under a written agreement.
Under Fla. Stat. § 627.404, a business entity has an insurable interest in the life, body, and health of its owners, directors, officers, partners, and managers, or of its key employees or key persons (including those of an affiliate or subsidiary), if consent is obtained in writing from them before the insurance is purchased, where a key employee or key person is an individual whose position or compensation is described in section 101(j)(2)(A)(ii) of the Internal Revenue Code of 1986. Fla. Stat. § 627.404 also provides that the business entity, or its affiliate or subsidiary, may not retaliate or take adverse action against a key employee or key person who does not consent to the issuance of insurance on that person’s life. See Fla. Stat. § 627.404.
See 26 U.S.C. § 264. Owners who live outside the United States should bring their ownership details to the review.
How does a term life insurance coverage review work?
A coverage review is the first meeting. It’s where your family’s numbers get sorted out with a licensed agent. To schedule one, contact the firm.
- Contact the firm and share the basic family and business picture.
- Gather information on income, debts, dependents, existing policies, employer coverage and any business agreements.
- Review options with the licensed agent, including how the numbers change with different terms.
- Complete the application. A fully underwritten policy requires health questions, and issue may depend on insurability.
- Wait for underwriting. The insurer decides whether to issue or decline the policy. Timing is set by the insurer.
- Read the policy form, including renewability and any age-based change.
Insurance is offered by the licensed agent, Nischay Rawal, separately from the accounting practice. Florida law requires agents to say they are acting as insurance agents. If the firm earns a commission on a product it sells to a client, it must disclose that to the client in writing, as Florida law requires.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Why work with NR CPAs & Business Advisors for term coverage?
NR CPAs & Business Advisors is a Miami CPA firm. It helps families, professionals and business owners across the United States choose and buy life insurance. The firm brings a CPA’s view of tax and cash flow to that work.
- CPA-informed review: tax and cash flow questions are part of the discussion.
- Separate roles: the licensed agent handles insurance, apart from the accounting practice.
- Florida markets: the firm serves families in Miami, Fort Lauderdale, West Palm Beach, Orlando, Tampa and Jacksonville.
- Indian-American households and NRIs: the firm explains coverage in plain language for households and non-resident Indians.
- No rebates or inducements: the firm offers no rebates or inducements to buy.
- Support: support staff handle office work. The licensed agent handles insurance discussions.
Our team works through each coverage review one step at a time, so you know what comes next.
Frequently asked questions
How do I choose a life insurance policy?
Start with the need, then choose the term and policy type. Read the policy form for premium, renewal and exclusion terms before you decide.
Is the death benefit taxable?
Under the general rule, life insurance death benefits are excluded from gross income. The IRS notes that interest received on those proceeds is taxable.
What changes the cost of term coverage?
Age, health, tobacco use, term length and coverage amount all affect premiums. The application shows how each factor applies.
Do I need to answer health questions?
Yes, a fully underwritten policy requires health questions. Issue may depend on insurability.
What happens when the term ends?
Renewability and any age-based change are stated in the policy form. Review those terms before you buy.
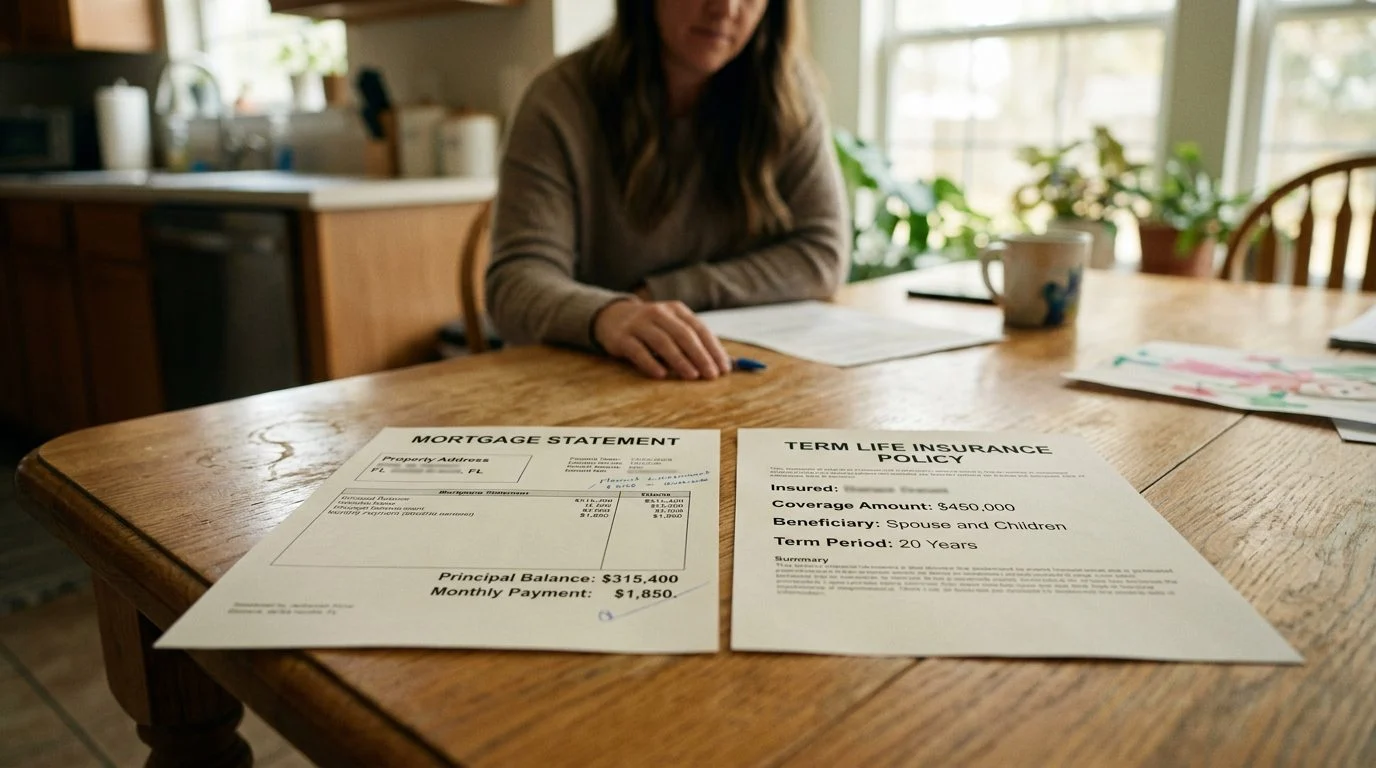
Talk with our team about your family’s coverage
You may be gathering facts for a spouse, a parent or a business partner. You may also be sorting this out after a new child, a home purchase or a change in your company. If you’re weighing how much term coverage protects your loved ones, contact our team to set up a coverage review with the licensed agent.
Why families and business owners work with NR CPAs
Coverage sized to your needs
We help you work out how much term coverage fits your family's income, debts and future expenses.
A CPA's view of cash flow
We look at how premiums fit into your budget and tax picture before you decide.
Support for Indian-American households and business owners
We help families and owners across the United States, including those with ties to India and NRI situations.
Clear explanations in plain words
We walk you through the policy form, including premium, renewal and exclusion terms.
How to estimate the coverage you need
List your income needs
Consider how many years your household would need replacement income and what that income supports.
Add your debts
Include mortgage balances, loans and other obligations your family would need to cover.
Plan for children and final costs
Account for education goals, daily living costs and final expenses.
Review it with our team
Bring your numbers to a coverage review and we will help you compare the options.
Before you choose a term
Term life insurance covers a set period of years. Read the premium, renewal and exclusion terms in the policy form before you decide. Term life insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the firm's accounting practice. Insurer names and policy details are provided during your coverage review.


