



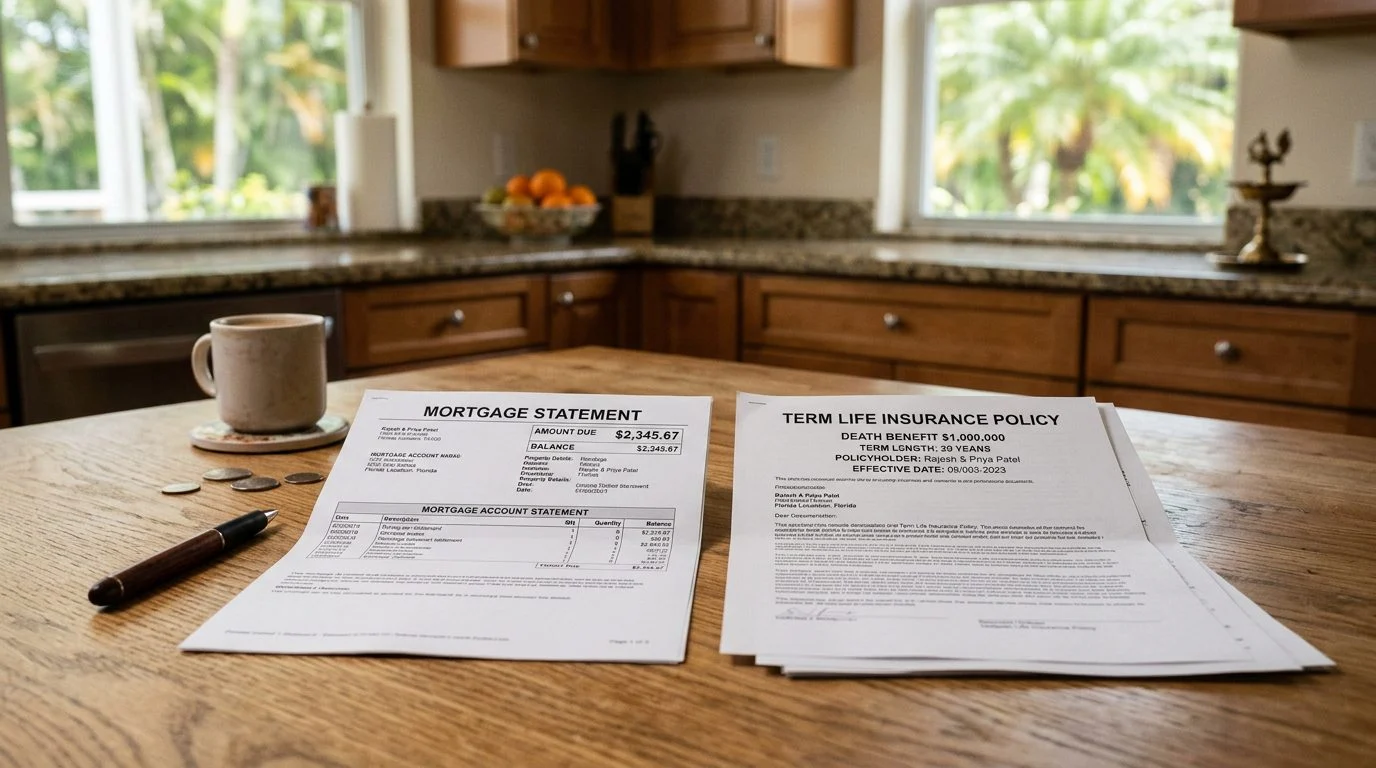
Term Life Insurance | NRI Families | Florida
Protect your loved ones with term life insurance in Florida
Coverage planned around your household's visa status, family obligations and monthly cash flow, with a CPA's view of the numbers behind each choice.
How we approach your coverage review
Built around your household
We look at your income, dependents and obligations in the United States and abroad before discussing any term policy.
A CPA's view of cash flow
We weigh premiums against your budget and your tax picture so the decision fits how your household actually runs.
Plain-language explanations
We explain insurance terms in simple words, including what a term policy covers, what it does not cover and when coverage ends.
Guidance from a licensed agent
Nischay Rawal, a licensed insurance agent, leads coverage reviews for this page, supported by our team.
By Nischay Rawal · Published November 9, 2026
If your spouse is not a U.S. citizen, you may be asking who should own a life insurance policy and who should receive the money. Term life insurance for NRI families can cover either spouse. The roles you assign decide who signs, who must consent and who gets paid.
This page explains those roles, the health questions that decide issue and rate, and the tax points a CPA reviews first.
What term life insurance for an NRI spouse is, and who it fits
Term life insurance covers a person for a set period at a set premium. It pays a death benefit only if the insured dies within that term. Whole or permanent life insurance lasts for life and adds a cash-value feature. FINRA’s insurance overview explains the difference.
A term policy can be written on either spouse. Insurers set their own documentation rules, so a spouse’s citizenship or visa status can affect what the application asks for.
This page fits families in Florida where one spouse holds H-4 status, holds a green card, or has no current U.S. status. It applies to single-earner and dual-income homes alike. The real question is what the surviving spouse would lose financially.
Insurance is a separate decision from tax filing. NR CPAs & Business Advisors is a Miami CPA firm. Its accounting practice is separate from the insurance, which is offered through its licensed agent.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Owner, insured and beneficiary: three roles, three decisions
The owner controls the policy. The insured is the person whose life is covered. The beneficiary receives the death benefit. One person can hold all three roles, or each role can go to a different person.
Common arrangements include:
- Each spouse insures the other, and each owns a policy on his or her own life.
- One spouse owns a policy on the other.
- A trust or another third party is named as owner or beneficiary.
Florida law lets any individual of legal capacity buy a policy on his or her own life for any beneficiary. A policy on another person’s life must pay the insured, the insured’s personal representative, or someone with an insurable interest when the contract is made (Fla. Stat. § 627.404). The substantial pecuniary advantage test also requires a consequent substantial pecuniary loss by reason of the death, injury, or disability of that other person. Whether your household meets that test depends on your facts, so the review checks it first.
Florida also says the insured, with legal capacity, must apply for the contract or consent to it in writing on or before the time the contract is entered into. Under Fla. Stat. § 627.404(5), a contract of insurance upon a person, other than a policy of prepaid funeral contract, group life insurance, or group or blanket accident, health, or disability insurance, may not be carried out unless, on or before the time the contract is entered into, the person insured, having legal capacity to contract, applies for or consents in writing to the contract and its terms. There is an exception: anyone with an insurable interest in the life of a minor younger than 15, or anyone a minor younger than 15 depends on for support and maintenance, may obtain a policy of insurance on the minor. Plan to have the insured person’s written consent in hand before the application is submitted.
Name a contingent beneficiary too. If the primary beneficiary dies first, the contingent beneficiary is next in line for the death benefit.
Changing the owner or beneficiary later depends on the policy’s terms. Read them before you sign. Our guide on choosing a policy owner walks through the choice.
Insurability: health questions and underwriting
Term applications ask health questions. The insurer decides whether to issue the policy and at what rate.
Underwriting is the insurer’s review of your application. The insurer may check health history and medical records, and sometimes it requires an exam. Then it offers a rate class or declines the application.
Insurers commonly weigh:
- Age
- Height and weight
- Tobacco use
- Personal and family medical history
- Current medications
- Coverage amount and term length
Insurers may also ask for identification and residency documents. Requirements vary by insurer, so ask which documents each one needs.
Many policies have a contestability period. FINRA notes that a typical period for life insurance is two years. During that time, the insurer can question the application’s answers. Answer every health question fully and accurately.
Application steps and what to expect
The process moves from a coverage review to an issued policy. Underwriting sets most of the timing.
- Coverage review: You go over your goals, roles and coverage amount.
- Roles decided: You name the owner, insured, beneficiary and contingent beneficiary.
- Application completed: The insured signs the application and consents in writing.
- Health questions answered: Every question is answered in full.
- Underwriting: The insurer reviews the file.
- Policy issued: You review the policy terms before you rely on them.
Gather these before the review: identification, current coverage, health history, the coverage amount you want, and any immigration documents the insurer may request.
Timing varies by insurer and by the health information needed. Ask for the insurer’s expected timeline during the review. Premium amounts, renewal terms and any age-based change come from the insurer’s policy terms. We walk through those terms during the coverage review.
CPA-view tax and cash-flow points
Death benefits paid because of the insured’s death are generally excluded from federal gross income. The rule has listed exceptions (26 U.S.C. § 101). Interest on the proceeds is taxable, according to the IRS life insurance proceeds FAQ.
Ownership affects the estate. Under federal law, proceeds payable to other beneficiaries count in the insured’s gross estate if the insured held incidents of ownership at death (26 U.S.C. § 2042). A transfer of a policy within three years of death can also pull it back into the estate if the insured would have held a retained interest under sections 2036, 2037, 2038, or 2042, unless the transfer was a bona fide sale for an adequate and full consideration in money or money’s worth (26 U.S.C. § 2035).
Gift tax rules can apply when one spouse pays for coverage the other spouse owns. The general annual gift exclusion is $19,000 per donee for 2026 (IRS gift tax FAQ).
Treat premiums as a fixed commitment for the full term. Fit that payment into your household budget before you apply. Check the tax position against your own facts.
Questions buyers ask about spouse coverage
Can a non-citizen spouse be the insured?
Yes, a term policy can be written on a non-citizen spouse. The insurer decides issue based on underwriting.
Does a spouse on H-4 need a green card to be insured?
Insurers set their own documentation rules. Ask about the requirements during the coverage review.
Can the insured spouse own the policy?
Yes. Ownership affects the estate, so review it against the estate rules above.
Can the U.S. citizen spouse own a policy on the other spouse?
Florida law requires the benefits to be payable to the insured, the insured’s personal representatives, or someone with an insurable interest when the contract is made, and the insured must consent in writing on or before entering into the contract.
Does changing the beneficiary need the insured’s consent?
It depends on the policy’s terms and who holds the owner’s rights. Confirm this in the review.
What if a health question reveals a condition?
The insurer decides issue and rate. Answer every question fully so the review can compare the terms that apply.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Insurance through a licensed agent, and a coverage review
Insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the firm’s accounting practice. Nischay Rawal is licensed in Florida.
NR CPAs & Business Advisors is a Miami CPA firm. It helps families, professionals and business owners across the United States choose and buy life insurance, with a CPA’s view of tax and cash flow. Its life insurance work covers:
- Term life insurance
- Whole life insurance
- Key person insurance
- Buy-sell agreement insurance
- Estate planning life insurance
- NRI life insurance
Our team serves households in Florida, including Miami, Fort Lauderdale, West Palm Beach, Orlando, Tampa and Jacksonville.
Deciding who owns the policy and who receives the benefit is the step that protects your loved ones. Call us today, or reach our team through the contact page, to set up a coverage review.
Important: insurance is offered separately
Term life insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice. A term policy covers only the stated term. Coverage ends when that term ends unless the policy is renewed or converted, and premiums can change with age. Issue depends on underwriting, which includes health questions.
Questions to bring to your coverage review
Immigration status
Ask how the insurer documents a spouse on a visa or a green card. Insurers set their own requirements, so confirm them early.
Length of the term
Compare the years your family will need protection, such as a mortgage, children's schooling or a business loan.
Coverage you already have
Review any group coverage through work and any policies you already hold before adding a new term policy.
Family and beneficiaries
Discuss beneficiaries and any financial obligations that extend to relatives outside the United States.


