



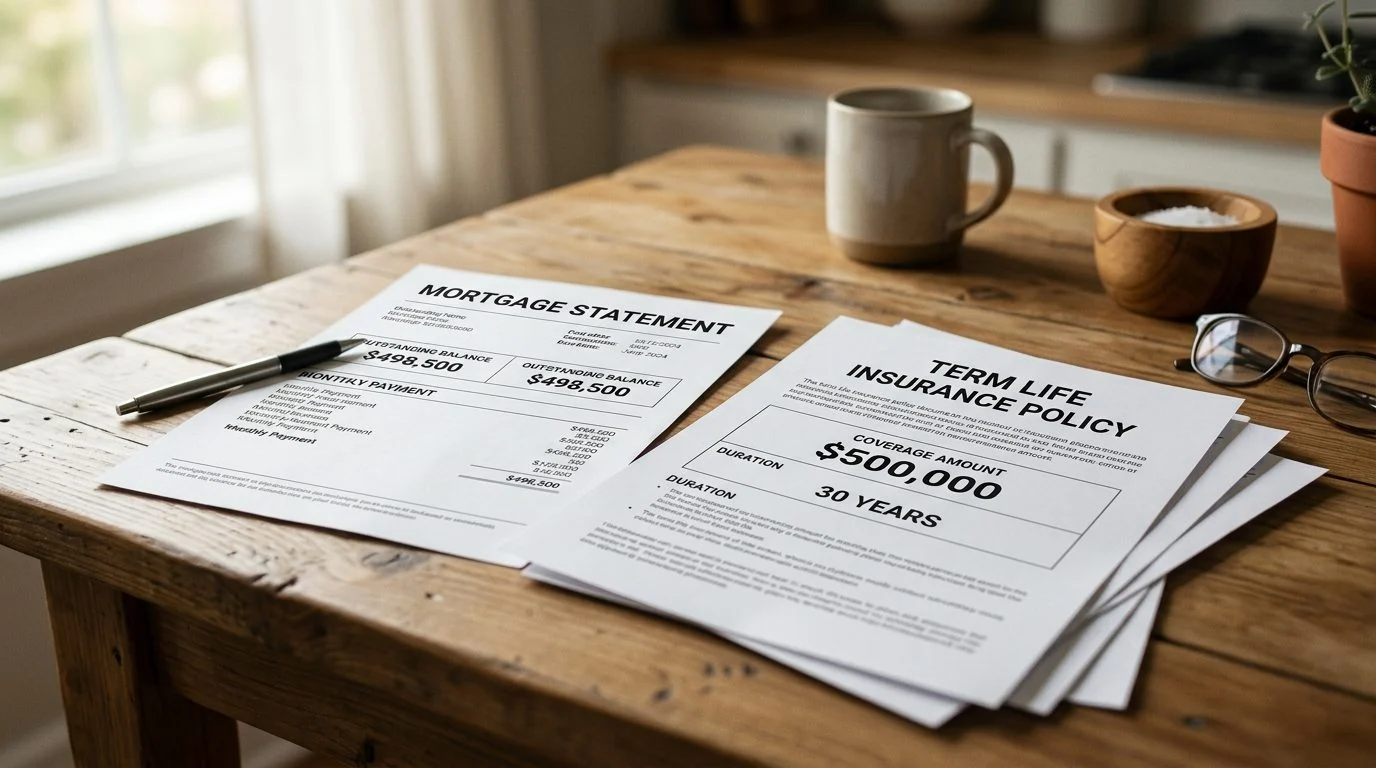
Term Life Insurance | Miami and Florida
What Does a $500,000 Term Life Policy Cost?
The price depends on the person being insured. NR CPAs & Business Advisors can walk you through the factors that shape the figure and help you plan coverage that protects your family.
By Nischay Rawal · Published November 3, 2026
A $500,000 term life insurance policy has no single price. The cost depends on the insurer, your age, your health, whether you use tobacco, and the term length you choose. This page explains each driver so you can see what moves the number up or down.
Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors.
What a $500,000 term life insurance policy means in plain words
A term life insurance policy pays a death benefit if the insured person dies during a set period. That period is the term, such as 10, 20 or 30 years. If the insured person outlives the term, the coverage ends unless the policy lets you renew it.
The face amount is the death benefit. In this case, the face amount is $500,000. The premium is the amount you pay to keep the policy in force.
Term coverage has no cash value. The FINRA insurance guide explains that term life insurance has a limited coverage period, while whole or permanent life insurance offers lifetime coverage and a cash-value feature.
The premium pays for the insurance coverage. A term policy pays only when the insured dies during the term. It does not build investment value.
If you are researching coverage for a spouse, a parent or a child after a family change, you do not have to work this out alone. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.

Why there is no single price for $500,000 of coverage
Insurers set premiums by sorting each applicant into an underwriting class. That class reflects risk factors such as age, sex, health history and tobacco use. Two people who ask for the same $500,000 can receive different premiums.
The insurer and the policy form matter too. Each company uses its own rate tables and rules. So a number from a general chart may not match the premium you would actually be offered.
That is why we do not quote premiums on this page. The figure has to come from a coverage review that looks at the specific insured person and the specific policy.
How the term length changes what you pay over time
Longer terms mean more years of premium payments. A 30-year term covers more years than a 10-year term, so the total paid over the term is usually higher.
A level premium applies only for the stated level term. When that level period ends, the premium can change. Renewal costs depend on the insured’s age and on the policy’s renewability and age-based change terms. Those terms must be explained when a specific policy is described.
Match the term to a real obligation. Common examples include a mortgage balance, years until children finish school, or a business loan that a family member would have to repay. Ask how long each obligation lasts, then compare that length to the term you are considering.
Health questions, tobacco use and insurability
A fully underwritten term policy asks health questions. The insurer decides issue and premium based on the answers and any records it requires. The application may also include a medical exam or a records review.
Tobacco use often moves an applicant into a higher-cost class. Recent medical history can do the same. Insurers look at both when they sort applicants.
Health history does affect whether a policy is issued, and it can affect claims. Do not assume it will not matter. Answer every health question on the application fully and accurately.
Term versus whole life when cost is the question
Whole life insurance is permanent coverage with a cash value component. The ALDOI consumer guide on policy types explains the difference between term and whole life, including how whole life premiums and cash value work.
Whole life often costs more than term for the same face amount. A PMC article on life insurance ownership notes that whole life policies may cost more than term insurance, have limited liquidity, and can carry penalties for withdrawing cash.
Term is designed for a set period. Whole life is designed to last for the insured’s life, as long as premiums are paid under the policy terms.
If a whole life policy pays dividends, state that dividends are not guaranteed. Under Florida law, any mention of policy dividends must be accompanied by a statement that they are not guaranteed. Guaranteed values and non-guaranteed values should be shown separately.
Neither term nor whole life is an investment or a promise of returns. Compare them by the coverage they provide and the cost of that coverage.
How a CPA sizes $500,000 against family cash flow
A CPA looks at the coverage amount as a cash flow question. Start with the income the family would need to replace. Then add debts, education costs and final expenses. Subtract assets and existing coverage that would already help.
The result is a range to test, not a target. $500,000 may fit one household and be too much or too little for another.
Next, look at the premium in the household budget. Ask how the payment fits with other monthly and yearly costs. Ask how it fits with the tax picture as well. Tax rules can help or limit a family in some cases. For example, 26 U.S.C. 101(a) generally excludes amounts paid because of the insured’s death from gross income. Interest paid on proceeds held by the insurer is a separate matter and can be taxable.
Estate size can also matter. Under 26 U.S.C. 2042, proceeds payable to other beneficiaries can be included in the gross estate when the decedent held incidents of ownership at death. Ask about ownership before you buy.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
NRI and Indian-American households: what to check
Residence outside the United States, or a visa status, can affect which insurers and policy forms are available. It can also change the documents the insurer needs. Ask early about what your family’s situation requires.
An agent may offer a specific policy only where the agent is currently licensed by the department and appointed by an appropriate appointing entity or person. Fla. Stat. 626.112 says no person may act as or hold out as an insurance agent unless currently licensed and appointed. Nischay Rawal will confirm the states where he is licensed as part of a coverage review.
A coverage review can cover family members who live in different countries. The review shows what options exist for them. It does not promise any result for them.
Florida and Miami: what to check locally
Florida law sets some baseline rules for every life insurance contract. Under Fla. Stat. 627.453, a policy must allow a grace period of not less than 30 days to pay any premium after the first. The policy stays in force during that grace period.
Under Fla. Stat. 627.455, a policy must be incontestable after it has been in force during the insured’s lifetime for 2 years from its date of issue. Fla. Stat. § 627.455 reads: “Every insurance contract shall provide that the policy shall be incontestable after it has been in force during the lifetime of the insured for a period of 2 years from its date of issue except for nonpayment of premiums and except, at the option of the insurer, as to provisions relative to benefits in event of disability and as to provisions which grant additional insurance specifically against death by accident or accidental means.” Certain items are excepted, including nonpayment of premiums. Accurate answers at application still matter.
For a Miami household, local factors can shape the review. These include real estate, business interests, and where adult children or parents live. The review should look at all of them together.
Florida law also governs how life insurance can be advertised and sold. Any policy you consider should be described accurately, and no state agency endorses this firm or any insurer.
Next step: a coverage review with Nischay Rawal
If you are researching coverage for a spouse, a parent or a child after a family change, you do not have to work this out alone. Many readers are gathering facts for someone else, and that is a reasonable place to start.
Call the firm to set up a coverage review with Nischay Rawal, a licensed insurance agent. We will look at the face amount, term length, health questions and cash flow together. The goal is to help you protect your loved ones with a plan that fits your household.
We disclose any compensation for insurance in writing before any engagement.
Frequently asked questions
Is $500,000 term life insurance cheap?
It depends on the insured’s age, health, tobacco use, term length and the insurer. A coverage review is the way to get a figure for a specific person.
Does a 30-year term cost more than a 20-year term?
Usually the total paid over a longer term is higher, because there are more years of premiums. The exact amount depends on the policy.
Does tobacco use change the premium?
Yes. Tobacco use often places an applicant in a higher-cost class.
What is a premium?
The premium is the amount you pay to keep the policy in force. A term policy does not build investment value.
What a coverage review covers
Your family's protection needs
We start with the people who depend on your income and the expenses they would need to cover.
Policy terms in plain words
We explain term length, premiums, renewal and what the policy does and does not cover.
Straight answers
Ask how a $500,000 term policy fits with your budget and your other financial goals.
Households and business owners
We address personal coverage as well as key person and buy-sell needs for owners.
What affects the price of a $500,000 term policy
Age and health
Insurers review age and health history when they set a rate. Health questions are required, and issue may depend on insurability.
Tobacco use
Tobacco use is one of the factors insurers consider when pricing a policy.
Length of the term
A longer term means more years of premiums, so the total paid over the life of the policy can be higher.
The insurer
Each insurer uses its own rate table, so the same coverage can be priced differently from company to company.
Important disclosure
Term life insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors. Any premium figure depends on the insured person's age, health and other factors and requires a coverage review.
Protect your loved ones. Start with a coverage review.
Related practice areas
- Term Life Insurance in Florida
- Term Life Insurance in Miami
- Is Life Insurance Included in a Trust? Florida Guide


