



Term Life Insurance | Florida
Plan Term Life Coverage for Your Family's Next Chapter
A CPA's view of cash flow, tax and coverage needs, offered through a licensed insurance agent.
Why Families and Business Owners Talk With Us
Coverage Review First
Our first meeting is a coverage review, where we look at your goals, your budget and the term you need before any policy is discussed.
A CPA's Perspective
Our team considers how a life insurance premium fits with your household cash flow, your tax situation and your broader financial plans.
Plain-Language Explanations
We explain policy terms, limitations and exclusions in everyday words so you can make an informed decision.
Experience With Indian-American Households
We work with families and business owners across the United States, including Indian-American households, on personal and business coverage needs.
By Nischay Rawal · Published November 12, 2026
You want to know how much a $500,000 term life insurance policy costs at age 60, and you want a straight answer. There is no single price.
When you are weighing a policy, the real question is what it will cost you, and that depends on a coverage review based on your own case. This page explains what the policy is, what drives the rate, how term length changes the picture, and where term coverage falls short. It is written for families, professionals, and business owners in Florida and across the United States, including Indian-American households.
What a $500,000 Term Life Insurance Policy Is and Who It Fits
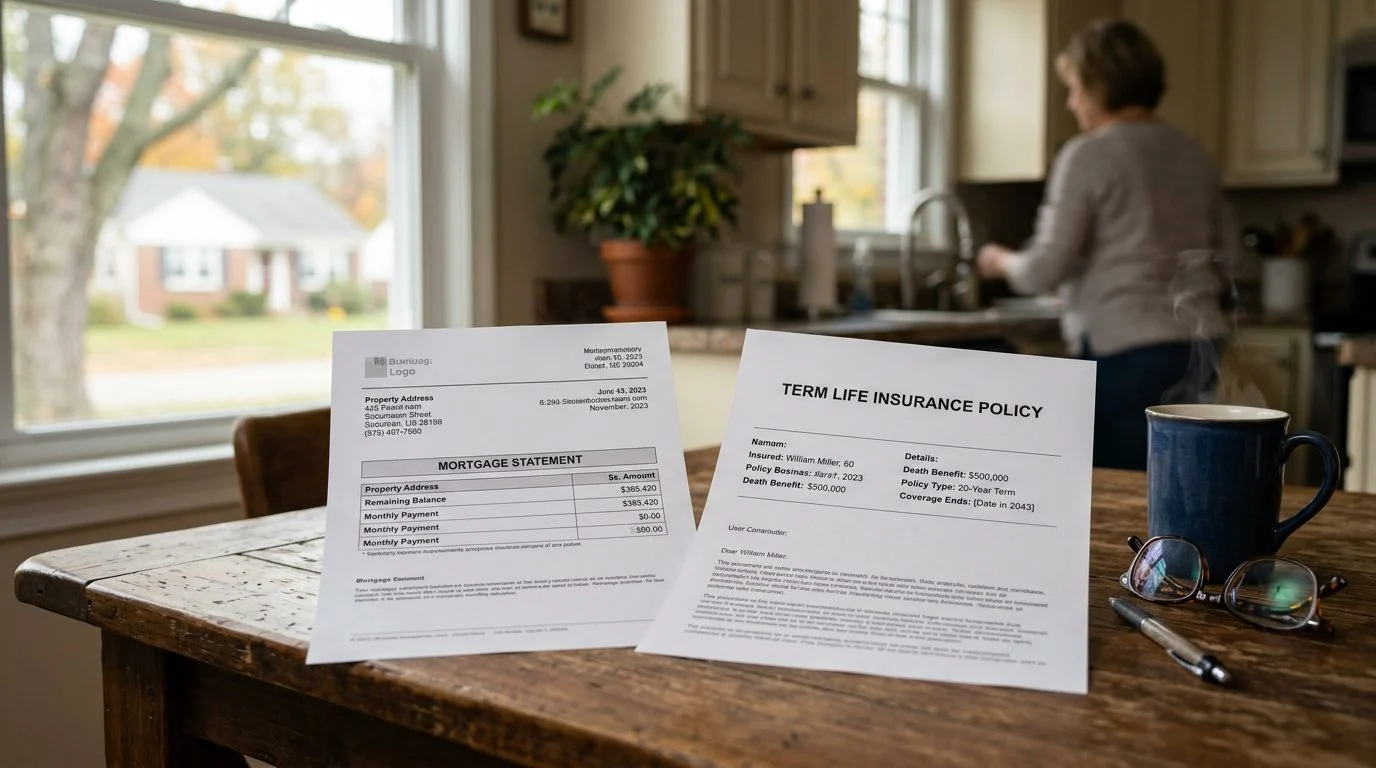
A $500,000 term life insurance policy pays a $500,000 death benefit to the named beneficiaries if the insured dies during a set number of years. That period is the term you choose.
The $500,000 is the face amount. It is a death benefit, not a cash account or a savings balance.
People in their early sixties often look at this amount for a few reasons:
- Replacing income so a spouse can keep up household bills.
- Paying off a mortgage or other debts.
- Covering final expenses.
- Meeting a business or estate need, such as a loan tied to a company.
This page describes a generic term life insurance policy. When we describe a specific insurer’s policy, we name that insurer.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.

What the Policy Covers and What It Does Not
A term policy pays its death benefit only if the insured dies while coverage is in force.
Review these parts of the policy form before you decide:
- The death benefit and face amount.
- The term length and its end date.
- The named beneficiaries.
- The premium schedule and any age-based changes.
Florida law requires every life policy to be incontestable after it has been in force during the insured’s lifetime for 2 years from its issue date, except for nonpayment of premiums and, at the insurer’s option, certain disability benefit provisions and accidental death additional-insurance provisions (Fla. Stat. § 627.455). Fla. Stat. § 627.455 reads: “Every insurance contract shall provide that the policy shall be incontestable after it has been in force during the lifetime of the insured for a period of 2 years from its date of issue except for nonpayment of premiums and except, at the option of the insurer, as to provisions relative to benefits in event of disability and as to provisions which grant additional insurance specifically against death by accident or accidental means.” That rule does not block defenses based on exclusions. Those stay available under Fla. Stat. § 627.463.
If the age or sex of the insured, or of any other individual considered in determining the premium or benefit, was misstated, the benefit becomes what the premium would have bought at the correct age or sex, calculated using the insurer’s rate at date of issue (Fla. Stat. § 627.456). Give exact ages on the application. Give exact ages on the application.
Term coverage has no cash value. FINRA notes that term coverage lasts for a limited period, while whole life offers lifetime coverage and a cash-value feature (FINRA). The Florida policy loan section does not apply to term policies (Fla. Stat. § 627.458), so there is nothing to borrow against.
What Sets the Price for a 60-Year-Old Man
The insurer’s underwriting sets the rate. It compares your application and health facts with its own rate tables.
Common rating factors include:
- Age at application and sex.
- Tobacco and nicotine use.
- Current health and medical history.
- Prescription medicines.
- Height and weight.
- Family medical history.
- Occupation and hobbies that involve physical risk.
- The term length and face amount you choose.
Health questions are required. The insurer may also ask for an exam, lab tests, or medical records. Issue depends on insurability, so the final offer can differ from an estimate.
A larger face amount generally means a larger premium. Rates differ from one insurer to another, so one number from one source tells you little.
Term Length, Age, and When Coverage Ends
Term coverage ends when the chosen term ends, unless the policy is renewed or converted under its terms.
- Many term policies keep the same level premium for the chosen term. Check your policy form for this.
- Renewal premiums are often based on your age at renewal, so they can rise sharply.
- A shorter term usually costs less each year but covers you for less time.
- A longer term costs more each year but extends protection.
Florida requires a grace period of at least 30 days for late premiums after the first (Fla. Stat. § 627.453). The policy stays in force during that grace period, but missing it can end coverage. Set up payment reminders.
Downsides of Term Life Insurance and Other Options
The main downside of term life insurance is that coverage ends and no cash value builds.
Other drawbacks to weigh:
- Renewal or conversion premiums can rise at older ages.
- Once the term ends, there is no death benefit unless you buy a new policy.
- Stopping payments does not return any cash, because the policy has none.
Whole life insurance is a different policy type. FINRA describes it as lifetime coverage with a cash-value feature. Ask to see guaranteed and non-guaranteed values side by side.
Florida requires an agent to give written information before a recommended surrender of a cash-value policy. This duty applies only when the agent recommends surrendering a cash-value annuity or life insurance policy and does not recommend using the proceeds to fund or buy another policy or annuity, and the information must include, at a minimum, any estimated surrender charge, the loss of any minimum interest rate guarantees, possible tax consequences, any forfeited death benefit, and a description of any other investment performance guarantees forfeited (Fla. Stat. § 627.4553). Florida also treats churning as unfair. That is using policy values, directly or indirectly, to buy another policy or annuity from the same insurer for the purpose of earning additional premiums, fees, commissions, or other compensation, without an objectively reasonable basis for believing it gives you an actual and demonstrable benefit (Fla. Stat. § 626.9541).
Choosing between term and whole life depends on your obligations, budget, and time horizon. A coverage review lets you compare both with the full facts.
How a Coverage Review Works, Step by Step
A coverage review moves from your goals to a decision you can sign off on. Here is the usual path.
- Share your goal, the amount you need, the term you’re considering, and who depends on the coverage.
- Complete the application and health questions. For individual policies, other than prepaid funeral contracts, group life insurance, and group or blanket accident, health, or disability insurance, the insured, having legal capacity, must apply for or consent in writing to the contract and its terms on or before entering it (Fla. Stat. § 627.404). Under Fla. Stat. § 627.404, an insurance contract on a person (other than a prepaid funeral contract, group life insurance, or group or blanket accident, health, or disability insurance) may not be carried out unless the insured person, having legal capacity to contract, applies for the contract or consents in writing to it and its terms on or before the time it is entered into. The statute makes one exception: a person with an insurable interest in the life of a minor younger than 15, or a person on whom such a minor depends for support and maintenance, may obtain a policy on the minor. The section also does not apply to any life insurance policy to which s. 624.402(8) applies.
- The insurer reviews the file and may request an exam, labs, or records. Timing varies by case.
- Review the offer and policy form before you sign. Check the premium, exclusions, renewability, and any age-based changes.
- If the offer matches your goal, the insurer issues the policy.
Your first meeting is a coverage review with the licensed agent, Nischay Rawal. Bring your questions, and we’ll walk through each step.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Why Buy Through NR CPAs & Business Advisors
NR CPAs & Business Advisors is a Miami CPA firm. It helps families, professionals, and business owners across the United States choose and buy life insurance.
The firm covers term and whole life, key person insurance, buy-sell agreement insurance, estate planning life insurance, and NRI life insurance. It serves Indian-American households and business owners.
The CPA view looks at how premiums and death benefits fit your cash flow, estate, and tax picture. The IRS states that life insurance death benefits are generally not taxable to the beneficiary, while interest earned on proceeds is taxable (IRS). Your facts decide how this applies.
Insurance is offered by Nischay Rawal, who acts as a licensed insurance agent. Florida requires agents to make that role clear when selling insurance (Fla. Stat. § 626.9531). Insurance is offered separately from the accounting practice. Florida also requires a current license and appointment for an agent (Fla. Stat. § 626.112). If an accounting firm engaged in the practice of public accounting accepts a commission for the sale of a product or service to a client, Florida requires written disclosure to the client (Fla. Stat. § 473.3205).
Our team supports the paperwork so each step stays organized.
Frequently Asked Questions About Term Life Costs
What is the average monthly cost of life insurance?
Averages vary widely by age, health, sex, term, and insurer. A coverage review for your own application is the way to get a real figure.
What are the downsides of term life insurance?
Coverage ends when the term ends, and no cash value builds. Renewal costs can rise sharply at older ages.
How much does term insurance cost?
Cost depends on underwriting, including your health, age, tobacco use, and face amount. Each insurer sets its own rates.
At what age do most people stop paying for life insurance?
Premiums stop when the term ends or the policy is cancelled or lapses. The right term usually matches the years your family or business still needs protection.
Protect Your Loved Ones: Request a Coverage Review
If you’re 60 and weighing $500,000 of term coverage to protect a spouse, a mortgage, or a business obligation, the next step is a coverage review. Request a coverage review with Nischay Rawal, the licensed agent, and bring your goals, your health history, and your questions.
Read the Quote Carefully
Term life insurance premiums depend on your age, health, sex, coverage amount, term length and the insurer. Any illustration of a 60-year-old's cost is only a general example. Health questions are required, and issue may depend on insurability. Coverage ends when the term ends, and it builds no cash value.
What Shapes the Cost of Term Life Insurance
Age at Application
Premiums generally rise as the applicant gets older, so the age at which you apply matters.
Health History
Health questions are part of the application, and your answers can affect whether and how a policy is issued.
Coverage Amount and Term Length
A larger death benefit or a longer term usually means a higher premium. Your coverage review helps match these choices to your needs.
Insurer and Policy Terms
Insurers price risk differently and set their own rules, so the policy form, renewal terms and any age-based changes should be compared carefully.


