



Key Person Insurance | Florida
Protect Your Business When a Key Person Is Lost
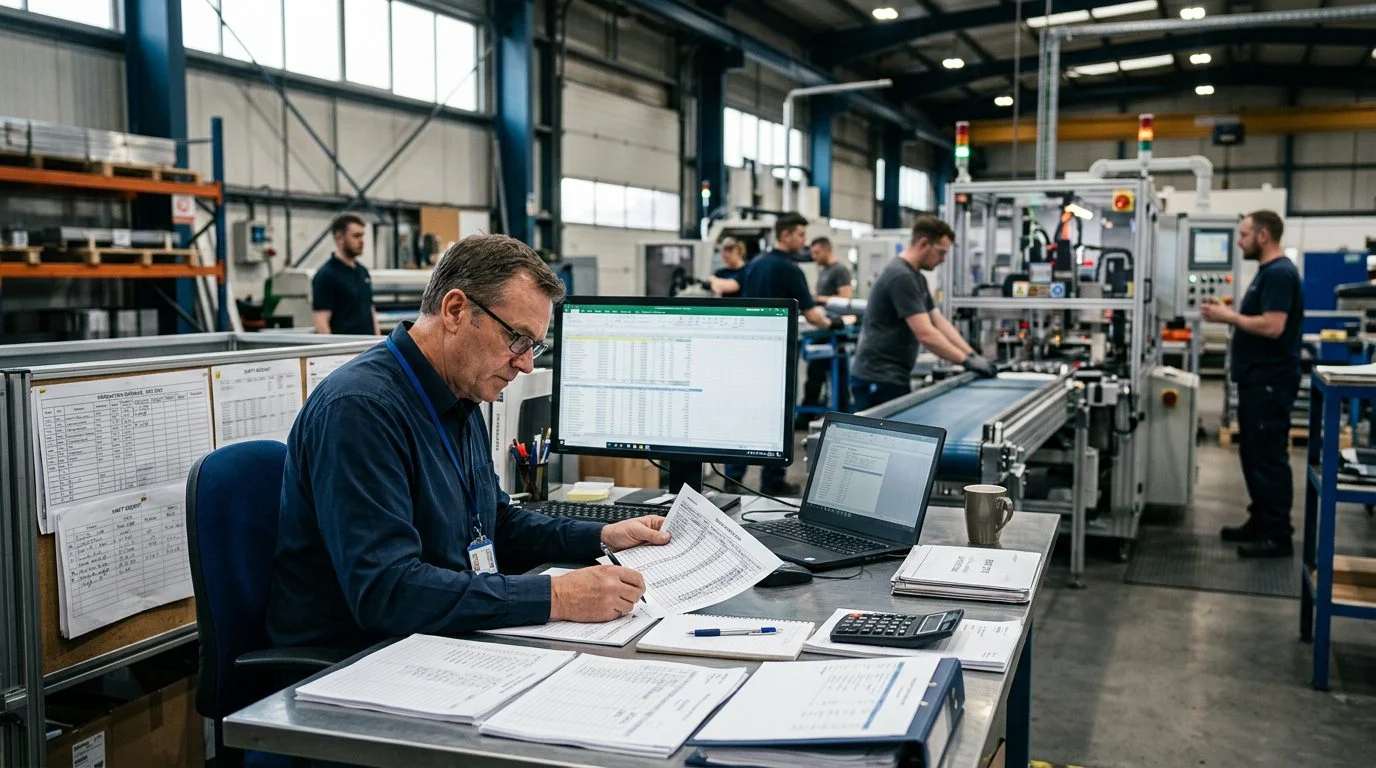
Key person insurance is designed to help a Florida business manage financial losses if a key employee dies or becomes disabled. Call NR CPAs & Business Advisors to schedule a coverage review.
By Nischay Rawal · Published October 19, 2026
Key person insurance pays a business for financial losses caused by the death or disability of a key employee. The business owns the policy and receives the benefit. The Insurance Information Institute publishes a small business owners’ guide to insurance with a page on life insurance for key employees.
This page explains what key person insurance covers, who can buy it, and how federal and Florida rules apply. NR CPAs & Business Advisors is a Miami CPA firm. Nischay Rawal is the licensed insurance agent who offers insurance, separately from the accounting practice.
What does key person insurance cover?
Key person insurance covers the financial losses a business may suffer when a key employee dies or becomes disabled. The business is the owner and the beneficiary. The money goes to the business, not directly to the employee’s family.
Florida law names who a business can insure. These include owners, directors, officers, partners, managers, and key employees, or any affiliate or subsidiary of the business, if consent is obtained in writing from the key employees or persons before the insurance is purchased. Fla. Stat. § 627.404 ties a key employee to a position or pay level described in federal tax law.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Who can a business insure?
Under Fla. Stat. § 627.404, a business entity has an insurable interest in the life, body, and health of its owners, directors, officers, partners, and managers, or of its key employees or key persons, if consent is obtained in writing from those key employees or persons before the insurance is purchased. The consent must come before the insurance is purchased.
Florida also bars the business from retaliating against a key employee who says no. A business that takes adverse action against a non-consenting employee breaks this rule.
Federal rules add their own conditions. For employer-owned contracts on key employees or key persons, IRC 6039I refers to valid consent in its annual filing requirements. Under IRC § 101, gross income does not include amounts received under a life insurance contract if such amounts are paid by reason of the death of the insured, except as otherwise provided in that section.
How do the tax rules work for key person coverage?
Premiums are generally not deductible when the business is the beneficiary. Death proceeds are generally left out of gross income. Employer-owned contracts have extra conditions.
- Premiums: No deduction is allowed for premiums on a life insurance policy if the taxpayer is directly or indirectly a beneficiary under it. Under IRC § 264, no deduction is allowed for premiums on any life insurance policy, or endowment or annuity contract, if the taxpayer is directly or indirectly a beneficiary under the policy or contract.
- Proceeds: Amounts paid by reason of death are generally excluded from gross income.
- Annual filing: A business that owns employer-owned life contracts issued after the date of enactment of this section must file a return showing details such as the number of insured employees and whether valid consent exists. See IRC § 6039I.
- Policy definition: The contract must meet the federal definition of a life insurance contract. See IRC § 7702.
How these rules apply depends on the facts of each business. A CPA’s view of the cash flow is part of that picture.
Term or whole life for a key person?
Key person coverage can use term or whole life insurance. The NAIC Life Insurance Buyer’s Guide is a consumer publication about life insurance.
Whole life insurance has cash value. Cash value is the part of a permanent policy that builds over time inside the contract. The Florida Department of Financial Services life insurance guide is a consumer guide to life insurance.
Florida’s policy-loan rule applies to policies with cash value. It does not apply to term policies or to term benefits added by riders. See Fla. Stat. § 627.458.
For federal income tax purposes, Internal Revenue Code section 264(a)(4) generally disallows a deduction for interest paid or accrued on debt taken against a life insurance policy the business owns, and section 264(e)(1) provides a narrow exception for policies covering key persons, subject to limits on the number of key persons, the amount of debt and the interest rate. Under Fla. Stat. § 627.458, the loan value of a policy must be at least equal to the cash surrender value at the end of the then-current policy year, except that the insurer may deduct from that loan value, or from the proceeds of the loan, any existing indebtedness not already deducted in determining the cash surrender value, including any interest then accrued but not due, any unpaid balance of the premium for the current policy year, and interest on the loan to the end of the current policy year.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
How do the claim rules work in Florida?
Under Fla. Stat. 627.455, every insurance contract must provide that the policy is incontestable after it has been in force during the insured’s lifetime for 2 years from its date of issue, except for nonpayment of premiums and, at the insurer’s option, as to provisions on disability benefits and provisions granting additional insurance specifically against death by accident or accidental means. Exceptions include nonpayment of premiums. See Fla. Stat. § 627.455.
Incontestability does not stop defenses based on policy exclusions or restrictions. See Fla. Stat. § 627.463.
When a policy pays a lump sum at death, the payment must include interest. Interest runs from the date the insurer receives written due proof of death. See Fla. Stat. § 627.4615.
Mistakes to avoid with key person coverage
- Skipping written consent. Florida requires it before the purchase.
- Assuming premiums are deductible. When the business is the beneficiary, the federal rule generally bars the deduction.
- Mixing key person coverage with buy-sell funding. Key person coverage protects business operations. Buy-sell agreement insurance covers a different purpose, the transfer of an owner’s share. Our buy-sell agreement insurance page covers that separately.
Frequently asked questions
What does key person insurance cover?
It covers financial losses a business may suffer when a key employee dies or becomes disabled.
Does Florida require written consent?
Yes. Florida law requires written consent from the key employee before the business buys the coverage.
Are the death proceeds taxable?
Death proceeds are generally excluded from gross income under federal law, subject to rules for employer-owned contracts.
Can a business borrow against a key person policy?
Florida’s policy-loan rule, Fla. Stat. 627.458, applies to policies that have a cash surrender value and does not apply to term policies or to term insurance benefits provided by riders or supplemental policy provisions.
How long before an insurer can contest a Florida life policy?
Under Fla. Stat. 627.455, the policy becomes incontestable after 2 years from its date of issue, during the insured’s lifetime, except for nonpayment of premiums; the insurer may also choose to except disability benefit provisions and provisions granting additional insurance specifically against accidental death from that rule.
Talk with us about your business
Key person coverage touches tax, cash flow, and employee consent. If a key employee’s role matters to your company, NR CPAs & Business Advisors can help you think through whether this coverage fits. To arrange a coverage review with Nischay Rawal, contact our firm.
What Key Person Coverage Addresses
Losses from a key person's death
A business may lose revenue, customers or momentum when an owner or key employee passes away. Key person coverage is intended to help offset those financial losses.
Losses from a key person's disability
When a critical team member can no longer work, the business may face lost income and added costs. Coverage can be structured to address these financial effects.
A CPA's view of cash flow
Our team looks at how a policy premium and any proceeds fit within your business's cash flow and tax picture, so the coverage decision is made with the full financial context.
Coverage review with a licensed agent
Nischay Rawal, a licensed insurance agent, reviews your business, your key people and your goals with you before any coverage is considered.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Why Business Owners Work With Us
Focused on business insurance
We handle key person insurance, buy-sell agreement insurance and related life insurance coverage for business owners.
Serving Indian-American households and business owners
We help families, professionals and business owners across the United States, including Indian-American households and business owners.
Tax and cash flow in view
Our CPA perspective helps you see how coverage fits into your business plans and financial statements.
Serving Florida from Miami
Based in Miami, we work with business owners in Fort Lauderdale, West Palm Beach, Orlando, Tampa and Jacksonville.
Important Disclosure
Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors. Key person insurance policies have limitations and exclusions, and issue may depend on insurability. Please ask us to explain these terms before you decide.


