



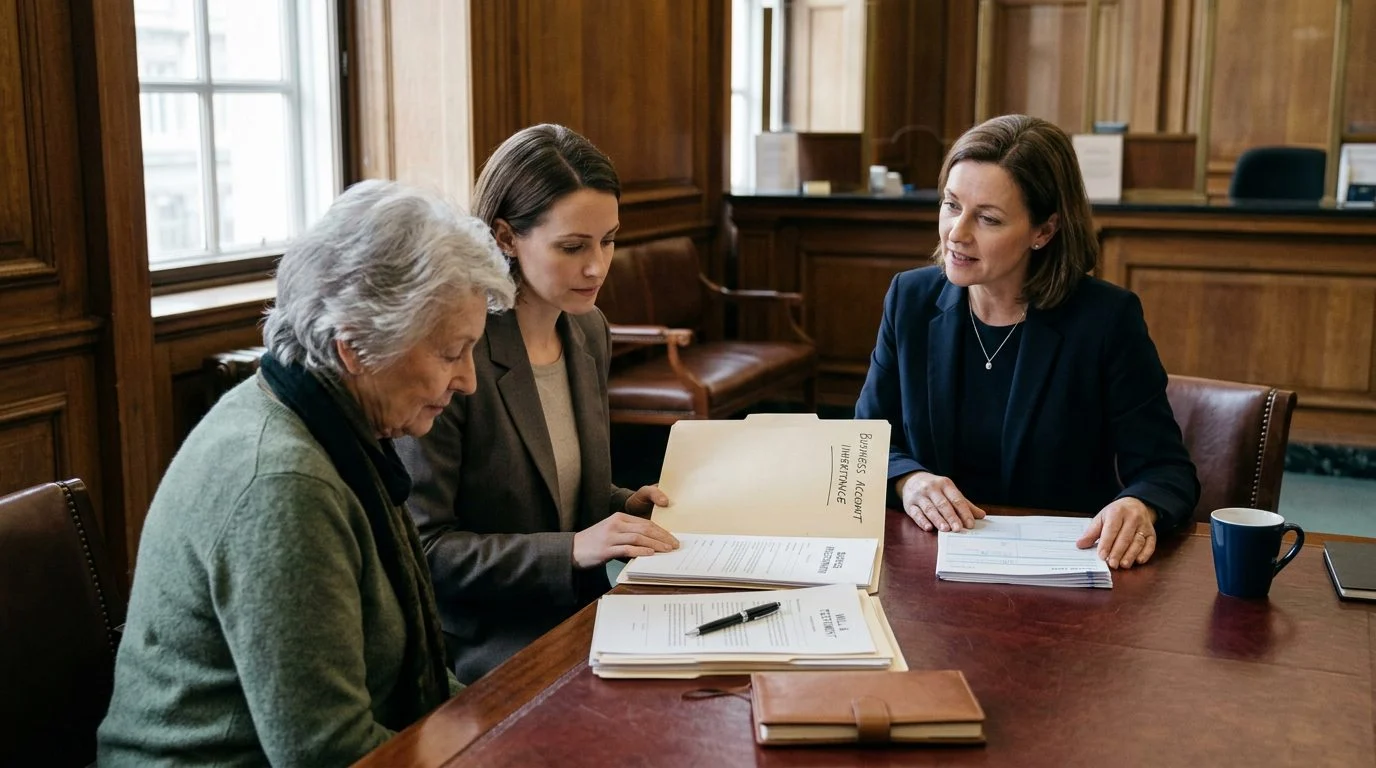
Business Succession Planning
What Happens to a Business Account When the Owner Dies?
Without proper planning, your business accounts may face delays, taxes, and probate. Life insurance and estate planning may help address some of these concerns, though how they work depends on your specific policy, documents, and personal circumstances.
By Nischay Rawal · Published October 05, 2026
When a business owner dies, their bank account does not always pass to heirs or continue operating. Instead, the account may be frozen, may enter the probate process, and may become part of the owner’s taxable estate, depending on how the account is titled and the owner’s situation. Without proper planning, this can leave the business without operating capital, employees unpaid, and family members facing unexpected tax bills and debt claims.
Business Accounts and the Probate Process
Probate is the court process that validates a will, identifies heirs, and distributes assets according to the will or state law. According to federal tax law, the gross estate of a decedent includes the value of all property, real or personal, tangible or intangible, at the time of death.
When the bank is notified of the owner’s death, the account is typically frozen or restricted. The executor or administrator of the estate must provide a death certificate and court documents to access the account. During this time, the business may struggle without operating capital to pay employees, suppliers, or rent.
Probate timelines vary by state but often take months or longer. In Florida and other states, the probate process can delay access to business funds for a period of months or longer. This delay can be devastating for a business that depends on regular cash flow.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Can a DBA Account Have a Beneficiary?
A DBA (doing business as) account is held in the owner’s personal name, so it does not automatically pass to a named beneficiary the way some personal bank accounts do. Unlike savings or checking accounts that can have payable-on-death (POD) designations, business accounts typically do not offer this option.
The account holder’s will or state intestacy law determines who receives the funds. Without a clear designation in a will or trust, the account becomes part of the probate estate. This means the court, not the owner’s family, decides how the money is distributed.
What Happens to the Company When the Owner of a Sole Proprietorship Dies?
A sole proprietorship has no separate legal existence from its owner. When the owner dies, the business does not continue automatically. The business assets, including the business bank account, become part of the owner’s personal estate.
Creditors of the business may make claims against the estate for unpaid invoices, loans, or other debts. The law allows deductions from the gross estate for funeral expenses, administration expenses, claims against the estate, and unpaid mortgages or indebtedness on property included in the gross estate. This means business debts reduce the amount available to heirs.
Without a succession plan or buy-sell agreement, the business may cease operations or be liquidated to pay debts and taxes. Family members or heirs may wish to continue the business but face delays and complications during probate. Customers may take their business elsewhere, employees may find new jobs, and valuable contracts may be lost.
What Happens to a Bank Account When Someone Dies?
When the bank learns of the owner’s death, the business bank account is frozen or restricted. The executor or administrator must provide a death certificate and court documents to access the account. Funds may then be used to pay final expenses, business debts, taxes, and estate administration costs.
Any remaining balance is distributed according to the will or state law. If there are joint account holders, they may have rights to the account depending on how it was titled.
The timing of this process varies from one situation to another.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
What Happens When Your Business Partner Dies?
If the business is a partnership or LLC with multiple owners, the deceased partner’s interest passes to their estate. Without a buy-sell agreement, the surviving partners may be forced into an unwanted partnership with the deceased’s heirs.
The business may face operational disruption, loss of credit, or difficulty obtaining financing. Banks and suppliers may hesitate to work with a business during this uncertain transition.
A buy-sell agreement funded by life insurance allows the surviving partners to purchase the deceased’s interest and continue the business. When the partner dies, the life insurance death benefit may be paid directly to the business or surviving partners, subject to the policy terms, underwriting, approval, and the individual circumstances. This can provide liquidity to help keep the business running.
Key-person insurance protects the business from financial loss when a critical owner or partner dies. Depending on the policy terms, underwriting, and approval, the death benefit may be used to help cover the cost of hiring and training a replacement, paying off business debts, or allowing the remaining owners to buy out the deceased’s stake.
How Estate Planning and Insurance Protect Your Business Account
A clear will or trust can direct how business accounts are handled and who manages them during probate. This reduces delays and gives heirs clarity about the owner’s wishes.
Life insurance proceeds may provide cash to help cover business debts, taxes, and operating expenses, depending on the policy and the claim process. Unlike the business bank account, which may be frozen during probate, life insurance death benefits may be paid directly to named beneficiaries, subject to the policy terms, and payment timing and tax treatment depend on the policy, the claim process, and the individual’s circumstances.
Proper titling of accounts and designation of successors can reduce probate costs and delays. Some business owners use revocable trusts to hold business assets, which can pass outside of probate to named beneficiaries.
For closely held businesses, the tax rules offer additional flexibility. Federal law allows an executor to elect installment payment of estate tax attributable to a closely held business interest, if the statutory conditions are met. This may help the business keep operating while the estate pays the tax over time, if the statutory conditions are met.
Why Business Owners Should Plan Ahead
Without a plan, a business account may be frozen for months, leaving employees unpaid and creditors waiting. Family members may face unexpected tax bills or business debts they did not anticipate. The business may lose customers, contracts, or key relationships during the transition.
Life insurance and a written succession plan may help address these risks. Talking with us about your current protection can help you understand what your business may need.
FAQ
Can a DBA account pass directly to heirs without probate?
No. A DBA account is held in the owner’s personal name and enters probate unless it is held in a trust or has a payable-on-death designation—and most business accounts do not offer that option.
How long does it take to access a business account after the owner dies?
The timing varies depending on each situation.
Can life insurance help protect a business account?
Yes. Life insurance may provide cash that can help cover business debts, operating expenses, and estate taxes while the probate process is underway; the timing of any payment depends on the insurer’s claim process and the terms of the policy. Because estate tax treatment depends on your situation, ask us how it applies to you.
What is a buy-sell agreement?
A buy-sell agreement is a contract between business owners that specifies what happens to a deceased owner’s stake. When funded by life insurance, it can help surviving owners purchase the deceased’s interest without depleting the business account.
Do I need key-person insurance for my business?
Key-person insurance protects the business from financial loss when a critical owner, partner, or employee dies. It can cover hiring and training costs, pay off debts, or provide funds to keep the business operating during the transition.
If you own a business or manage one after an unexpected loss, the fate of your accounts and cash flow during a transition matters deeply. Understanding how probate, taxes, and insurance work together can mean the difference between a business that survives and one that fails. Reach out to discuss your situation and explore how life insurance and estate planning can protect both your business and your family’s financial security.
Most business accounts do not pass automatically to heirs
A DBA account held in the owner's personal name enters probate unless it is held in a trust or has a payable-on-death designation. This can freeze assets, delay access for months, and create tax complications for your family and business.
How life insurance fits into business succession
Key-Person Insurance
Protects your business if a critical owner or manager dies. The policy proceeds help cover lost income, debt, and the cost of finding and training a replacement.
Buy-Sell Agreement Insurance
Funds the purchase of a deceased owner's share, ensuring a smooth transition and preventing disputes among surviving owners or heirs.
Estate Planning Life Insurance
Can provide liquidity that may help pay estate taxes and probate costs, depending on the policy and your individual circumstances.
Term and Whole Life Coverage
Ensures your family is protected if something happens to you, and can be structured to work alongside your business succession plan.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Why business owners choose NR CPAs & Business Advisors
CPA perspective on taxes and cash flow
Tax and cash flow guidance from our CPAs
Our CPA services address the tax and business finance questions that can relate to your planning, separate from any insurance products.
Insurance considerations for different business structures
Whether you're a sole proprietor, partnership, or corporation, we can discuss how insurance may fit with your business and estate plan.
Planning that connects insurance to succession
We help you look at how life insurance may support your loved ones and your business, depending on the policy, the contract and your individual circumstances.
Protect your business and your family
Related practice areas
- Key Person Insurance for Business Owners: Protect Your Company’s Future


