



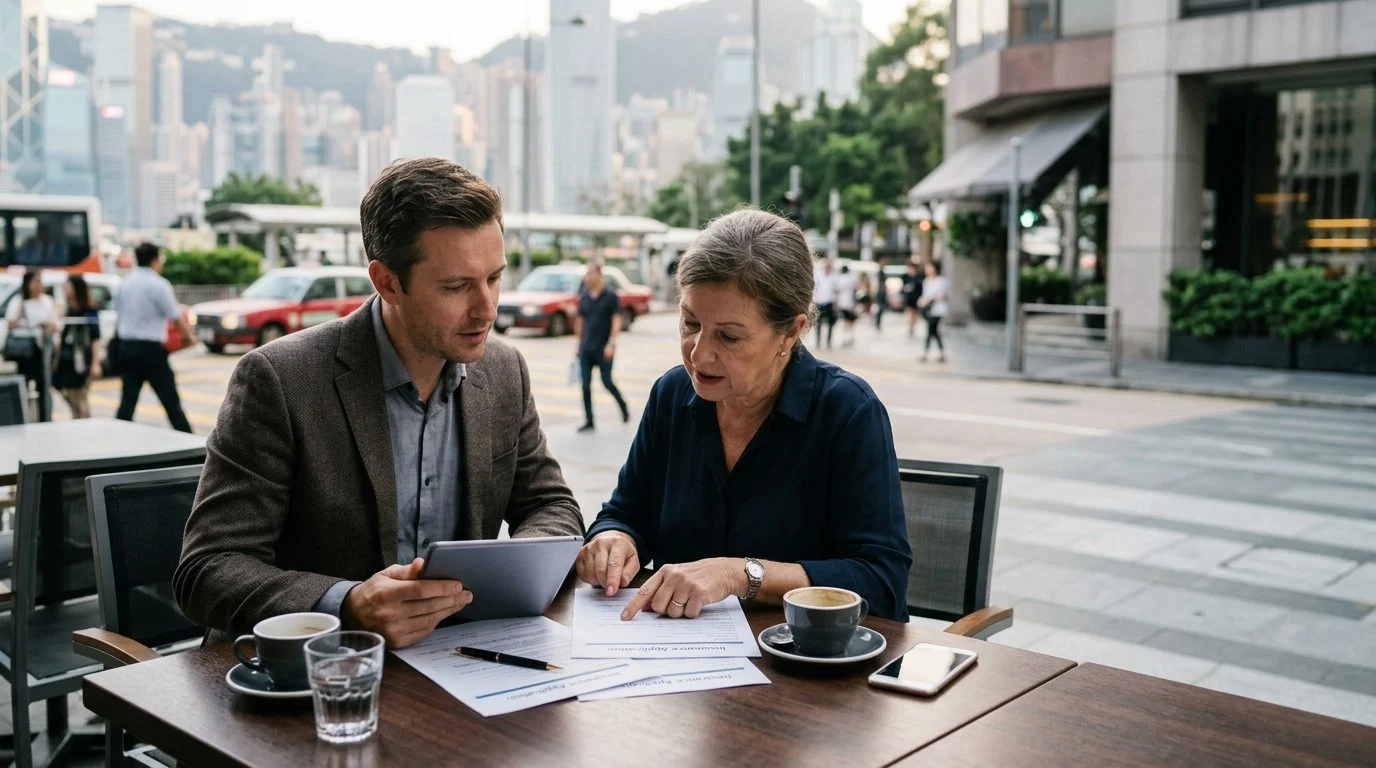
NRI Life Insurance | Florida
Protect Loved Ones Living Abroad With the Right Life Insurance
Family members, business partners and beneficiaries overseas can affect how a policy is set up. Learn the questions to ask before you buy, with a CPA's view of tax and cash flow.
By Nischay Rawal · Published October 26, 2026
Often, yes. Many insurers will issue life insurance on a person who lives in another country. Each insurer decides case by case, based on four questions: where the insured lives, whether the insured is insurable, who owns the policy, and whether the owner has an insurable interest. This page explains each one from a CPA firm’s point of view.
The Short Answer: Often Yes, but Residence and Insurability Decide It
Coverage on someone abroad is usually possible when the owner has a real reason to insure that person. The insurer must also be willing to underwrite the risk. The answer depends on the facts, so each part matters.
- Where the insured lives. Residence affects which insurers will accept the case and what they ask.
- Insurability. The insured’s health, habits and travel are reviewed before a policy is issued.
- Who owns the policy. The owner applies for the policy, pays the premiums and controls the contract.
- Insurable interest. The owner needs a legally recognized reason to insure the other person’s life.
Business owners often ask similar questions when the insured is a key employee, and it is worth discussing how the policy is structured with a licensed insurance agent before coverage is bought. Our key person insurance page covers the wider framework for business-owned coverage.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Insurable Interest: Who Can Own a Policy on Someone Abroad
The owner needs a real relationship with the insured. Under Fla. Stat. § 627.404, a policy on another person’s life must make its benefits payable to the insured, the insured’s personal representatives, or a person who had an insurable interest in the insured when the contract was made. A policy on another person’s life must pay the benefit to the insured or his or her personal representatives, or to someone with an insurable interest when the contract is made.
Two relationships cover most family cases. The second is an expectation of a substantial financial advantage from the other person’s continued life. If that person dies, is injured or becomes disabled, the owner must face a substantial financial loss. A parent who supports an adult child abroad may fit this test.
The interest must exist when the contract is made. The statute says it need not exist after coverage starts. That matters when a family’s situation changes later.
Business rules are more specific. A business can insure a key employee or key person, meaning someone whose position or compensation is described in s. 101(j)(2)(A)(ii) of the Internal Revenue Code, if that person gives written consent before the policy is bought. The business may not retaliate against someone who says no. The Insurance Information Institute explains that key person life insurance compensates a business for losses caused by a key employee’s death or disability.
How Living Abroad Affects Underwriting and Issue
Living overseas can change how an insurer reviews an application. It does not remove the review. Insurers look at the insured’s health, lifestyle, travel and residence history. Expect questions about where the insured lives and how long they have lived there.
Some insurers may ask for overseas medical records, translated documents or an exam arranged in the insured’s country. Whether they do, and how, depends on the insurer and the policy. Ask early so you know what to gather.
A fully underwritten policy asks health questions. Issue may depend on insurability. Answer every question accurately and completely, including questions about immigration or visa status. Incomplete answers can cause problems later.
Age matters too. Fla. Stat. § 627.456 says that if the insured’s age or sex was misstated, the payable amount is what the premium would have bought at the correct age or sex. Get the birth date right on the application. The same person may be insurable under one policy and not another.
Owner, Beneficiary and How a Claim Is Paid Across Borders
The owner, the insured and the beneficiary can each live in a different country. Each role needs its own review. The owner controls the policy. The insured is the person whose life is covered. The beneficiary receives the death benefit.
Florida law offers some protection. Fla. Stat. § 222.13 says that when a Florida resident dies leaving life insurance, the insurance benefits the person designated in the policy, unless the insurance is payable to the insured or the insured’s estate or to the insured’s executors, administrators, or assigns, in which case the proceeds become part of the insured’s estate. The proceeds are exempt from the insured’s creditors unless the policy or a valid assignment says otherwise, but if the insurance is payable to the insured, the insured’s estate, or the insured’s executors, administrators, or assigns, the proceeds become part of the insured’s estate and are administered by the personal representative under the probate laws.
If a policy pays a lump sum at death, Fla. Stat. § 627.4615 requires interest at an annual rate equal to or greater than the Moody’s Corporate Bond Yield Average-Monthly Average Corporate as of the day the claim was received, from the date the insurer receives written due proof of death; if that index’s calculation method has been substantially changed from its January 1, 1993 method, the rate must be at least 8 percent.
A claim usually needs a certified death certificate, claim forms and identity documents. Documents issued abroad may need certified copies or translations. Ask the insurer how it will pay, in what currency, and how money reaches a bank overseas. The beneficiary’s home country may have its own rules on receiving proceeds. Our team can check them with you when you call us.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Premiums, Payments and Cancelling a Policy From Abroad
Each insurer sets premiums based on the insured’s age, health and the policy type. Premiums can be paid from another country, but the payment method matters. Confirm the currency and any bank fees before the first payment.
Every policy must give time to pay. Fla. Stat. § 627.453 requires a grace period of not less than 30 days for any premium after the first. The policy stays in force during that period. The insurer may charge interest of up to 8 percent per year. A payment missed past the grace period can lead to a lapse.
The NAIC Life Insurance Buyer’s Guide explains the difference between term and permanent life insurance. The Florida DFS life insurance guide covers cash value and policy loans. Term policies generally do not build cash value. Whole life policies may.
Cancelling a policy returns a different amount depending on the policy type and how long it has been in force. Ask the insurer for the figures in writing. Dividends on participating whole life policies are not guaranteed.
Tax and Estate Considerations a CPA Would Check First
Life insurance paid by reason of death is generally excluded from a U.S. beneficiary’s gross income. Estate tax rules look at who owned the policy, though.
Under IRC § 2035, a transfer made within three years of death may, in some cases, bring a policy back into the gross estate.
For 2026, the basic exclusion amount for estate and gift tax is $15,000,000. Estate planning life insurance is built around these rules. Ownership choices should be checked before the policy is issued. A beneficiary’s country may tax the proceeds differently, so coordinate a cross-border tax review early.
This section is general information. Insurance is offered by the licensed agent, separately from the accounting practice of NR CPAs & Business Advisors.
Next Step: A Coverage Review for Your Family or Business
The first step is a coverage review, a meeting to look at your facts before any policy is chosen. Bring the details that shape the answer. Gather the insured’s country and residence history, visa or immigration status, and health history. List the owner, insured and beneficiary. Note the reason for coverage and any buy-sell or business agreements. For key employees, confirm written consent.
Common questions
Can a beneficiary live in another country?
Yes. Ask the insurer what it needs to identify and pay the beneficiary.
Does a policy pay out if the insured dies abroad?
Payment depends on the policy terms and the documents the insurer receives.
Are the proceeds taxable?
Generally, a beneficiary does not include them in gross income under 26 U.S.C. § 101, except as otherwise provided in paragraphs (2) and (3), subsection (d), subsection (f), and subsection (j).
Nischay Rawal is a licensed insurance agent and the responsible agent for this page. If a family member abroad or a business partner is part of your decision, contact NR CPAs & Business Advisors to start a coverage review.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
How We Help Families and Business Owners
Built for cross-border families
We work with Indian-American households, NRIs and families with relatives in other countries, across the United States.
Policy and paperwork review
We walk through the policy terms, the forms the insurer requires and the information needed to identify and pay a beneficiary abroad.
A CPA's view of tax and cash flow
Premium payments and the tax treatment of proceeds can affect your planning. We review these with you alongside the coverage.
Coverage for many needs
We help with whole life, term life, key person, buy-sell agreement and estate planning life insurance, as well as NRI life insurance.
Before You Buy
Whether a claim is paid depends on the policy terms and the documents the insurer receives. Ask the insurer in writing what it needs from a beneficiary or family member living outside the country.
Common Questions We Review
Beneficiary living abroad
Ask the insurer what it needs to identify and pay the beneficiary, and how payment would be made from another country.
Insured living abroad
Discuss how residence outside the United States may affect the application, the underwriting process and the documents needed later.
Documents and records
Keep current contact details, beneficiary information and policy records where your family can find them.
Tax and cash flow
We look at premium payments and the possible tax treatment of proceeds, so the coverage fits your broader financial picture.
Talk With Us About Protecting Your Loved Ones
Related practice areas
- Key Person Insurance for a Staffing Agency: Protecting Placement Revenue When the Owner Leaves
- Key Person Insurance for a Real Estate Brokerage Owner: Coverage Review


