



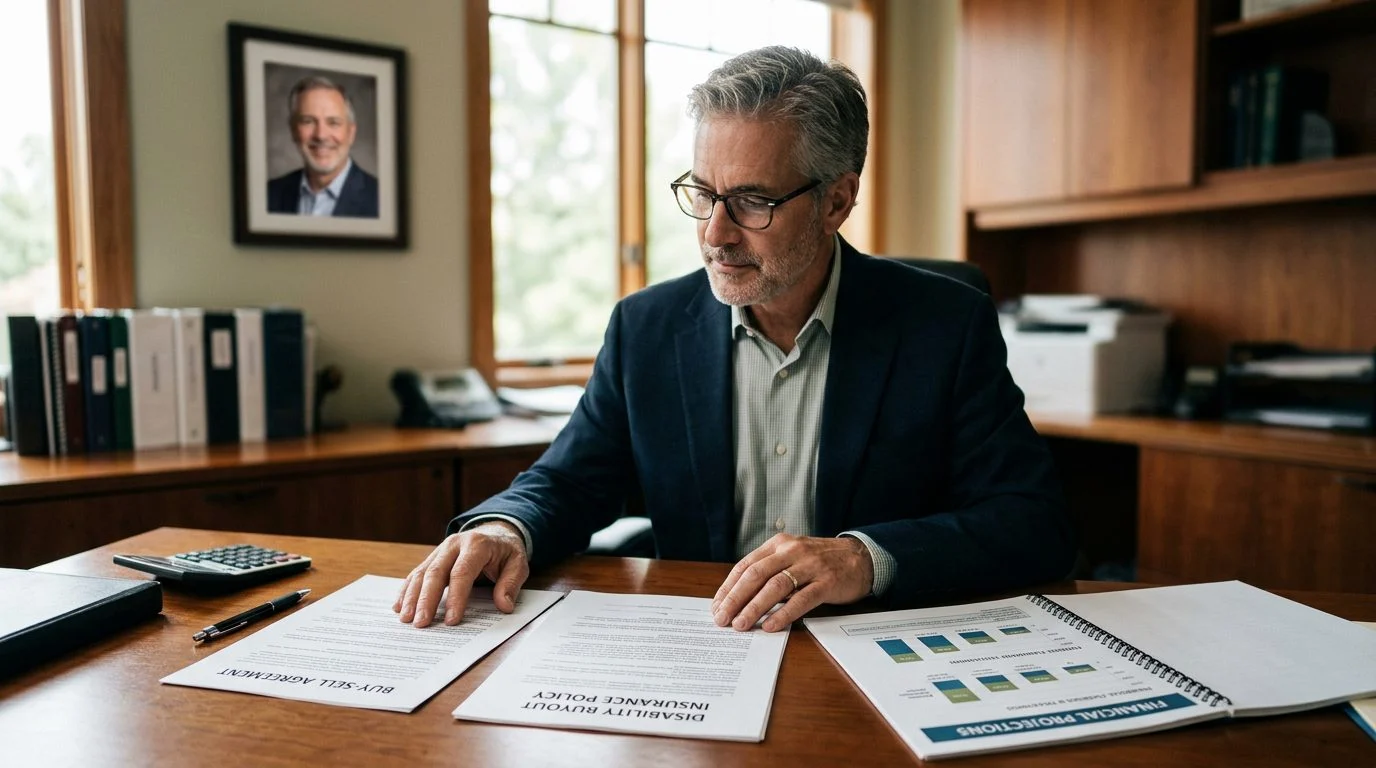
Buy-Sell Agreement Insurance | Miami and Florida
Plan for a Partner's Disability Before It Happens
By Nischay Rawal · Published October 29, 2026
Disability buyout insurance for business partners provides the money to buy out a partner’s ownership interest after that partner becomes disabled. It works best when a written buy-sell agreement spells out the buyout terms. This page explains how the policy and the agreement fit together, what to review, and how to start a coverage review. NR CPAs & Business Advisors is a Miami CPA firm that helps families, professionals and business owners across the United States, including Indian-American households and business owners, choose and buy life insurance.
What Disability Buy-Out Insurance Is and Who It Is For
Disability buy-out insurance is a policy that provides funds to buy a partner’s ownership interest after that partner becomes disabled. It ties to a written buy-sell agreement, which sets who buys, at what price, and when.
A disabled owner often still owns part of the business. The other owners may need cash to buy that share. The disabled owner may need a fair payment for it. The policy is meant to close that gap.
It typically fits closely held businesses with two or more owners. Partnerships and professional practices are common examples, especially where each owner’s work drives the income. Owners who run a practice together should look at this early, before a health event forces a decision.
Florida partnership law leaves the partnership agreement in charge of relations among partners. The statute fills in only where the agreement is silent Fla. Stat. § 620.8103.

Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What the Policy Covers and the Key Terms to Understand
The policy pays a benefit. The buy-sell agreement decides how that benefit is used to fund the buyout.
- Benefit amount. The benefit should match the buyout price in the agreement. Valuation matters. Federal estate tax rules define the value of a business interest as the net amount a willing purchaser would pay a willing seller, based on all relevant factors, including a fair appraisal of the business’s assets (including goodwill) and its demonstrated earning capacity 26 C.F.R. § 20.2031-3.
- Disability definition. The policy’s disability definition and the agreement’s disability trigger must line up. If they differ, a claim may pay under one and not the other.
- Elimination and benefit periods. The elimination period is the wait before benefits start. The benefit period is how long benefits last. If the wait is long, the partners may need cash on hand to cover the gap.
- Cross purchase or entity purchase. In a cross purchase, each partner owns a policy on the others and buys directly. In an entity purchase, the business owns the policy and buys the interest. Who owns the policy decides who receives the benefit.
- Wait-and-see agreement. This structure delays the choice of buyer until a disability occurs. It adds flexibility, but the price and funding still need planning.
How Disability Buy-Out Insurance Works, Step by Step
The process moves from a written agreement to a completed transfer of the disabled partner’s interest, in four steps.
- Set up the agreement. Write the ownership terms, the valuation method, and a clear disability definition.
- Obtain the policy. The insurer reviews the insured’s health history, so answer every question accurately. Insurability affects whether the policy issues and on what terms. Florida law says a contract on a person, other than a prepaid funeral contract, group life insurance, or group or blanket accident, health, or disability insurance, may not be carried out unless the insured applies for or consents to it in writing on or before entering the contract Fla. Stat. § 627.404.
- Meet the disability trigger. Both the agreement’s definition and the policy’s terms must be met. The claim review confirms it.
- Complete the buyout. Give written notice, agree on the price, pay, and transfer the interest. Then update the documents. In a Florida partnership, when a partner is dissociated without dissolution and no agreement is reached within 120 days after a written demand, the partnership pays the dissociated partner its estimated buyout price in cash, reduced by offsets, plus accrued interest Fla. Stat. § 620.8701.
Default rules matter. Under Florida law, an individual partner is dissociated from a partnership upon several events, including death, the appointment of a guardian or general conservator for the partner, or a judicial determination that the partner has otherwise become incapable of performing the partner’s duties under the partnership agreement Fla. Stat. § 620.8601. That is why the agreement should define disability clearly. How long the process takes depends on the waiting period, the claim review, and the notice terms.
Funding the Buyout: Disability Insurance Compared With Life Insurance
Life insurance pays when the insured dies. Disability buyout coverage responds when a partner is disabled and still alive.
A disabled partner may keep an ownership interest for a long time. Without funding, the buyout can stall, and the business may struggle to pay the agreed price.
Key person insurance is a related tool. The Insurance Information Institute explains that key person life or disability insurance compensates a business for financial losses caused by an employee’s death or disability.
Many partners use both types. Disability coverage can fund a buyout during a disability, and life coverage can fund one at death. The right mix depends on the agreement and the business’s cash flow.
Life insurance can also affect estate tax. Under federal law, insurance on a decedent’s life counts in the gross estate to the extent receivable by the executor, and also when the decedent held incidents of ownership at death for amounts receivable by other beneficiaries IRC § 2042. IRC § 2042 reads: “For purposes of the preceding sentence, the term “incident of ownership” includes a reversionary interest (whether arising by the express terms of the policy or other instrument or by operation of law) only if the value of such reversionary interest exceeded 5 percent of the value of the policy immediately before the death of the decedent.”
The policy’s form decides what is paid and when. Read the form and the agreement together, not a general summary.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Limitations and Points to Review Before You Rely on It
A buyout policy pays only what its terms allow. Check the limits before you count on the funds.
- Exclusions and health questions. The policy may exclude certain conditions or limit coverage based on health history.
- Benefit caps. The benefit may be lower than the agreed buyout price.
- Benefit period. Benefits may stop before the agreement’s payment duty ends.
- Agreement drift. An agreement not updated after a change in ownership, valuation, or partner roles can stop matching the policy.
- Contestability. Florida law requires insurance contracts to become incontestable after they have been in force during the insured’s lifetime for 2 years from issue. Exceptions include nonpayment and, at the insurer’s option, disability benefit provisions Fla. Stat. § 627.455. Check those disability terms closely.
- Tax and cash flow. How premiums and benefits are taxed depends on who owns the policy and how the buyout is structured. We review these questions alongside the business’s cash flow.
- Questions to ask. The NAIC Life Insurance Buyer’s Guide covers the questions to ask before buying life coverage.
How NR CPAs & Business Advisors Approaches This Coverage
NR CPAs & Business Advisors is a Miami CPA firm that reviews disability buyout funding alongside the business’s cash flow and tax picture.
- Licensed agent. Insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the accounting practice.
- CPA view. We look at how the buyout would be funded, whether cash flow would hold up, and how the entity structure affects the result.
- Commission disclosure. Florida law bars a CPA firm from accepting or paying a commission or referral fee in connection with the sale or referral of public accounting services, and requires a firm engaged in public accounting that accepts a commission for selling a product or service to a client to disclose it to the client in writing Fla. Stat. § 473.3205. We disclose any commission in writing before any engagement.
- No inducements. We do not offer rebates or other inducements to buy coverage.
- Our process. We review the buy-sell agreement, the policy in place, and the business’s cash flow before making any recommendation.
- NRI life insurance. The firm also offers NRI life insurance for Indian-American families and owners.
Frequently Asked Questions
What is a business disability buyout policy?
It provides funds to buy out a partner’s ownership interest after that partner becomes disabled. It works with a buy-sell agreement.
Which contract lets the remaining partners buy out a disabled partner’s interest?
A buy-sell agreement does. It sets the buyout price, the disability definition, and the notice steps.
What is one limitation of disability buyout insurance?
Exclusions and benefit caps can leave the funds short of the agreed price.
Does the policy pay if the partner is disabled but has not died?
It can, when the policy’s disability terms are met. The agreement’s disability trigger should match those terms.
Can a business buy insurance on a partner?
Florida law allows a business to have an insurable interest in its owners, if written consent is obtained before the purchase Fla. Stat. § 627.404.
Does the firm charge for a coverage review?
Any fees and costs for a coverage review are explained in writing before you decide to go further.
If a partner’s disability has you weighing the buyout terms now, you don’t have to sort them out alone. Contact NR CPAs & Business Advisors to request a coverage review of your buy-sell agreement and the policy in place.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
How disability buyout planning works for your business
Start with the buy-sell agreement
The buy-sell agreement sets the buyout price, the definition of disability, and the notice steps. The insurance is designed to match those terms.
Match the policy to the agreement
Coverage should reflect the agreed buyout amount and timing so the funds are available when the agreement calls for them.
Review the tax and cash flow effects
Our CPA perspective helps you see how premiums, ownership changes and business cash flow fit together.
Protect the people who depend on the business
A clear plan can help keep the business steady for remaining partners, employees and the families who rely on it.
Review your buy-sell agreement first
Disability buyout insurance works with your buy-sell agreement. Coverage that does not match the agreement's terms may not fund the buyout the way the partners intended.
Key parts of a disability buyout plan
Buy-sell agreement
The contract among owners that sets the buyout price, the disability definition and the steps for giving notice.
Coverage review
A coverage review with our team covers your agreement, your ownership structure and how the policy would be funded.


