



Life insurance for Florida families
Should Your Parents Have Life Insurance? Start With the Right Questions
Coverage on an older parent can support family plans, but ownership, consent and tax details shape the result. Here is how a CPA firm approaches the decision.
By Nischay Rawal · Published November 20, 2026
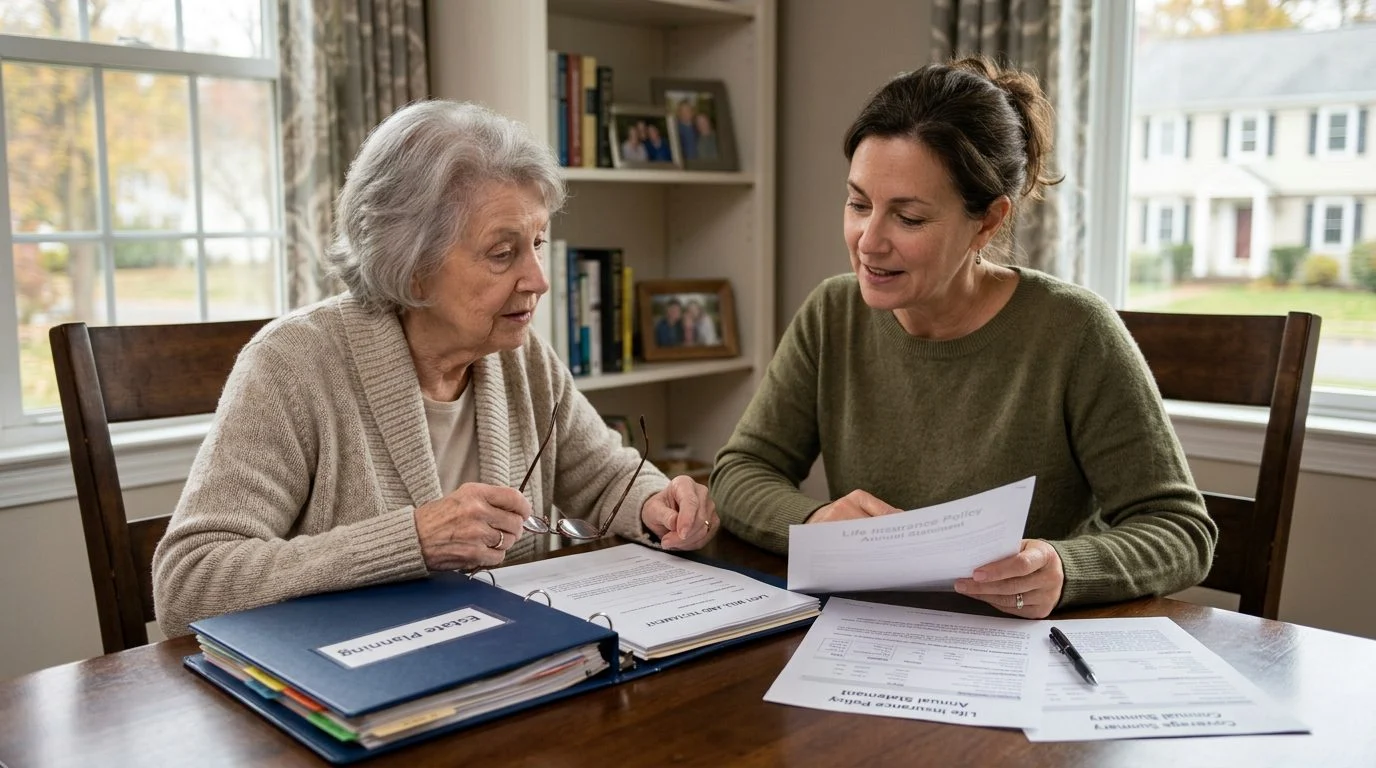
If a parent’s health has changed recently, you may be asking whether they still need life insurance. For many families, the answer is yes when a death would leave final costs, debts or a spouse’s income without support.
Whether a policy fits depends on the parent’s age, health and who would own it. This page covers the questions to answer first. It doesn’t pick a policy for your parent. NR CPAs & Business Advisors is a Miami CPA firm; life insurance for families, professionals and business owners is offered through Nischay Rawal, a licensed life and health insurance agent in Florida, separately from the firm’s accounting practice.
Why adult children ask this question
Most adult children ask this question after a change, such as a diagnosis, a hospital stay, a retirement, or a parent with no coverage at all. The worry is usually simple: who would pay the final costs if something happened?
Families often guess at the answer. A guess can miss a mortgage, a credit card balance or a spouse who depends on one paycheck. Writing down what is owed and who relies on income is a better start.
You may be researching this for someone else. Many adult children begin here before they talk with a parent about money, and that’s a normal first step. You don’t have to decide anything today.
Parents often read these pages too, and the same questions apply to them. Use the sections below to sort what you know from what you still need to learn.
If a recent change in your parent's health has your family wondering what their death would cost, our team can set up a coverage review with the licensed agent, Nischay Rawal. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What a policy on a parent is meant to cover
A policy on a parent usually exists to pay a specific need after death. Common needs include final expenses, outstanding debts and income a surviving spouse relies on. Some families also use coverage to help pay estate costs.
Three terms appear in nearly every policy. The face amount is the death benefit the policy pays. The beneficiary is the person or entity that receives it. The premium is the amount paid to keep the policy in force.
A need can exist even when no policy is in place. Whether a policy is the right tool depends on the family’s assets, income and debts. Compare the list of what would be owed with what the family already has.
Who should own the policy and who should be the beneficiary
The owner controls the policy, the insured is the person whose life is covered, and the beneficiary receives the death benefit. These can be three different people, or one person can fill two roles.
Florida law limits who can buy coverage on another person. A person of legal capacity may buy a policy on his or her own life for the benefit of anyone. Buying on another person’s life requires that the benefits be payable to that person, or to someone with an insurable interest when the contract is made. In plain words, an insurable interest generally means the buyer would suffer a substantial financial loss if that person died.
The same statute requires the insured to apply for or consent in writing before the contract is carried out. Your parent should know about the policy and sign the consent.
Ownership also matters for taxes. For federal estate tax purposes, life insurance proceeds are generally included in the insured person’s gross estate if the insured held any incidents of ownership in the policy at death (such as the right to change the beneficiary, borrow against the policy or surrender it) or if the proceeds are payable to the insured’s estate (Internal Revenue Code § 2042), and a policy the insured transferred within three years of death is generally brought back into the estate (Internal Revenue Code § 2035). Review ownership and beneficiary choices again whenever the family’s circumstances change.
Whole life and term: how each fits an older parent
Whole life insurance covers the insured for life and has a cash-value feature. Term life insurance covers a limited period. FINRA That difference drives most of the choice for an older parent.
A whole life policy can build cash value, and the insured may be able to take a policy loan. Whole life premiums are generally higher than term premiums for the same face amount.
If a policy pays dividends, those dividends are not guaranteed. Keep guaranteed values and non-guaranteed values separate when you review a policy.
A policy is not an investment, a savings plan or a promise of returns. Using the values of an existing life insurance policy or annuity contract to buy another policy or annuity contract from the same insurer, for the purpose of earning additional premiums, fees, commissions, or other compensation and without an objectively reasonable basis for believing it will provide an actual and demonstrable benefit to the policyholder, is churning. Florida law treats churning as an unfair practice. Fla. Stat. § 626.9541
Health questions, age and how price can change
A fully underwritten policy asks health questions, and issue may depend on insurability. Some policies sold with simpler questions offer graded or limited benefits in the early years. Health history can still matter for issue and for claims under those policies.
Age matters in two ways. Fla. Stat. § 627.455 reads: “Every insurance contract shall provide that the policy shall be incontestable after it has been in force during the lifetime of the insured for a period of 2 years from its date of issue except for nonpayment of premiums and except, at the option of the insurer, as to provisions relative to benefits in event of disability and as to provisions which grant additional insurance specifically against death by accident or accidental means.” Policy exclusions can still apply after that period. Fla. Stat. § 627.463
Premium changes, renewal and cancellation terms come from the specific policy. Ask how each works at your parent’s age and health. The figures for your parent depend on the facts.
Estate planning and NRI family situations
Estate planning life insurance can give an estate cash for taxes, debts or equal inheritances. The result depends on what the estate holds. For a Florida resident who dies, proceeds are exempt from the insured’s creditors unless the policy or a valid assignment provides otherwise. Proceeds payable to the insured’s estate become part of that estate. Fla. Stat. § 222.13
For federal estate and gift tax, the IRS states the basic exclusion amount for 2026 is $15,000,000. IRS Rev. Proc. 2025-32 The IRS also explains that life insurance death benefits are generally excluded from gross income, while interest paid on proceeds is taxed. IRS life insurance FAQ
Indian-American families often have a parent in India or a child abroad. NRI life insurance is designed for families with members living abroad. Florida’s consent and insurable interest rules still apply to a Florida policy. Paperwork can include consent and identity documents, and requirements vary by insurer, so allow extra time. NR CPAs & Business Advisors offers a CPA’s view of tax and cash flow as context only. That view does not promise any tax result.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Key takeaways and a coverage review
Before choosing, answer five questions:
- Why does the family need coverage?
- Who will own the policy, and who will receive the benefit?
- Does whole life or term fit the length of need?
- How do health and age affect issue and price?
- Do estate or cross-border needs change the plan?
Can I buy life insurance on my parent?
Florida law allows it when the benefits are payable to your parent or to someone with an insurable interest when the contract is made. Your parent must also consent in writing. Fla. Stat. § 627.404
Is life insurance paid to a beneficiary taxable?
Death benefits are generally not included in gross income, but interest the insurer pays on proceeds can be taxable. IRS life insurance FAQ
Is whole life or term better for an older parent?
Term covers a set period, while whole life covers the insured’s life and includes cash value. The right choice follows the length of coverage the family needs.
If a recent change in your parent’s health has your family wondering what their death would cost, a coverage review is a practical next step. You can request one through our contact page.
Life insurance is offered through Nischay Rawal, a licensed life and health insurance agent in Florida (license G066337, NPN 22274975), separately from the accounting services of NR CPAs & Business Advisors.
What we look at together
Ownership and beneficiaries
Who owns the policy, who is named to receive the benefit, and how those choices fit the family's wishes.
Tax and cash flow
How premiums, policy values and a future payout may affect household budgets and estate plans, reviewed with a CPA's view.
Fit with the broader plan
How a policy works alongside existing coverage, estate documents and business interests such as buy-sell or key person arrangements.
Review details before you apply
Ownership, beneficiary designations and your parent's written consent should be reviewed with your licensed agent before any application is submitted. Life insurance is offered through Nischay Rawal, a licensed life and health insurance agent in Florida (license G066337, NPN 22274975), separately from the accounting services of NR CPAs & Business Advisors.
Common types of coverage we discuss
Whole life insurance
Permanent coverage with cash value components. Dividends, where offered, are not guaranteed.
Term life insurance
Coverage for a set period of years, designed for a defined need such as a mortgage or family support.
Estate planning life insurance
Coverage coordinated with wills, trusts and the transfer of assets to heirs.


