Does Ford F150 Qualify for Section 179 and When Does It Apply?

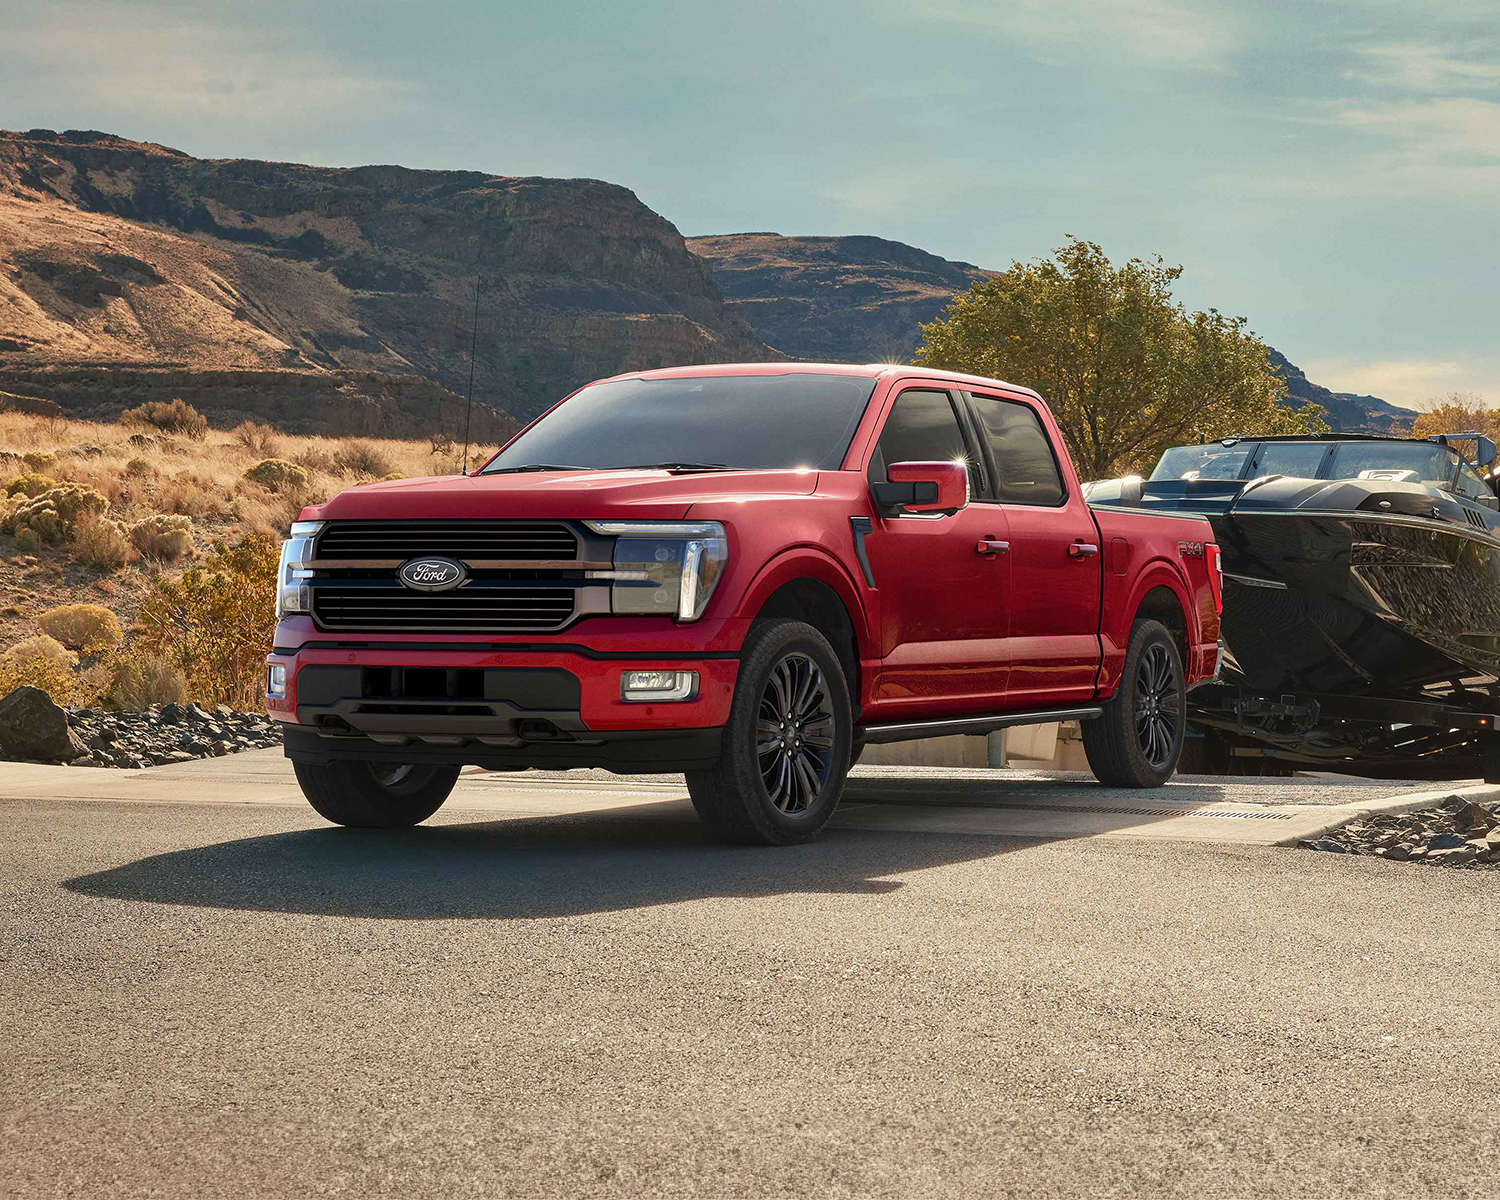
A Ford F-150 qualifies for Section 179 when its gross vehicle weight rating exceeds 6,000 pounds and the truck is used more than 50% for business, which describes most F-150 configurations on the road. Qualifying and being fully deductible are two separate questions. An F-150 with a cargo bed shorter than six feet is treated as a sport utility vehicle under the tax code and carries a $32,000 Section 179 ceiling for 2026, while the same truck with a 6.5-foot or 8-foot bed carries no such ceiling.
The sections below cover the 2026 dollar limits, where the F-150 lands on the weight threshold by configuration, why bed length changes the answer more than weight does, how bonus depreciation closes the gap left by the SUV cap, how the Raptor and Lightning are treated, which Ford SUVs qualify, the business-use and ownership requirements, when the deduction actually applies, and how the election gets made on your return.
Key Takeaways
- Most F-150 configurations exceed 6,000 pounds GVWR, with ratings running roughly 6,010 to 7,050 pounds depending on cab, bed, and powertrain.
- Bed length, not weight, determines whether the $32,000 heavy SUV cap applies. A cargo bed of at least six feet removes the cap entirely.
- The 2026 Section 179 maximum is $2,560,000, phasing out dollar for dollar once total qualifying purchases pass $4,090,000.
- The SuperCrew with a 5.5-foot bed, the highest-volume F-150 configuration, falls under the SUV cap. So do the Raptor and the Lightning, which are built on that same short bed.
- The cap limits Section 179 only. Bonus depreciation at 100% covers the remaining basis in 2026, so a capped truck can still reach a full first-year deduction.
- Business use must exceed 50% in the year the truck is placed in service, and dropping to 50% or below in a later year triggers recapture as ordinary income.
- No universal rule requires the title to be in the business name. The answer depends on your entity type.
Does a Ford F-150 Qualify for Section 179?
A Ford F-150 qualifies for Section 179 in nearly every configuration Ford currently builds, because the truck clears the 6,000-pound gross vehicle weight rating threshold that governs vehicle eligibility. Weight is the entry test, and the F-150 passes it comfortably across the lineup.
Passing the entry test settles less than most buyers expect. The tax code contains a second test that applies after the weight test, and that second test splits the F-150 lineup down the middle. Configurations with a cargo bed of at least six feet receive the full Section 179 treatment. Configurations with a shorter bed are reclassified and capped, even though the truck is identical in weight, price, and work capability.
The distinction is worth several tens of thousands of dollars in first-year deduction on a single purchase, and it is decided by a specification most buyers select for cab room rather than tax outcome. Deliberate tax planning before the order is placed is what keeps that decision from being made by accident.
What Is the Section 179 Deduction?
Section 179 is the provision of the Internal Revenue Code that lets a business deduct the full cost of qualifying equipment in the year it is placed in service, rather than depreciating that cost across several years. Vehicles, machinery, computers, and off-the-shelf software all fall inside the definition of qualifying property.
Immediate expensing changes cash flow rather than total deduction. A truck depreciated under standard rules produces deductions across five or six tax years. The same truck expensed under Section 179 produces the entire deduction now, which reduces the current year's tax bill and leaves the cash in the business instead of with the Treasury.
The provision became far more generous in 2025. The One Big Beautiful Bill Act raised the Section 179 baseline to $2.5 million permanently for tax years beginning after December 31, 2024, replacing a limit that had sat near $1.16 million. Guidance published before that change still circulates widely, which is why figures from 2023 and 2024 continue to appear on pages that look current.
What Is the Section 179 Limit for 2026?
The Section 179 limit for 2026 is $2,560,000, with the deduction phasing out dollar for dollar once total qualifying property placed in service exceeds $4,090,000 and disappearing entirely at $6,650,000. Those figures come from IRS Revenue Procedure 2025-32.
Phase-out rarely constrains a single truck purchase. A business placing $4.2 million of equipment in service in one year loses $110,000 of its Section 179 allowance, which affects fleets and capital-intensive operations rather than an owner buying one pickup. The limit that actually binds on a vehicle purchase is the heavy SUV cap covered further below, and the taxable income limitation covered near the end.
Is a Ford F-150 Over 6,000 lbs?
A Ford F-150 is over 6,000 pounds in most configurations, with gross vehicle weight ratings running from roughly 6,010 pounds at the light end of the lineup to about 7,050 pounds on heavier builds. The F-150 Lightning sits higher still, between roughly 6,500 and 8,250 pounds, because the battery pack adds substantial mass.
Gross vehicle weight rating measures something different from what the truck weighs on a scale. GVWR is the manufacturer's maximum rating for the vehicle fully loaded, combining curb weight, passengers, cargo, fuel, and tongue weight. A truck weighing 5,200 pounds empty can carry a 7,000-pound GVWR, and the rating rather than the curb weight is what the tax code uses.
The lightest F-150 builds sit close enough to the line that the rating deserves verification rather than assumption. A configuration coming in at 5,950 pounds falls under the passenger automobile rules entirely, where the 2026 first-year depreciation ceiling is $20,300 with bonus depreciation applied, according to IRS Revenue Procedure 2026-15.
F-150 ConfigurationTypical GVWRClears 6,000 lbs2026 Section 179 TreatmentRegular Cab, 8-foot bed6,100 to 6,800 lbsYesNo SUV cap, full expensing availableRegular Cab, 6.5-foot bed6,010 to 6,600 lbsUsuallyNo SUV cap, full expensing availableSuperCab, 8-foot bed6,500 to 7,050 lbsYesNo SUV cap, full expensing availableSuperCab, 6.5-foot bed6,300 to 6,900 lbsYesNo SUV cap, full expensing availableSuperCrew, 6.5-foot bed6,600 to 7,050 lbsYesNo SUV cap, full expensing availableSuperCrew, 5.5-foot bed6,400 to 7,000 lbsYes$32,000 SUV cap appliesRaptor (SuperCrew, 5.5-foot bed)6,200 to 6,800 lbsYes$32,000 SUV cap appliesLightning (SuperCrew, 5.5-foot bed)6,500 to 8,250 lbsYes$32,000 SUV cap applies
Sources: IRC Section 179(b)(5); IRS Revenue Procedure 2025-32 (2026 inflation adjustments); manufacturer gross vehicle weight rating data. GVWR varies by model year, powertrain, axle ratio, and equipment. Verify the rating on the specific vehicle before relying on it.
How Do You Find Your F-150's GVWR?
You find your F-150's GVWR on the certification label affixed to the driver's side door jamb, where the manufacturer prints the rating alongside the front and rear axle weight ratings. That label is the authoritative figure for tax purposes.
Three secondary sources carry the same number. The window sticker on a new truck lists it, the owner's manual reproduces it by configuration, and a dealer can pull it from the VIN. Marketing material and third-party model pages frequently round or generalize, so the door jamb label is the one to photograph and keep with your purchase records.
Does Bed Length Change the Deduction on an F-150?
Bed length changes the deduction on an F-150 more than weight does, because a cargo bed of at least six feet exempts the truck from the heavy SUV cap while a shorter bed subjects it to that cap. The exemption sits in Section 179(b)(5)(B) of the tax code.
Section 179(b)(5)(B) exempts three categories of heavy vehicle from the SUV limitation. A vehicle with an open cargo area of at least six feet in interior length that is not readily accessible from the passenger compartment is the category that covers pickups. A vehicle seating nine or more passengers behind the driver is the second. A vehicle with a fully enclosed cargo compartment and no seating behind the driver's row is the third, which is why cargo vans escape the cap.
Interior length is what the test measures, taken from the inside of the bulkhead to the inside of the closed tailgate. A 5.5-foot bed misses the threshold by six inches, and those six inches move the truck from unlimited Section 179 treatment into a capped category built for luxury sport utility vehicles.
What Is the Heavy SUV Limit for Section 179?
The heavy SUV limit for Section 179 is $32,000 per vehicle for tax years beginning in 2026, applying to vehicles rated between 6,001 and 14,000 pounds GVWR that are primarily designed to carry passengers. The cap is prorated by business-use percentage like every other vehicle deduction.
Congress created the cap two decades ago after heavy sport utility vehicles became a widely publicized expensing strategy, and it has been indexed for inflation since. The figure was $28,900 in 2023, $30,500 in 2024, $31,300 in 2025, and $32,000 in 2026. Vehicles above 14,000 pounds GVWR sit outside the cap entirely and receive commercial treatment.
Does a Ford F-150 SuperCrew Qualify for Section 179?
A Ford F-150 SuperCrew qualifies for Section 179, but the version with a 5.5-foot bed is subject to the $32,000 cap while the version with a 6.5-foot bed is not. Both trucks clear 6,000 pounds. Only one of them clears the bed-length test.
The distinction matters more than it first appears because the SuperCrew short bed is the highest-volume F-150 configuration sold. A buyer choosing the 5.5-foot bed for a shorter turning radius or a tighter parking footprint has made a tax decision without being told one was on the table. Pages published by vehicle sellers routinely list this configuration as fully eligible with no mention of the cap.
The same trap catches two halo models. The Raptor and the Lightning are both built exclusively on the SuperCrew short-bed body, which places both under the $32,000 ceiling despite the Lightning carrying one of the highest gross weight ratings in the lineup. Weight does not rescue a short bed.
Can You Write Off 100% of a 6,000 lb Vehicle?
You can write off 100% of a 6,000-pound vehicle in the first year, because bonus depreciation covers whatever basis the Section 179 cap leaves behind. The One Big Beautiful Bill Act restored bonus depreciation to 100% for qualified property acquired and placed in service after January 19, 2025.
Bonus depreciation and Section 179 are separate provisions that stack rather than compete. Section 179 is an election with a dollar limit, a phase-out, and a taxable income ceiling. Bonus depreciation applies automatically to eligible property unless you elect out, carries no dollar limit, and can create or increase a business loss. Applying them in the correct order is what produces the full first-year write-off on a capped vehicle.
The order runs as follows on a 100% business-use vehicle:
- Confirm the GVWR clears 6,000 pounds. Below that line, the passenger automobile ceilings under Section 280F govern and the stacking analysis stops.
- Determine whether the SUV cap applies. A cargo bed of at least six feet removes it. A shorter bed imposes the $32,000 ceiling for 2026.
- Apply Section 179 first. Take the full cost on an uncapped truck, or $32,000 on a capped one, subject to the taxable income limitation.
- Apply 100% bonus depreciation to the remaining basis. On a capped vehicle, this is the step that closes the gap to a full deduction.
- Depreciate anything left under MACRS. With bonus at 100%, there is generally nothing remaining at this step.
- Prorate the entire result by business-use percentage. A truck used 80% for business produces 80% of the figure the prior steps generated.
A worked illustration makes the stacking concrete. Take a $78,000 SuperCrew with a 5.5-foot bed used entirely for business. Section 179 delivers $32,000, bonus depreciation delivers the remaining $46,000, and the first-year deduction reaches the full $78,000. The identical truck with a 6.5-foot bed reaches $78,000 through Section 179 alone. Same deduction, different mechanics, and the mechanics matter because bonus depreciation availability is set by legislation that has changed repeatedly.
What Is the Difference Between Section 179 and Bonus Depreciation?
The difference between Section 179 and bonus depreciation is that Section 179 is an elective deduction with dollar caps and an income ceiling, while bonus depreciation applies automatically with no caps and can generate a net operating loss. Businesses frequently use both in the same year on the same asset.
Three practical distinctions follow from that split. Section 179 cannot push a business into a loss, because the deduction is capped at aggregate business taxable income. Bonus depreciation can. Section 179 is elected asset by asset, so you can expense one truck and depreciate another. Bonus depreciation applies to an entire class of property unless you elect out of that class. And several states allow Section 179 in some form while disallowing bonus depreciation completely, which the state section below addresses.
Bonus depreciation percentages have also moved repeatedly under recent legislation, dropping to 60% for part of 2024 before returning to 100%. The current bonus depreciation rules are what make a full first-year write-off possible on a capped vehicle, and a strategy built entirely on that provision carries more legislative exposure than one that clears under Section 179 alone.
The same stacking logic drives depreciation planning on buildings rather than vehicles, where a cost segregation study reclassifies building components into shorter recovery periods so bonus depreciation can reach them. The provisions are the same. Only the asset changes.
What Pickup Trucks Qualify for Section 179?
Pickup trucks qualify for Section 179 when they exceed 6,000 pounds GVWR and are used more than 50% for business, and they escape the $32,000 SUV cap when the cargo bed measures at least six feet. Across the Ford lineup, that produces three distinct groups.
The Super Duty range clears both tests in every configuration Ford builds. The F-250, F-350, F-450, and F-550 all carry gross weight ratings well above the threshold, and the bed options all meet or exceed six feet. Full Section 179 expensing applies up to the $2,560,000 annual limit, with no vehicle-level ceiling.
The F-150 splits by bed length, as covered above. Long-bed and 6.5-foot configurations receive full treatment while 5.5-foot configurations face the cap.
Compact and mid-size pickups sit in the third group and require verification rather than assumption. Several Ranger and Maverick configurations carry gross weight ratings below or near 6,000 pounds, which places them under the passenger automobile ceilings where the 2026 first-year limit is $20,300 with bonus depreciation applied. Contractors and restaurant owners shopping the smaller trucks for delivery and service routes frequently assume truck treatment and receive car treatment.
Does a Ford Raptor Qualify for Section 179?
A Ford Raptor qualifies for Section 179 and clears the 6,000-pound threshold comfortably, but it is subject to the $32,000 cap because it is built exclusively on the SuperCrew 5.5-foot bed platform. No long-bed Raptor exists, so no Raptor configuration escapes the cap.
Reaching a full first-year deduction on a Raptor therefore depends on bonus depreciation rather than Section 179. That distinction carries real risk exposure, since bonus depreciation sits at 100% under current law but has phased down before and could again. A truck whose deduction depends entirely on the second provision is more exposed to legislative change than one that clears on the first.
Does the F-150 Lightning Qualify for Section 179?
The F-150 Lightning qualifies for Section 179 with gross weight ratings running from roughly 6,500 to 8,250 pounds, and it is also subject to the $32,000 cap because it is only offered with a 5.5-foot bed. Battery weight raises the rating without changing the bed-length analysis.
Electric trucks carry one additional wrinkle. Any clean vehicle credit claimed on the purchase reduces the depreciable basis, which shrinks the amount available for Section 179 and bonus depreciation. Modeling the credit and the deduction together, rather than claiming each in isolation, is where the actual after-tax cost of an electric work truck gets determined.
Do Ford SUVs Qualify for Section 179?
Ford SUVs qualify for Section 179 when they exceed 6,000 pounds GVWR, and they are subject to the $32,000 cap in every case because no sport utility vehicle satisfies the six-foot cargo bed exemption. The cap is the default for this entire category rather than an exception within it.
The Expedition and Expedition MAX carry gross weight ratings comfortably above the threshold in all configurations. Both are capped at $32,000 under Section 179, with the remaining basis eligible for 100% bonus depreciation in 2026 when business use supports it.
Smaller Ford SUVs require the same verification the compact pickups do. Ratings vary by trim and powertrain, and models sitting under 6,000 pounds fall into the passenger automobile ceilings rather than the heavy vehicle rules.
Does the Ford Explorer Qualify for Section 179?
The Ford Explorer qualifies for Section 179 in configurations rated above 6,000 pounds GVWR, subject to the $32,000 heavy SUV cap. Explorer ratings sit close to the threshold and move with trim, drivetrain, and equipment, so the door jamb label decides the answer rather than the model name.
An Explorer landing above 6,000 pounds enters the heavy vehicle rules and takes $32,000 under Section 179 plus bonus depreciation on the balance. An Explorer landing below it enters the passenger automobile rules and caps at $20,300 in the first year for 2026 with bonus applied, according to IRS Revenue Procedure 2026-15. The gap between those two outcomes on the same nameplate is substantial.
Does the Ford Bronco Qualify for Section 179?
The Ford Bronco qualifies for Section 179 in configurations rated above 6,000 pounds GVWR, again subject to the $32,000 cap. Four-door Broncos in higher trims are the configurations most likely to clear the threshold, while two-door models and the smaller Bronco Sport generally do not.
Verification matters more on the Bronco than on almost any other model in the lineup, because the spread between configurations straddles the threshold rather than sitting above it. Two Broncos on the same lot can receive entirely different tax treatment.
How Much Business Use Does the IRS Require?
The IRS requires more than 50% business use in the year the vehicle is placed in service, and the deduction is reduced proportionally by the personal-use share. A truck used 70% for business produces 70% of the deduction the purchase price would otherwise support.
Business use means use in your trade or business, measured by mileage. Hauling materials to a job site counts. Driving to a client meeting counts. Commuting between your home and your regular workplace does not count, which surprises many owners and is the single most common source of an overstated business-use percentage.
Falling at exactly 50% fails the test, since the statute requires use to exceed half. A vehicle at or below that line loses the Section 179 election entirely and depreciates under the alternative depreciation system instead.
What Happens If Business Use Drops Below 50%?
If business use drops to 50% or below in a year after the deduction was claimed, Section 280F(b)(2) requires you to recapture the excess depreciation as ordinary income on that year's return. Recapture reverses the benefit rather than merely stopping it.
The recaptured amount equals the depreciation actually taken minus what straight-line depreciation would have produced over the same period. A truck expensed at $70,000 in year one and dropped to 40% business use in year three can generate a five-figure income pickup in that third year, arriving at a moment the owner is typically not expecting additional taxable income.
Two situations create this risk more than any other. A business that winds down or changes direction leaves a truck that was heavily used now sitting mostly idle. And an owner who buys a replacement work vehicle often shifts the older truck into personal or family use without recognizing that the shift has a tax consequence attached. Ongoing business consulting catches that transition before the return is filed rather than after a notice arrives.
Does the Truck Have to Be Titled in the Business Name?
The truck does not have to be titled in the business name in every case, because the correct answer depends on your entity structure rather than on a universal rule. Guidance stating otherwise appears frequently and is wrong for a large share of small business owners.
A sole proprietor filing Schedule C is the same taxpayer as the business, so a truck titled personally and used more than 50% in the business supports the deduction on that owner's return. A single-member LLC treated as a disregarded entity reaches the same result for the same reason.
Corporations and partnerships are different taxpayers from their owners, and there the title question carries weight. A vehicle titled personally but used by an S corporation is generally handled through an accountable plan reimbursement or a documented lease to the entity, rather than by the corporation claiming Section 179 on an asset it does not own. Getting this wrong on a corporate return is a documentation problem that surfaces during examination, and it is decided at the moment of entity selection rather than at the dealership.
How Does Section 179 Work for an S Corporation or Partnership?
Section 179 for an S corporation or partnership is applied at both the entity level and the owner level, with the dollar limit and the taxable income limitation tested twice. The entity elects the deduction and passes it through, and the owner then tests it again against their own limits.
Double testing produces outcomes owners rarely anticipate. An entity can pass through a Section 179 amount the owner cannot fully use in that year, because the owner's own aggregate business taxable income is lower than the passed-through figure. The unused portion carries forward at the owner level indefinitely. Basis limitations apply on top of that, since a shareholder cannot deduct beyond their stock and debt basis in the entity. Early-stage companies working through startup advisory engagements hit this constraint often, because basis is thin in the years when equipment spending is heaviest.
Does a Used or Financed F-150 Qualify?
A used F-150 qualifies for Section 179 as long as the truck is new to your business and acquired from an unrelated party, and financing the purchase does not reduce the deduction at all. Both points run contrary to widespread assumption.
The used-vehicle rule turns on novelty to the taxpayer rather than novelty to the world. A three-year-old F-150 bought from a dealer qualifies in full. The same truck acquired from a related party, inherited, or received as a gift does not, and neither does a vehicle you previously owned personally and later moved into the business.
Financing changes nothing about the deduction. A truck purchased with a loan and placed in service in December supports the same first-year deduction as a truck paid for in cash, even though almost none of the purchase price has been paid out yet. That mismatch between deduction timing and cash outlay is the single largest cash-flow advantage the provision offers, and it is a standard input in the models we build during CFO support work.
Leasing follows separate rules entirely. A true operating lease produces deductible lease payments rather than a Section 179 deduction, since you do not own the asset. A finance lease structured as a conditional sale can support the deduction, and which category a given contract falls into depends on the terms rather than on what the document is titled.
When Does the Section 179 Deduction Actually Apply?
The Section 179 deduction applies in the tax year the vehicle is placed in service, meaning the year it is ready and available for its intended business use. Purchase date and delivery date are not the operative dates. Availability is.
A truck delivered on December 28 and available for work supports a deduction on that year's return even if the first job runs in January. A truck ordered in November and delivered in February supports a deduction in the following year. For a calendar-year taxpayer the deadline is December 31, and factory order lead times make late-year planning a scheduling exercise rather than a purchasing one. Working the timing in October rather than late December is the difference, which is why year-end planning for equipment starts well before the fourth quarter.
One limitation constrains the deduction independently of timing. Section 179(b)(3) caps the deduction at your aggregate business taxable income for the year, so a business with $40,000 of taxable income cannot generate a $78,000 Section 179 deduction. The disallowed portion carries forward indefinitely to future years with income to absorb it, and bonus depreciation remains available in the meantime because it carries no equivalent income ceiling.
Does Section 179 Reduce Your State Taxes Too?
Section 179 reduces state taxes only in states that conform to the federal limits, and a significant number of states decouple by capping the deduction far below the federal amount or disallowing bonus depreciation entirely. Federal treatment and state treatment are calculated separately.
Decoupling produces a real administrative burden. A business taking a full federal deduction in a decoupled state adds back part of that amount on the state return and then depreciates the difference over the following years, which means maintaining two separate depreciation schedules for the same truck across its entire recovery period.
Florida imposes no state income tax on individuals, so a Miami business owner operating as a pass-through faces no state add-back on a truck purchase and no second depreciation schedule to maintain. Businesses operating across state lines rarely get that simplicity, and the state layer is worth pricing into the decision before the purchase rather than discovering it at filing.
How Do You Claim Section 179 on Your Tax Return?
You claim Section 179 by making the election in Part I of Form 4562, Depreciation and Amortization, filed with your return for the year the vehicle is placed in service. Part V of the same form handles listed property, which is where vehicle business-use percentage gets reported.
The election has a timing constraint worth respecting. It must be made on a timely filed original return, including extensions, for the year the property is placed in service. Bonus depreciation carries no equivalent election requirement, since it applies automatically unless you elect out.
Documentation is what holds the deduction up under examination, because a vehicle is listed property and carries a heightened substantiation standard. The record set should include the following:
- A contemporaneous mileage log recording date, destination, business purpose, and miles for each trip, kept as you go rather than reconstructed at year end.
- The purchase or financing documents showing the acquisition date, the seller, and the total cost.
- A photograph of the door jamb certification label establishing the GVWR that supported your treatment.
- Evidence of the placed-in-service date such as the delivery receipt, registration, or insurance binder.
- An annual business-use calculation reconciling total miles to business miles for every year in the recovery period, not just the first.
Reconstructed records are the recurring problem in vehicle examinations. A mileage log assembled in April from calendar entries and memory carries far less weight than one kept in the truck, and the deduction at stake on a heavy vehicle is large enough to make the difference expensive. Business owners carrying years of missing returns face a compounded version of this, since each open year needs its own substantiation, and the path forward on unfiled returns starts with rebuilding those records year by year.
Rebuilding records after the fact is always more expensive than keeping them. Coordinating the purchase timing, the configuration choice, and the documentation set before the truck is ordered is the substance of the tax strategy work we do with business owners buying equipment.
Frequently Asked Questions
What Throws Red Flags to the IRS?
What throws red flags to the IRS on a vehicle deduction is a claimed business-use percentage that is high, round, and unsupported by contemporaneous records. A return reporting 100% business use on the only vehicle a household owns invites questions the taxpayer usually cannot answer. Large first-year deductions are not themselves a flag, since Section 179 exists precisely to produce them. Weak substantiation behind the deduction is the flag. We provide IRS representation for taxpayers already holding a notice, and documentation is nearly always what resolves the issue.
What Pickup Truck Weighs Over 6,000 Pounds?
Nearly every full-size pickup truck weighs over 6,000 pounds GVWR, including the Ford F-150 and the entire Super Duty range. Half-ton trucks across the market generally start above 6,000 pounds and run to roughly 7,200 pounds depending on configuration, while three-quarter-ton and one-ton trucks clear the threshold by a wide margin. Compact and mid-size pickups are the category where the rating frequently falls below the line.
Can You Take Section 179 on a Leased F-150?
You cannot take Section 179 on a true operating lease, because the deduction requires ownership of the asset. Payments on an operating lease are deducted as they are made, prorated by business use. A finance lease structured as a conditional sale contract, where you build equity and take title at the end, is treated as a purchase and can support the deduction. The contract terms determine the classification rather than the label on the paperwork.
Do the Ford Maverick and Ranger Qualify for Section 179?
The Ford Maverick and Ranger qualify for Section 179 only in configurations rated above 6,000 pounds GVWR, and many of their configurations fall below that line. A compact or mid-size pickup under the threshold is treated as a passenger automobile, capping the 2026 first-year deduction at $20,300 with bonus depreciation applied. Both models also carry beds shorter than six feet, so configurations that do clear the weight threshold still face the $32,000 SUV cap.
Can You Claim Section 179 If Your Business Had a Loss?
You cannot claim a Section 179 deduction that exceeds your aggregate business taxable income, so a business operating at a loss cannot use the deduction in that year. The disallowed amount carries forward indefinitely until a profitable year absorbs it. Bonus depreciation works differently and can create or deepen a loss, which is why a business without current income often takes bonus depreciation on a vehicle instead of electing Section 179.
Can You Use Section 179 on More Than One Vehicle in a Year?
You can use Section 179 on as many vehicles as you place in service in a year, subject to the overall $2,560,000 limit for 2026 and to the per-vehicle SUV cap where it applies. The $32,000 ceiling is applied to each capped vehicle separately rather than to the business as a whole, so two short-bed trucks support $64,000 of Section 179 between them. Total qualifying purchases above $4,090,000 begin reducing the overall allowance dollar for dollar.
Putting It All Together
An F-150 qualifies for Section 179 in most configurations Ford builds, and the truck's weight is rarely the question that decides the outcome. Bed length is. A 6.5-foot or 8-foot bed delivers unlimited Section 179 treatment up to the 2026 ceiling of $2,560,000, while a 5.5-foot bed moves the same truck into the heavy SUV category and caps the election at $32,000, with bonus depreciation carrying the rest.
Around that central distinction sit the requirements that decide whether the deduction survives: more than 50% business use in the placed-in-service year and every year after, ownership that matches your entity structure, a placed-in-service date inside the tax year, enough business taxable income to absorb the election, and a mileage log kept in the truck rather than rebuilt in April. If you are weighing a work vehicle purchase this year, the team at NR CPAs & Business Advisors in Miami can look at the configuration and the timing before you order rather than after.
A short conversation usually settles which specification and which tax year produce the better result for your situation. You can talk it through with us, or call +1 954-231-6613.


Tax and Financial Insights
by NR CPAs & Business Advisors