



Life Insurance Basics
What Is Term Life Insurance?
Understand how term coverage works and whether it fits your family's protection needs.
By Nischay Rawal
What Exactly Is a Term Life Insurance Policy? Definition & How It Works
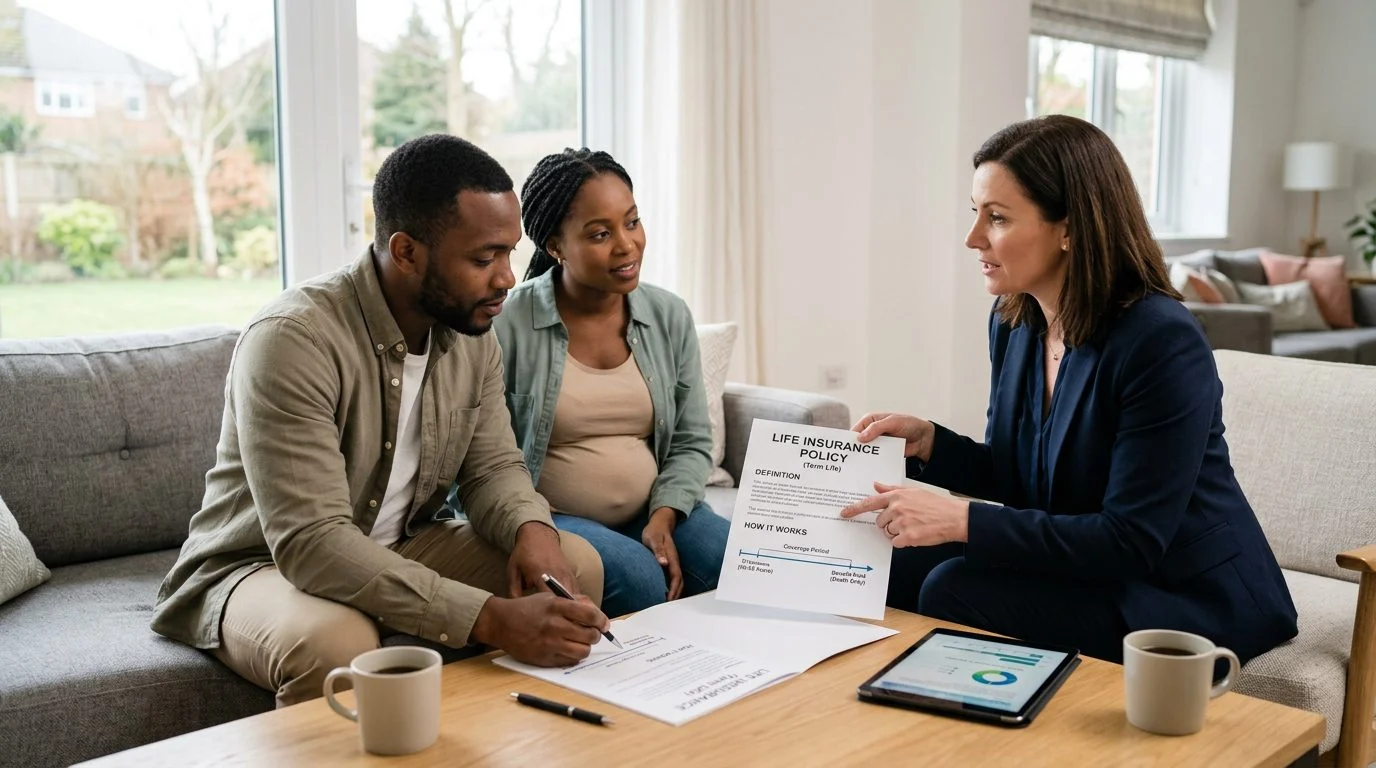
Term life insurance is a life insurance policy that pays a death benefit to your beneficiaries if you die during a set period of time—typically 10, 20, or 30 years. It’s pure insurance protection: you pay a premium each month or year, and in exchange, your family receives a lump sum if you pass away while the policy is active. Unlike some other forms of life insurance, term life has no cash value or investment component; it exists solely to provide financial protection for a defined period.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Term Life Insurance: The Basic Definition
Term life insurance provides coverage for a limited period of time, typically between 10 and 30 years, and pays a death benefit only if you die during that term. Any level-premium period depends on the specific policy and contract. You choose the coverage amount (how much your beneficiaries receive) and the term length (how long you’re protected) when you apply. The NAIC Life Insurance Buyer’s Guide is a consumer resource for people evaluating life insurance options.
Life insurance death benefits are generally excluded from gross income under federal tax law, but exceptions apply and tax treatment depends on the policy and your individual situation.
How Long Does Term Life Insurance Last?
Term life policies are sold in fixed periods: commonly 10, 20, or 30 years. You choose the term length when you buy the policy based on how long you need protection—for example, until your children finish college, until your mortgage is paid off, or until you reach retirement age.
Your premium is typically level for the level-premium period stated in your policy and contract, so your cost generally does not change year to year during that period. This stability makes budgeting predictable. The premium may stay the same at later ages only for the level-premium period stated in the specific policy and contract, so a 30-year-old with a 20-year term policy should confirm that period before relying on it.
What Happens After Your Term Ends?
When the term expires, the policy ends and coverage stops. If you are still living, you receive no payout—term life insurance only pays if you die during the active term.
At the end of the term, you may have the option to renew or convert to a permanent policy, depending on your policy’s terms. However, premiums will typically be higher because you are older and may have developed new health conditions. Some policies allow conversion to whole life insurance without requiring a new medical exam; health questions are still required, issuance depends on insurability, and the cost will reflect your age at conversion.
Do You Get Paid Out for Term Life Insurance?
A payout occurs only if you die while the policy is in force. Your beneficiaries—the people you name—may receive the death benefit if one is payable under the terms of your policy, subject to underwriting, approval, and your individual circumstances. The benefit is the coverage amount stated in your policy. If you outlive the term, there is no payout; the policy simply expires and you have paid premiums with no return.
This is the trade-off of term life insurance: coverage lasts only for a set term, and if you outlive that term, no death benefit is paid.
What Does Term Life Insurance Cover?
Term life insurance may pay a death benefit for death from illness, accident, or natural causes when the death occurs during the active term, subject to the terms and exclusions of your specific policy. The policy pays the death benefit to your named beneficiaries, who can use it for any purpose: paying off debt, covering living expenses, funding education, or other needs.
Whether a death is covered depends on the terms of your specific policy and on the death occurring while the policy is active.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
What Is the Downside to Term Life Insurance?
Term life provides no cash value or savings component—you build no equity in the policy. If you outlive the term, you have paid premiums but receive nothing back. This is fundamentally different from whole life insurance, which is life insurance that may build cash value under the contract. That cash value consists of guaranteed and non-guaranteed amounts, dividends are not guaranteed, and loans may reduce both the cash value and the death benefit.
If you need coverage beyond the original term, you may need to reapply, and whether coverage is available then depends on the policy, the insurer, and your health at that time. Premiums may be higher at that point because age and health can affect cost. Some applicants who develop serious illnesses during their first term may find it difficult or impossible to obtain coverage at renewal.
Term life is not designed to build wealth or serve as a long-term investment vehicle. It is pure protection—nothing more.
Term Life Insurance vs. Whole Life Insurance
Term life covers you for a set number of years; whole life covers you for your entire lifetime as long as premiums are paid. Term life premiums are generally lower because they cover a limited period; whole life premiums are higher, and whole life can include a cash value component that may build over time under the contract, consisting of guaranteed and non-guaranteed amounts.
Term life is pure protection; whole life is life insurance that may build cash value under the contract. The cash value in a whole life policy consists of guaranteed and non-guaranteed amounts; policy loans can reduce both the cash value and the death benefit, and terms depend on the policy. Dividends, where paid, are not guaranteed.
Term life is often chosen when you need affordable protection for a specific period, such as while raising young children or paying off a mortgage. Whole life is chosen when you want lifetime coverage and are considering a policy that may build cash value under the contract.
How Much Does Term Life Insurance Cost?
Term life insurance premiums depend on your age, health, the amount of coverage you purchase, and the length of the term. Younger, healthier applicants pay lower premiums. A 35-year-old in good health will pay significantly less than a 55-year-old for the same coverage and term length.
A longer term (30 years) typically costs more per month than a shorter term (10 years), but the per-year cost is often lower. Exact premium amounts vary by insurer and your individual circumstances. The IRS FAQ on life insurance proceeds addresses tax treatment but does not quote specific rates—because premiums are individual and change based on underwriting.
Who Should Consider Term Life Insurance?
Parents and caregivers who want to protect their family’s financial security if something happens to them are natural candidates. Business owners who want to protect their business partners or key employees through key-person insurance or buy-sell agreement coverage often use term life as part of their strategy.
Professionals and wage earners who carry debt or have dependents relying on their income should consider term life. Anyone who needs affordable, straightforward death benefit protection for a defined period—without the higher cost and complexity of permanent insurance—may find term life the right fit.
Getting Started With Term Life Insurance
The first step is to think about how much coverage your family would need and for how long. Consider your debts, your family’s living expenses, education costs, and any other financial obligations. Talking with NR CPAs & Business Advisors can help you think through the amount and term that may fit your situation.
A conversation with our team lets you explore how term life fits with your other financial goals—whether that’s protecting your family, funding a buy-sell agreement, or ensuring your business can operate if a key person passes away.
Frequently Asked Questions
What is the main advantage of term life insurance?
The main advantage is affordability: term life premiums may be lower than whole life premiums because coverage is limited to a set period, though actual premiums depend on the insurer, the policy, and your circumstances.
What happens if I’m diagnosed with an illness during my term?
Under the terms of your policy, coverage generally continues as long as premiums are paid during the stated term. At the end of the term, renewal may be difficult or more expensive, depending on your health.
How do I know how much term life insurance I need?
Talking with a CPA can help you think through your debts, income replacement, and other financial obligations as a starting point when considering how much coverage may fit your situation.
If you’re weighing whether term life fits your family’s or business’s financial picture, especially alongside tax and cash flow, you can contact NR CPAs & Business Advisors to talk through your options. Get in touch with NR CPAs & Business Advisors to explore your term life options and how they work with your overall financial plan.
How Term Life Insurance Works
You Choose a Term Length
Term life policies cover you for a set period, often 10, 20, or 30 years, though available term lengths depend on the policy and insurer. Whether your premium stays level throughout that term depends on the level-premium period stated in your specific policy and contract.
Your Beneficiaries Receive a Death Benefit
If you pass away during the term, your beneficiaries receive the policy's death benefit. The proceeds go to them as named in your policy.
Coverage Ends When the Term Ends
When the term expires, coverage stops. At that point, you can renew (usually at a higher rate), convert to permanent coverage, or let the policy end.
Term Life Premiums Compared With Whole Life
Because term coverage is temporary, premiums may cost less than whole life insurance, which is designed to cover you for your entire lifetime; actual premiums depend on the insurer, the policy, and your circumstances.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Why Families and Business Owners Choose Term Life
Straightforward Protection
Term life is simple: you pay a premium, your family is protected if something happens to you during the term.
Flexible Coverage Amounts
You select the death benefit that matches your family's needs—mortgage, education, income replacement, or business obligations.
Match Your Coverage to Your Timeline
Choose a term that aligns with when you need protection most: while children are young, while you're paying a mortgage, or while you're building your business.
Factors to Consider in Your Plan
Term length and coverage amount depend on your overall financial picture and tax situation, and our team can discuss these factors with you.
Conversion and Renewability
Many term policies allow you to convert to whole life coverage or renew your term. If you convert, the insurer will ask health questions and issue depends on your insurability at that time. Conversion terms and conditions vary by policy—this is an important detail to discuss when you're evaluating your options.
Term Life vs. Whole Life: Key Differences
Term Life Insurance
Coverage for a set period, with lengths that vary by policy and insurer. Premiums that may be lower, depending on the insurer, the policy, and your individual circumstances. No cash value. Ends when the term expires.
Coverage for your entire lifetime. Higher premiums. May build cash value under the contract, which includes both guaranteed and non-guaranteed amounts. Provides permanent protection.
When Term Makes Sense
You need affordable protection for a specific period—such as while raising children, paying a mortgage, or during key business growth years.
When Whole Life Makes Sense
You want lifelong coverage, or protection that may also support estate planning or business succession goals.
Term Life in Your Bigger Picture
Family Protection
Term life replaces your income if something happens to you, helping your family pay bills, mortgage, and education costs.
Business Continuity
Key-person term insurance protects your business if a critical team member passes away. Buy-sell term insurance funds the buyout of a departing owner's stake.
Estate Planning
Term life can be part of your estate plan, working alongside whole life or other strategies to meet your family's long-term needs.
Tax and Cash Flow Considerations
Term coverage may relate to your tax situation and overall financial planning, and tax treatment depends on the policy and your individual circumstances.


