



Miami CPA Firm | Life Insurance for Immigrant Families
Can an Immigrant Get a Life Insurance Policy? Here's How to Start
Your immigration status, visa, or length of time in the U.S. can affect which life insurance options are available. NR CPAs & Business Advisors helps families and business owners across Florida understand their choices, with a CPA's view of tax and cash flow.
By Nischay Rawal · Published October 31, 2026
Short answer: can an immigrant get a life insurance policy?
Yes, many immigrants can apply for life insurance in the United States. Immigration status is one factor an insurer reviews, but it is not the whole picture. The insurer also looks at identity, residence, age, health, and the amount of coverage requested.
Each insurer sets its own underwriting rules. One company may accept a document that another company turns down. That is why the same applicant can get different answers from different carriers.
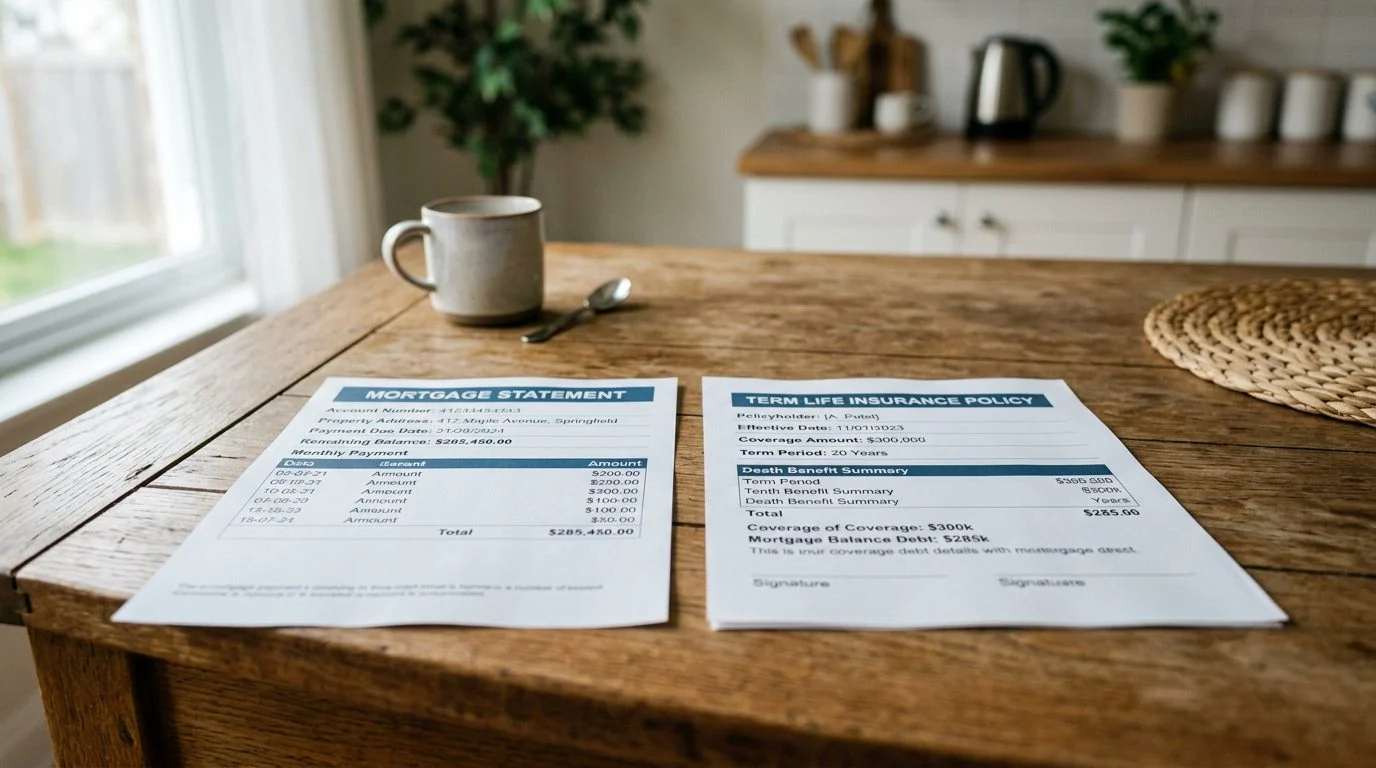
Two basic products come up in most of these questions. Term life insurance covers a set number of years. FINRA explains that term coverage is for a limited period, while whole life insurance provides lifetime coverage and includes a cash-value feature.
This page focuses on who can apply and which documents matter. It does not pick a policy design for you.
Many readers are asking on behalf of someone else. A parent may be asking about an adult child. A spouse may be asking about a partner who just received a green card or a visa. Keep that in mind as you read.
If you are gathering papers for a parent or spouse after a change in status, we can review your documents with you in a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Do you have to be a U.S. citizen to have a life insurance policy?
Citizenship is not the only test. A non-citizen applicant is reviewed on the core factors that apply to everyone, plus extra questions about residence and documents.
The application usually asks about lawful residence, identity papers, and address history. The insurer then decides whether those papers are enough for the policy it offers. Its underwriting guidelines, not a general rule, decide which documents it accepts.
Florida law also limits who can buy coverage on another person’s life. Fla. Stat. § 627.404 says any individual may buy insurance on his or her own life for the benefit of any person. A person may not buy insurance on another individual’s life unless the benefits are payable to that individual or his or her personal representatives, or to someone with an insurable interest when the contract is made.
The same statute says the proposed insured’s signature on the application counts as written consent. So a parent buying coverage for an adult child needs the child’s consent and must meet the insurable interest test.
What insurers ask non-citizen applicants
Insurers usually ask for identity papers, a taxpayer number, address history, and health information. The exact list depends on the company and the policy.
- Identity documents: a passport or government-issued photo ID, plus any paper showing the applicant’s status or permission to live in the United States.
- Taxpayer number: a Social Security number or, where the insurer accepts it, an Individual Taxpayer Identification Number (ITIN).
- Residence: the current address, past addresses, and whether the applicant lives in the United States or abroad.
- Age and coverage amount: the age on the application and the death benefit requested.
- Health questions: a fully underwritten policy involves health questions, and issue may depend on insurability.
Accuracy matters on the application.
Green card holders and permanent residents
A green card is usually the main proof of status for a lawful permanent resident. Insurers still review the application as a whole. The card helps show residence and identity, but it does not decide eligibility or the terms offered.
Ask the insurer which card or papers it accepts before you apply. Some companies may ask for a copy of both sides or for a specific date range.
If a permanent resident later moves abroad or changes address, tell the insurer. The policy file should match the applicant’s real residence. A mismatch can cause problems at claim time, when the insurer checks the file.
Florida’s contestability rule matters here too. Fla. Stat. § 627.455 requires every insurance contract to provide that the policy becomes incontestable after it has been in force during the insured’s lifetime for two years from its date of issue, with exceptions. Fla. Stat. § 627.455 reads: “Every insurance contract shall provide that the policy shall be incontestable after it has been in force during the lifetime of the insured for a period of 2 years from its date of issue except for nonpayment of premiums and except, at the option of the insurer, as to provisions relative to benefits in event of disability and as to provisions which grant additional insurance specifically against death by accident or accidental means.” Nonpayment of premiums is one exception. Accurate information on the application is still important from the start.
Visa holders and changes in status: what happens to a policy
A visa has an expiration date, and a status change can raise new questions. A visa renewal, a change of status, or a move out of the United States may each affect how the insurer views an existing policy.
Read your policy for the rules on changes. Tell the insurer about any change the policy requires you to report. Keep the policy, the insurer’s contact details, and your immigration papers together in one place.
Some term policies include a convertible option. This lets the owner change a term policy into a permanent policy within a set period. Whether that option is available, and under what terms, depends on the policy. The convertible term option is not automatic for every policy.
Florida’s grace period rule is also useful to know. A missed payment is not the same as a lapse, but the policy’s terms still control.
Can I get life insurance without a Social Security Number?
Many insurers ask for a Social Security number. Some accept an ITIN or another taxpayer identification number. Acceptance varies by insurer, so you should not assume one company’s answer applies to another.
Before you apply, ask the insurer in writing how it handles a missing Social Security number. Ask what it accepts instead. Ask whether it needs any supporting papers with the taxpayer number.
A missing Social Security number is a question to raise early. It is not a fact that ends the process by itself. The insurer decides what it will accept, and it does so under its own guidelines.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Can an undocumented person buy life insurance?
Insurers set their own rules for applicants who do not have lawful status. Acceptance of identity and residence documents differs from one company to another.
A reader in this situation should get the rules in writing before applying. Useful questions include these: What identification does the insurer accept? How does it handle a taxpayer number? How do the beneficiary and premium payment terms work?
The insurable interest rule still applies. If the policy will insure someone else, the buyer must meet the rule in Fla. Stat. § 627.404.
This section explains how the application process works. It does not predict what any insurer will decide.
NRI life insurance and families living abroad
NRI life insurance is coverage for a non-resident Indian or another person who lives outside the United States. Residence abroad changes the documents, the taxpayer number, and the insurer’s rules.
Confirm those points before you apply. An insurer may handle a foreign address, a foreign taxpayer number, or a long stay abroad in its own way. Put the questions in writing.
Indian-American households in Miami, Fort Lauderdale, West Palm Beach, Orlando, Tampa, and Jacksonville may have family in more than one country. For Florida residents, the Florida Statutes on insurance agents say a person may not act as an insurance agent unless licensed and appointed. Fla. Stat. § 626.112 reads: “(1)(a) No person may be, act as, or advertise or hold himself or herself out to be an insurance agent, insurance adjuster, or customer representative unless he or she is currently licensed by the department and appointed by an appropriate appointing entity or person.”
From a tax view, 26 U.S.C. § 101(a) says amounts paid because of the insured’s death are generally not gross income. The IRS life insurance proceeds FAQ covers the same general rule.
Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice. Florida law requires agents to clearly indicate to prospective insureds that they are acting as insurance agents with regard to insurance products and identified insurers.
Documents to gather before a coverage review
Gather these papers before you contact an insurer or meet with an agent. Most insurers ask for them.
- Identification and any paper showing lawful status
- Taxpayer number, such as a Social Security number or ITIN
- Current and past addresses, including any address abroad
- Details of the coverage amount and the beneficiaries
- Any prior policies, with the insurer’s name and policy number
Bring a short list of questions too. Ask which insurers accept your documents. Ask how a visa or status change would affect the policy. Ask how residence abroad would be handled.
Is a life insurance policy possible without a green card?
Possibly. Each insurer decides what it accepts. Ask in writing before you apply.
Does a visa expiration affect an existing policy?
It can raise questions about the policy. Read the policy’s change rules and ask the insurer how a status change would be handled.
Can a non-resident Indian buy life insurance in the United States?
Some insurers consider applicants who live abroad. The documents and taxpayer rules differ by insurer, so confirm them before applying.
If you are gathering papers for a parent, spouse, or relative after a change in status, you do not have to sort it out alone. Contact us at our contact page to arrange a coverage review of your documents and your situation.
How We Can Help
Whole Life and Term Life
We walk you through the differences between whole life insurance and term life insurance, including premiums, coverage length, and cash value, so you can compare them against your family's needs.
NRI Life Insurance
For non-resident Indians and families with ties across borders, we review how residency and status may affect the policy you are considering.
Business Coverage
We discuss key person insurance and buy-sell agreement insurance to help owners plan for the continuity of their business.
Estate Planning Coverage
We explain how life insurance can fit into an estate plan, alongside the tax and cash flow questions your CPA may already be addressing.
Ask Before You Apply
Each insurer sets its own underwriting rules, and those rules can change over time. Ask the insurer in writing how your immigration status and situation will be treated before you submit an application.
Coverage Options We Discuss
Whole Life Insurance
Permanent coverage designed to last for your lifetime, as long as premiums are paid under the policy terms.
Term Life Insurance
Coverage for a set period of years, often chosen to protect a mortgage, children's education, or other obligations.
Key Person and Buy-Sell Insurance
Policies that support business continuity when an owner or key employee passes away.
Estate Planning Life Insurance
Life insurance coordinated with your broader estate and tax planning goals.


