



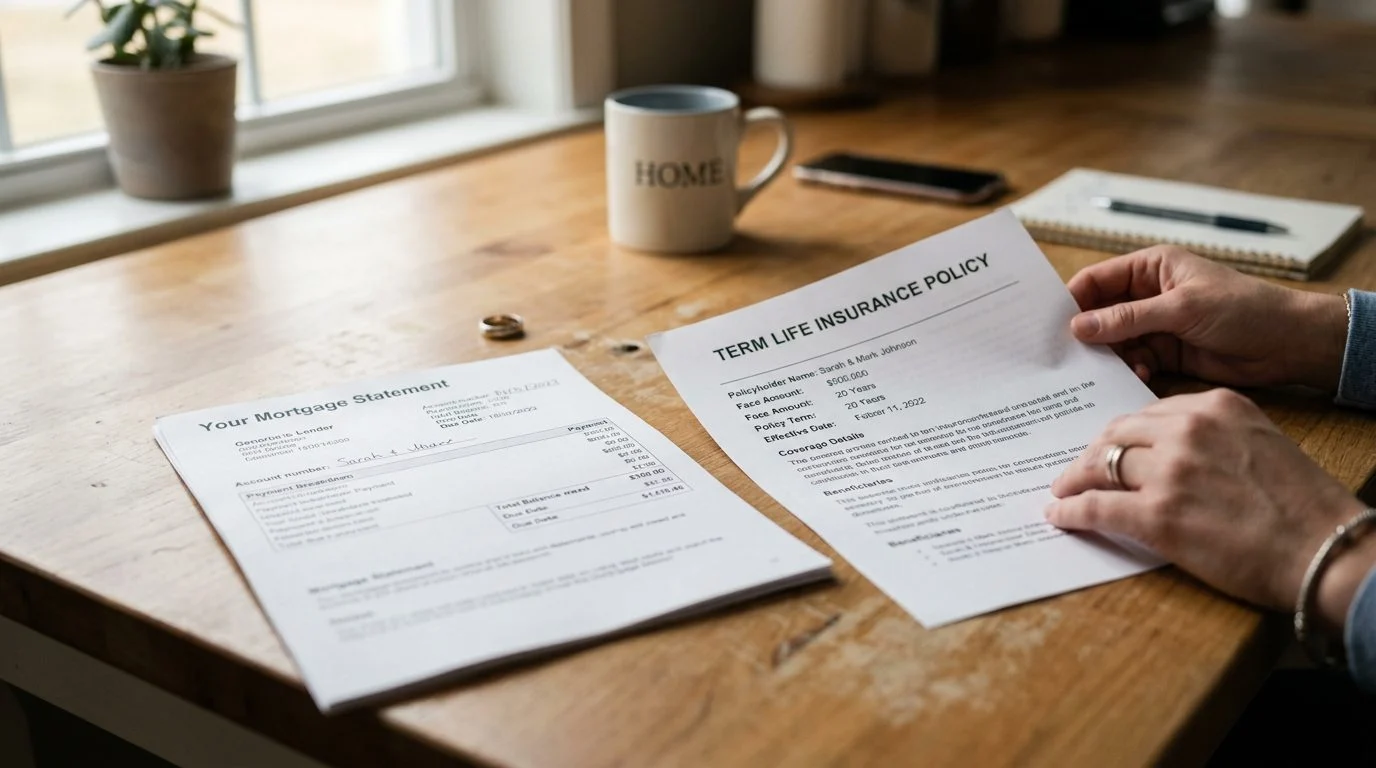
Business Life Insurance | Miami, Florida
Understand COLI before your business buys corporate-owned life insurance
Learn how a COLI policy is owned, funded and used, and what a business should review before it applies. Nischay Rawal, a licensed insurance agent, offers this coverage separately from the firm's accounting practice.
By Nischay Rawal · Published November 6, 2026
A COLI policy is life insurance that a business buys, owns and pays for. The business is also the beneficiary, and the insured person is usually an employee or owner. COLI stands for corporate-owned life insurance.
If you’re asking “What is a COLI policy?”, the short answer is this: it’s a structure. The ownership details decide how the policy is handled for tax and paperwork. This guide explains the roles, the notice rules and the points a CPA reviews.
Insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors.
What a COLI policy is, in plain words
A COLI policy is life insurance that a company owns on the life of one of its people. The company applies for the policy, pays the premiums and collects the death benefit.
You may also hear the term “company life insurance.” It usually means this same structure. It does not mean group benefits that employees join.
Compare that with a typical individual policy. The insured person usually owns the policy and names family members as beneficiaries. In a COLI policy, the roles shift to the business.
COLI is often used in businesses that want coverage tied to key people. The reason for the coverage shapes how the policy is set up and documented.
If a lender, a co-owner or your own company has asked you to review a COLI policy on an employee's life, you don't have to sort it out alone. Our team can walk through it with you in a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Who owns, insures and benefits under a COLI policy
A COLI policy has three roles. The business is the owner. The employee or owner is the insured. The business is the beneficiary.
For an employer-owned life insurance contract, certain exceptions to the income limit apply only when the notice and consent requirements are met. Before the policy is issued, the employee must be told in writing that the business intends to insure his or her life. The notice must state the maximum face amount.
The employee must also give written consent. That consent can extend to coverage that continues after employment ends.
Businesses that own these contracts also have an annual filing duty. Under IRC § 6039I, an applicable policyholder that owns one or more employer-owned life insurance contracts issued after the enactment of this section must file a return for each year those contracts are owned. The return shows the number of its employees at year-end, the number of those employees insured, the total insurance in force, and the policyholder’s name, address, taxpayer identification number and type of business. It also states that the policyholder has a valid consent for each insured employee, or, if not all consents were obtained, the number of insured employees for whom consent was not obtained.
Florida law adds its own rule. Under Fla. Stat. § 627.404, a business may insure the life, body, and health of its owners, directors, officers, partners, and managers, or of its key employees or key persons (including those of affiliates or subsidiaries), if written consent is obtained before the purchase. The business may not retaliate against a key person who refuses to consent.
How COLI differs from key person and buy-sell insurance
COLI describes who owns the policy. Key person and buy-sell coverage describe why the coverage exists.
Key person insurance protects a business from financial loss if an essential officer or owner dies. The business can own that policy. Federal tax law defines a key person, for interest-deduction purposes, as an officer or a 20-percent owner, but the number of individuals who may be treated as key persons for any taxpayer is capped, as explained in 26 U.S.C. § 264.
Buy-sell agreement insurance funds an agreed purchase of an owner’s interest at death. Under Fla. Stat. § 627.404, an individual party to a contract for the purchase or sale of an interest in a business entity has an insurable interest in the life of each other party, for that contract only.
One policy can serve more than one purpose. A business might use a COLI policy to protect against a key person’s death and to help fund an owner buyout. For that reason, the purpose and the ownership should be reviewed together.
Permanent and term designs, and how cash value is described
A COLI policy can be built as a term design or a permanent design. FINRA explains that term life insurance covers a limited period. Whole or permanent life insurance covers the insured’s lifetime and includes a cash-value feature, according to FINRA’s insurance page.
Cash value is the built-in value inside a permanent policy. It is separate from the death benefit. Guaranteed values and non-guaranteed values should be described separately. Dividends, where a policy pays them, are not guaranteed.
When you describe the product, use its generic name, such as whole life insurance policy. Don’t describe it as an investment or a retirement plan.
Policy loans work differently. Under Fla. Stat. § 627.458, a permanent policy with a cash surrender value must include a loan provision. Fla. Stat. § 627.458 reads: “The loan value of the policy shall be at least equal to the cash surrender value at the end of the then-current policy year, except that the insurer may deduct, either from such loan value or from the proceeds of the loan, any existing indebtedness not already deducted in determining such cash surrender value, including any interest then accrued but not due, any unpaid balance of the premium for the current policy year, and interest on the loan to the end of the current policy year.” The insurer may defer a loan for 6 months after application, other than for paying a premium to the insurer.
Under Fla. Stat. § 627.458(2), the policy may also provide that, if unpaid loan interest brings total debt to or above the loan value, the policy terminates, but not until at least 30 days’ notice has been mailed by the insurer to the last known address of the insured or policyowner and of any assignee of record. The loan-value provision of the statute provides that, where a policy includes it, the policy terminates only after at least 30 days’ notice has been mailed by the insurer to the last known address of the insured or policyowner and of any assignee of record at the insurer’s home office, once total indebtedness equals or exceeds the policy’s loan value.
Tax points a CPA reviews for corporate-owned coverage
Under 26 U.S.C. § 101, death benefits are generally excluded from income. The employer-owned exception is the key limit. It depends on notice and consent.
The IRS explains that life insurance proceeds may be nontaxable. Interest paid on proceeds left with the insurer is taxable, according to the IRS guidance on life insurance proceeds.
A policy must also meet federal tests to count as life insurance. Under 26 U.S.C. § 7702, a contract qualifies only if it meets the cash value accumulation test or the guideline premium and cash value corridor requirements.
Interest on policy loans for a key person has a limit. Under 26 U.S.C. § 264, an exception applies only up to $50,000 of aggregate indebtedness on policies covering that key person.
Whether a specific policy is treated a certain way depends on the facts. Tax rules can change. Each COLI policy should be reviewed against its contract and the business’s filings.
How long premiums are paid, and what to review in the policy
The premium payment length depends on the policy design and the contract schedule. Some policies are paid over a set number of years. Others are paid over the insured’s lifetime.
Review the face amount first. Then check any planned changes in face amount or premium, limitations, exclusions, renewability and age-based changes.
Loans and surrenders change the policy’s values and the death benefit. Read those provisions before any action.
Florida law also says the insurable interest need not exist after coverage begins, under Fla. Stat. § 627.404. The signed application by the proposed insured can serve as written consent.
Frequently asked questions
What does COLI stand for?
COLI stands for corporate-owned life insurance. A business owns and pays for the policy on an employee’s or owner’s life.
How many years do you pay on a life insurance policy?
It depends on the policy design and the contract schedule. Some are paid over set years, and others are paid over the insured’s lifetime.
Is a COLI death benefit taxable?
It depends on the facts, including whether the notice and consent rules were met. A CPA should review the specific policy.
Have a COLI policy question on your desk? Reach out through our contact page to set up a coverage review with our team.
How we work with business owners
Licensed insurance agent
Nischay Rawal is a licensed insurance agent. Insurance is offered through that licensed agent, separately from the firm's accounting practice.
Policy details in plain words
We explain the insured, the owner, the beneficiary, premiums, the payment period and the policy limitations so you can review each term.
Business owners and their families
We work with business owners across the United States, including Indian-American business owners and households, on business-owned coverage.
A coverage review first
Contact us to schedule a coverage review of your business, its key people and your goals before any policy is chosen.
Important: COLI is not a tax plan on its own
A COLI policy's tax treatment, cash values and costs depend on the policy design, who owns it and your business's circumstances. Review these points before you apply.
Points to review before you apply
Ownership and beneficiary
Identify who owns the policy, who is insured and who receives the death benefit, and confirm the business's reasons for each choice.
Premiums and payment period
Ask how long premiums are payable, what they cost over time, and whether the premium or face amount can change.
Cash value and loans
Non-guaranteed values, loans and withdrawals can affect the policy. Ask how each one changes the death benefit.
Insurability and limits
Health questions are required, issue may depend on insurability, and exclusions and renewal terms apply. Review them with your agent.


