



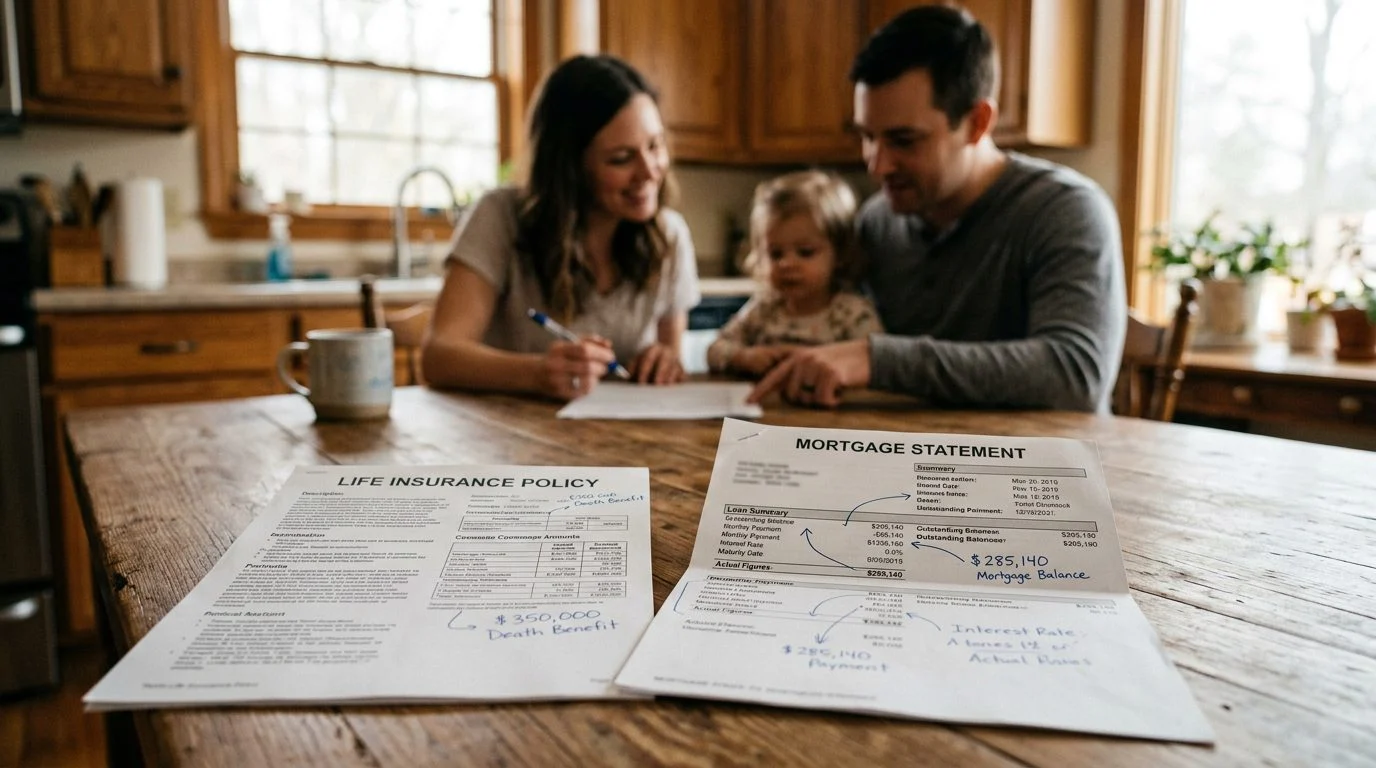
Whole Life Insurance | Miami, Florida
Know What Your Life Insurance Policy Is Worth in Cash Today
Net cash surrender value is the cash figure that matters when you review a permanent policy. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the firm's accounting practice.
By Nischay Rawal · Published November 8, 2026
What Net Cash Surrender Value Means on a Life Insurance Policy
What does net cash surrender value mean on a life insurance policy? It is the cash the policy owner would receive if they ended a permanent policy, after the insurer subtracts what it is owed. The word “net” means deductions were taken. The word “surrender” means ending the policy in exchange for its cash value.
This figure matters most when a statement lands in the mail and the number does not match what you expected. It also matters when a parent, spouse, or business partner asks whether a policy should be cancelled. This page walks through the figure step by step, using Florida rules where they apply.
If a figure on a policy statement or a question about cancelling has you stuck, you don't have to sort it out alone. Contact our team to set up a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.

What Net Cash Surrender Value Means in Plain Words
Net cash surrender value is the cash a policy owner would get by ending a permanent policy on a given date. Surrender charges, unpaid loans, and loan interest all reduce it. Only permanent policies, such as whole life insurance, build cash value to surrender. A standard term policy covers a set period and builds no cash value, so this term does not apply to it. FINRA explains that term coverage lasts a limited period, while whole or permanent coverage lasts for life and has a cash-value feature.
The payout is what the insurer pays the owner when the policy ends while the insured is alive. It is not the death benefit that beneficiaries receive after the insured dies.
Net Cash Surrender Value vs. Cash Value and Death Benefit
Net cash surrender value is smaller than cash value, and the death benefit is a separate amount. Each one goes to a different person at a different time.
| Amount | What it is | Who gets it, and when |
|---|---|---|
| Cash value | Value built up inside the policy before deductions | Stays in the policy; not paid out on its own |
| Net cash surrender value | Cash value minus what the insurer is owed | The policy owner, only if the policy is surrendered |
| Death benefit | Amount payable when the insured dies | Named beneficiaries, at the insured’s death |
Surrendering ends the policy, so the death benefit ends too. An owner cannot collect the surrender payment and the death benefit. Statements also show guaranteed and non-guaranteed figures. Read those separately, because they are not the same kind of number.
How the Net Figure Is Worked Out
The net figure starts with cash value. The insurer then subtracts surrender charges, outstanding loans, and unpaid loan interest. Surrender charges often apply in a policy’s early years and shrink over time.
Here is a hypothetical example, for illustration only: cash value of $50,000, a surrender charge of $4,000, a policy loan of $15,000, and accrued loan interest of $500. The net figure would be $30,500. Your real numbers come from your insurer’s statement, not from this example.
Dividends, where a policy pays them, are not guaranteed. A dividend-based value can change, so past dividends do not set future values. Any growth or interest illustration must show its limits with equal emphasis. Current values can differ from illustrated values.
Where to Find the Figures on Your Policy Statement
The net cash surrender value line usually sits near the cash value and loan lines on an annual or quarterly statement. Look for four items: cash value, surrender charge, loan balance with interest, and the net figure. Each one affects the bottom line.
Check whether the statement separates guaranteed values from non-guaranteed values. Guaranteed values are set by the contract. Non-guaranteed values depend on the insurer’s experience, such as dividends. Because values change, ask the insurer for a current surrender value statement instead of relying on an old one. Note the insurer’s name and the policy number, and read the statement alongside the policy contract and any riders.
What Happens When You Cancel and How Long a Payment Takes
Cancelling for cash value pays the net cash surrender value, but the death benefit ends. The payment may also be less than the premiums you paid over the years.
Surrender is not the same as lapse. Ending a cash-value policy before its maturity date in exchange for its current cash surrender value is one option; a lapse for nonpayment of premium is a separate event. Florida also requires a grace period of at least 30 days to pay a premium after the first (Fla. Stat. § 627.453).
Payment timing depends on the insurer’s forms and processing. Ask the insurer for its written timeline before you decide. Before ending a policy, review its early-termination fees, lost guarantees, possible tax effects, and any forfeited death benefit. Florida also treats churning by an insurer or agent as an unfair practice.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Taxes and Policy Loans That Change the Net Amount
Policy loans lower the net figure, and unpaid interest can grow the debt. Florida law lets the insurer deduct unpaid interest and any unpaid premium balance from the loan value or the loan proceeds (Fla. Stat. § 627.458). Fla. Stat. § 627.458 reads: “The loan value of the policy shall be at least equal to the cash surrender value at the end of the then-current policy year, except that the insurer may deduct, either from such loan value or from the proceeds of the loan, any existing indebtedness not already deducted in determining such cash surrender value, including any interest then accrued but not due, any unpaid balance of the premium for the current policy year, and interest on the loan to the end of the current policy year.” If loan interest goes unpaid, it can be added to the loan balance. Fla. Stat. § 627.458 reads: “The loan value of the policy shall be at least equal to the cash surrender value at the end of the then-current policy year, except that the insurer may deduct, either from such loan value or from the proceeds of the loan, any existing indebtedness not already deducted in determining such cash surrender value, including any interest then accrued but not due, any unpaid balance of the premium for the current policy year, and interest on the loan to the end of the current policy year.” If total debt reaches the loan value, the policy can end, but only after at least 30 days’ notice is mailed. That loan rule does not apply to term policies.
Federal rules also matter. Amounts paid under a life insurance contract because of the insured’s death are generally not included in the beneficiary’s gross income, but if the insurer holds those proceeds under an agreement to pay interest on them, the interest payments are included in gross income. Subject to certain exceptions, no deduction is allowed for interest on debt incurred or continued to buy or carry a life insurance policy under a plan that contemplates systematically borrowing part or all of the increases in the policy’s cash value. Surrender can also carry tax consequences. Tax results depend on the facts of the policy and the owner, and our CPA team can review them.
Net Cash Surrender Value on a Key Person or Business-Owned Policy
For a business-owned policy, the net figure can matter to the owners. It can come up when a buy-sell agreement is updated, a partner exits, or ownership of a key person policy changes. How the business records that value on its books is an accounting question our team can review.
Federal estate rules also look at who owned the policy. Read our key person insurance overview alongside this page.
Nischay Rawal is a licensed insurance agent. Insurance is offered by the licensed agent, separately from the accounting practice. Florida law requires agents to say they are acting as insurance agents and to identify the insurers involved (Fla. Stat. § 626.9531).
Talk Through Your Policy Statement With Our Team
To get a net figure explained, contact NR CPAs & Business Advisors for a coverage review. If a statement number, a cancellation question, or a partner’s request has you stuck, you do not have to work through it alone. Our team can review the statement, the surrender figures, and the tax and cash flow effects with you. Contact our team to get started.
Frequently Asked Questions
What does net cash surrender value mean on a life insurance policy?
It is the cash a policy owner would receive for ending a permanent policy, after the insurer subtracts charges and loans. The figure does not include the death benefit.
Does term life insurance have a net cash surrender value?
No. Term life insurance covers a set period and builds no cash value to surrender.
Can creditors reach the cash value of a life insurance policy in Florida?
Generally no. Florida law says the cash surrender values of life policies on the lives of Florida citizens or residents cannot be reached by attachment, garnishment or other legal process in favor of a creditor of the insured, unless the policy was taken out for that creditor’s benefit. The same protection applies to annuity proceeds against creditors of the annuity’s beneficiary (Fla. Stat. § 222.14).
Does a policy loan reduce the net cash surrender value?
Yes. Unpaid loans and loan interest are subtracted from the cash value when the net figure is worked out.
Why the Net Figure Matters
A plain-words definition
Net cash surrender value is the cash a policy owner would receive for ending a permanent policy, after the insurer subtracts surrender charges and any outstanding policy loans.
Separate from the death benefit
The death benefit is the amount paid to beneficiaries when the insured dies. Surrender value is a different figure and does not include it.
Why it changes over time
Cash value in a whole life insurance policy typically grows as premiums are paid, but surrender charges can reduce what is available in the early years.
A CPA's view of cash flow
Our team looks at how cash value, loans and premiums fit into your household or business budget before any decision is made.
Terms to Know Before You Review Your Policy
Surrender charges
Fees the insurer may deduct when a policy is ended, often higher in the first years the policy is in force.
Policy loans
Money borrowed from the insurer using the policy as collateral. Unpaid loans and interest reduce the net amount.
Term life insurance
Coverage for a set period. Term policies generally do not build cash value, so there is no surrender value to calculate.
Check the Net Figure Before You Act
Ending a life insurance policy, or borrowing against it, can have tax consequences and can end coverage you may need.


