



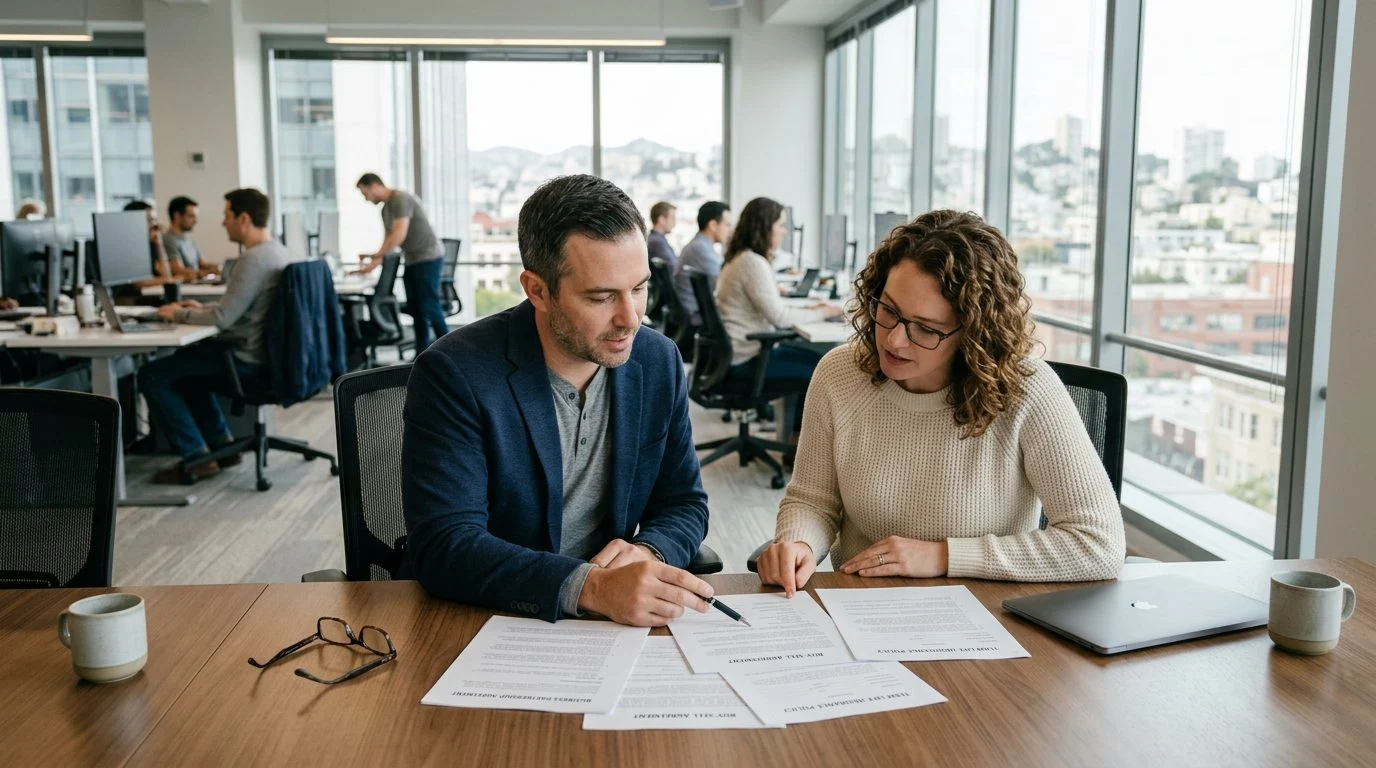
Key Person Insurance | Florida
Protecting Your Business When a Key H-1B Employee Matters Most
Learn how companies approach life insurance on an H-1B employee, and what to review with a CPA's view of tax and cash flow.
By Nischay Rawal · Published November 6, 2026
Can a company buy life insurance on an H-1B employee? Generally, yes, when the company has an insurable interest in that person’s life, which for a business covers its owners, directors, officers, partners, managers, and key employees or key persons of the business entity or affiliate or subsidiary, and the key employee or person gives written consent before the insurance is purchased. This page explains the rules for companies in Florida, including Miami, Fort Lauderdale, Orlando, and Tampa, and what H-1B workers should know.
The Short Answer: Yes, When the Company Has an Insurable Interest
Yes, a company can generally buy life insurance on a key employee when it has an insurable interest in that employee’s life and the employee’s written consent is obtained before the purchase. Florida law sets this test in plain terms. The Florida insurable interest statute gives a business an insurable interest in its key employees, but only when written consent is obtained before the purchase.
So the answer depends on the facts of each company and employee. This page covers the general rules.
If your company is unsure whether it can insure the life of an H-1B employee, our team can walk through that question in a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What Insurable Interest Means for a Business
Insurable interest means the company would suffer a real financial loss if the employee died. Under Florida law, an individual may have an insurable interest in another person if the individual expects a substantial pecuniary advantage through that person’s continued life, health, and safety, with a consequent substantial pecuniary loss by reason of that person’s death, injury, or disability; a business’s insurable interest in its key employees rests on written consent obtained before the purchase. It must also face a substantial financial loss if that person dies, is injured, or becomes disabled.
Common examples include lost profits from a role the business depends on. Other examples are the cost of recruiting and training a replacement, and loans or contract obligations tied to that person. The company should be able to describe the loss in specific facts and figures.
Businesses often use key person insurance for this purpose. The Insurance Information Institute describes key person coverage as protection against financial losses from the death or disability of a key employee. Florida’s rule also ties “key employee” to position or pay rules in federal tax law.
Does H-1B Status Change Whether the Company Can Buy the Policy?
Not by itself. H-1B status is a separate question from insurable interest. The test looks at the company’s financial loss, not the worker’s visa category.
H-1B work is tied to the employer’s petition. That makes the company’s continuing need for the worker part of the loss analysis. If the company truly depends on that role, the loss is easier to describe. If the role could be filled easily, the company’s case may be harder to support.
Two other points matter. First, federal rules for employer-owned policies define an insured as a U.S. citizen or resident. The IRC § 101 text sets out that definition. So the worker’s tax residency is worth reviewing before any application. Second, insurers set their own underwriting questions for applicants on temporary visas. Those questions can differ from one carrier to the next.
Consent, Ownership, and Beneficiary Rules
Yes, the employee’s written consent is required before the company buys the policy. Florida law requires written consent from key employees before the insurance is purchased. The insured must also consent in writing on or before the contract is made. The Florida insurable interest statute sets out both rules.
The business may not retaliate against a key employee who refuses consent.
Federal rules for employer-owned contracts add more steps. The Florida statute requires written consent from key employees before the insurance is purchased; it does not contain the federal notice requirement for the employee’s intent to insure and maximum face amount. The employee must also give written consent. The employee’s written consent must cover being insured and the fact that the coverage may continue after employment ends, under IRC § 101.
Write the roles down. The company is usually the owner and beneficiary, and the employee is the insured. If the employee leaves, ownership matters. Federal law has special rules for transferring a policy for value, so review any transfer before it happens.
Employer Group Life Coverage Versus a Company-Owned Policy
Group life coverage and a company-owned policy are different arrangements. Group life comes through an employer’s benefit plan, and its terms follow the plan’s rules. A company-owned policy is an individual policy the business buys on a key person. The insurer underwrites that one person.
Group-term life coverage has its own federal tax rules. The part of its cost above certain exclusions is included in the employee’s income, under IRC § 79. Check the plan’s terms before assuming group coverage covers the same loss.
The two can coexist. A business may have a group plan for all staff and a separate individual policy for one key role. Each answers a different need. Start with the loss the business wants to cover, then compare the two.
What Shapes the Cost of Coverage
Cost depends on the insured’s age, health history, and tobacco use. It also depends on the policy type and the insurer’s rates. Each case is priced on its own facts.
Policy type matters too. FINRA explains that term life insurance covers a limited period. Whole or permanent life insurance provides lifetime coverage and includes a cash value feature. A whole life insurance policy includes a cash value component, which is part of the policy contract and builds over time according to the policy’s terms. Guaranteed cash values and non-guaranteed values are shown separately, and the non-guaranteed amounts are not assured. Name the plan type whenever cost comes up, because the two structures work differently.
A fully underwritten policy requires health questions, and issue may depend on insurability. Underwriting questions about health and residency shape the offer an insurer can make.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Other Coverage Arrangements a Company May Consider
Companies often compare key person coverage with group life, disability coverage, and buy-sell arrangements. Each option answers a different loss. Disability coverage addresses lost income from injury or illness, not death. So start with the financial loss you want to cover.
A buy-sell arrangement works differently. Florida law lets an individual party to a contract to buy or sell an interest in a business entity have an insurable interest in the other party’s life, but only for that contract. The Florida insurable interest statute states this rule. The Florida insurable interest statute states this rule. Owners who agree to buy each other’s shares may use it for a buy-sell agreement.
Next Steps for Your Company’s Situation
If your company depends on an H-1B employee’s work, start by naming the financial loss in plain terms.
Nischay Rawal, a licensed insurance agent, handles the insurance side of this question. Insurance is offered by the licensed agent, separately from the firm’s accounting practice.
Can a company buy life insurance on an H-1B employee?
Yes, generally, when the company has an insurable interest and a key employee consents in writing before the insurance is purchased.
Does the employee have to agree?
Yes. Florida law requires written consent from key employees before the purchase. The company may not retaliate against someone who refuses.
Is key person insurance the same as group life?
No. Group life comes through a benefit plan. Key person coverage is an individual policy the business owns on one key employee.
If your company is weighing whether it can insure an H-1B employee’s life, our team can talk through that question in a coverage review. Contact NR CPAs & Business Advisors to request one.
Before you apply
Whether a policy fits your business depends on your insurable interest, the insured's health answers, the policy terms and your tax and cash flow picture. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the firm's accounting practice.
How NR CPAs & Business Advisors helps
Key person coverage
We help businesses review key person insurance and how it could support the company if a valued employee's life changes unexpectedly.
CPA view of tax and cash flow
Our team looks at how premiums and policy choices may affect your business's cash flow and tax position.
Plain-language explanations
We explain policy terms, limits and exclusions in everyday words, so you can compare options with a clear picture.
Serving Florida from Miami
Based in Miami, we help Florida business owners and professionals across the state, including Fort Lauderdale, West Palm Beach, Orlando, Tampa and Jacksonville.
Topics we review together
Insurable interest
We discuss the business relationship behind any policy and whether the coverage matches what the company stands to lose.
Employee consent
We walk through the written consent steps that apply to key employees before coverage is purchased.
Policy type
We compare key person, term and whole life insurance so the structure fits your business goals and budget.
Tax and cash flow
We look at how premiums, ownership and beneficiary choices may affect your books and your tax position.
Protect the people and plans your business depends on
Related practice areas
- Can I Buy My Key Person’s Life Insurance Policy From My Business? The Transfer-for-Value Rule
- Are Maturity Proceeds From Life Insurance Taxable?


