



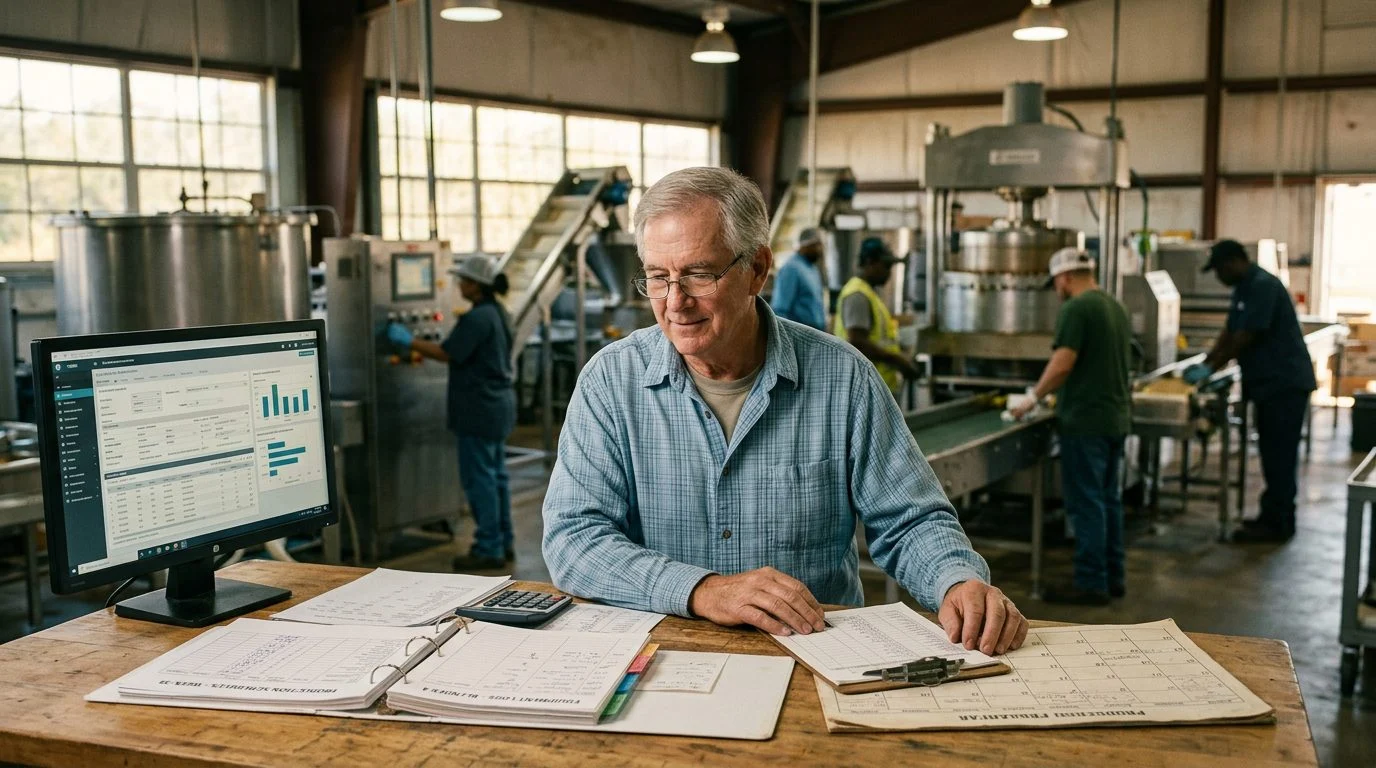
Florida Farm Businesses | Miami
Key Person Insurance for Florida Farm Businesses
Life insurance that helps a farm business plan for the loss of a key owner or operator. Nischay Rawal, a licensed insurance agent, offers this coverage separately from the firm's accounting practice.
By Nischay Rawal · Published October 27, 2026
Key person insurance is life insurance that a business owns, pays for, and collects from when the covered person dies. On a farm, that person is often the operator who makes planting, breeding, harvest or grove decisions, or a partner who holds the buyer and lender relationships. This guide explains how key person insurance farm business coverage works, what the death benefit can and cannot do, and how a coverage review fits in.
What Key Person Insurance Is and Who It Fits on a Farm
Key person insurance is a policy the business applies for, owns, and pays premiums on. The business is also the beneficiary, so the business receives the death benefit. The insured person is someone whose loss would seriously hurt the operation.
It fits several farm setups. A sole proprietor with a key worker may use it. Family farms, LLCs and partnerships where one person runs daily work often use it too. Florida law lets a partnership, LLC or corporation have an insurable interest in its owners, partners, managers and key employees. The business must get written consent from that person before buying the coverage (Fla. Stat. § 627.404).
For the broader topic, read our key person insurance guide.
Insurance is offered through Nischay Rawal, a licensed insurance agent in Florida, separately from the accounting practice of NR CPAs & Business Advisors. Florida law requires an agent to make clear that they act as an insurance agent when selling insurance (Fla. Stat. § 626.9531). Any specific policy we discuss will name its insurer.

Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Identifying the Farm Roles to Insure
Insure the person whose absence would cause the largest and fastest loss to the operation. Start with the roles, not the job titles.
Common roles to review include:
- The principal operator, who makes calls on planting, breeding, harvest or grove work that cannot wait.
- A co-owner or partner, whose loss could change who controls the business.
- A buyer, lender or supplier contact, whose absence could interrupt sales or cash flow.
- A key worker, whose replacement would be costly or slow.
For a key worker, weigh two things. Compare the cost of hiring a replacement with the time it takes to train a successor. A worker who takes a season to replace may matter more than one who is easy to find. Write down who signs for debt, who holds the relationships and who knows the land, the herd or the grove best. Those answers point to the people worth insuring. For a deeper look at one scenario, see what happens to my business if my partner dies.
What the Policy Pays and What It Does Not Cover
The death benefit goes to the business, and the business decides how to use it. The money is not tied to a specific expense. Common uses include loan payments, operating expenses, payroll during a transition, and hiring or training a replacement.
Cash-flow planning turns the benefit into numbers. Add up the monthly operating costs, loan payments and payroll the farm must keep paying. Then see how many months the benefit would cover. Our page on months of operating cash after losing an owner shows this math in more detail.
Key person life insurance does not cover everything a farm can lose. It does not cover:
- Farm property, buildings or land
- Crops, equipment or livestock
- Liability claims
- Losses from weather or disease
Those losses need separate property and liability coverage. Life insurance also pays a death benefit only. It does not restore lost production or guarantee the farm’s income. For how a business can handle a loan after an owner dies, see business loan when an owner dies.
Term or Whole Life for a Farm Key Person
Term life covers a set number of years. Many farms match a term to a loan or a known transition window. Ask how premiums change at renewal and with age, since terms differ by policy.
Whole life is permanent coverage that can build cash value. Present the guaranteed and non-guaranteed values separately, because they work differently. Dividends are not guaranteed. Florida law lets a whole life policy be borrowed against, through the insurer advancing funds on proper assignment or pledge of the policy, once it has a cash surrender value and no premium is in default, though the insurer may defer granting a loan for 6 months after application, except a loan to pay a premium to the insurer (Fla. Stat. § 627.458). That same section does not apply to term policies, so a term policy has no loan feature under this rule.
The business, not the individual, usually owns the policy. Ownership decides who can change the policy, borrow against it and name beneficiaries. Premiums are set in underwriting. Age, health, coverage amount and policy type all affect the price.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
How the Process Works, Step by Step
The process starts with a coverage review and moves through application, underwriting and policy issue. Timing depends on the insurer’s underwriting process.
- Coverage review. We map the farm’s ownership structure, key roles, debts and cash-flow needs.
- Choose the amount and policy type. We discuss how the business would use the benefit and what coverage level fits.
- Application. Fully underwritten policies require health questions, and issue may depend on insurability.
- Underwriting and issue. The insurer reviews the application. If approved, the policy is issued and names the insurer, the business as owner and the business as beneficiary.
- Periodic review. Revisit the plan when the farm adds a partner, takes on new debt or changes its succession plan.
Key Person Coverage Compared With Buy-Sell Coverage
Key person insurance pays the business to protect operations and cash flow. Buy-sell agreement insurance funds the purchase of a deceased owner’s share, so the surviving owners or family members can buy it under the agreement’s terms.
Farms with co-owners often need to consider both. One policy keeps the operation running. The other helps the owners carry out the buyout they agreed to. They can be structured to work together, but the agreement and the policies must match.
Estate rules matter too. Under federal law, the gross estate includes insurance receivable by the executor under policies on the life of the decedent, to the extent of the amount receivable.
Tax treatment depends on the facts of the ownership structure and the policy. Generally, death benefits are excluded from gross income, but interest received on those proceeds is taxable (IRS FAQ on life insurance proceeds). Federal law also says no deduction is allowed for premiums when the taxpayer is directly or indirectly a beneficiary of the policy (26 U.S.C. § 264). So a business that is the beneficiary of its key person policy generally cannot deduct those premiums.
Questions Farm Owners Ask Before Buying
How much does key person insurance cost on a farm?
Premiums depend on the insured person’s age, health, coverage amount and policy type. The insurer sets them in underwriting.
Does this replace farm property or crop insurance?
No. It is life insurance. It does not cover property, crops, equipment, livestock or liability.
Who owns the policy and who gets the money?
The business usually owns the policy and is the beneficiary. The business decides how to use the proceeds.
Are health questions required?
Yes, for fully underwritten policies. Issue may depend on insurability.
Can a family member apply for coverage on a farm operator?
The business applies for coverage on the key person. Florida law requires that person’s written consent before the policy is bought (Fla. Stat. § 627.404).
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Why Work With NR CPAs & Business Advisors and Next Steps
NR CPAs & Business Advisors is a Miami CPA firm. We help business owners and families choose and buy life insurance. We pair the policy decision with a CPA’s view of tax and cash flow.
Our agent, Nischay Rawal, is a licensed insurance agent in Florida. Insurance is offered separately from the accounting practice. We use plain words for terms like cash value and beneficiary, and we present guaranteed and non-guaranteed values separately.
If you’re researching life insurance for your household, this page explains the main coverage types in plain terms. You don’t have to sort out the ownership, the debts and the policy on your own. When you’re ready, contact NR CPAs & Business Advisors to set up a coverage review of your farm’s key roles, debts and cash-flow needs.
How we approach key person coverage for farms
Start with the business
We look at which owner, partner or operator the farm depends on for income, management and day-to-day decisions before discussing any policy.
Tie coverage to the operation
We discuss how the policy amount, ownership and beneficiary relate to the farm's debts, cash flow and succession plans.
Keep personal and business needs apart
Key person insurance is a business planning tool. We explain how it differs from coverage for family income or estate needs.
Clear explanations
We explain insurance terms in plain words, including how underwriting, health questions and insurer decisions affect the policy.
Key warning
Key person insurance is life insurance. It does not cover farm property, crops, equipment, livestock or liability. Premiums are set by the insurer based on the insured person's age, health, coverage amount and policy type, and issue depends on underwriting, which includes health questions.
Common questions Florida farm owners bring to our coverage review
Who should be insured?
The insured is usually a person whose work, knowledge or relationships are important to the farm's income. We help you identify that person with your own records.
Who owns the policy?
Ownership and beneficiary choices affect how proceeds are used. We review these choices alongside your business structure.
How much coverage?
The amount is a planning decision. We look at debts, loan obligations and the cost of replacing the key person's role.
Whole or term?
Term and whole life insurance work differently. We explain the features of each so you can compare them against your farm's needs.


