



Key Person Insurance | Miami, Florida
Key Person Insurance for an Employee in India
NR CPAs & Business Advisors helps U.S. business owners review key person coverage on an employee based in India, with a CPA's view of tax and cash flow. Insurance is offered by Nischay Rawal, a licensed insurance agent.
By Nischay Rawal · Published November 4, 2026
Key person insurance on an employee living in India is a life policy your U.S. business can own on that person. The company may have an insurable interest in a key employee, but only if the employee gives written consent before the insurance is purchased. Three questions decide whether the arrangement works: who owns and pays for the policy, whether consent is documented, and which policy terms apply to an insured living abroad.
NR CPAs & Business Advisors is a Miami CPA firm. We help business owners, professionals and families across the United States, including Indian-American households and business owners, look at life insurance with a view of tax and cash flow. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the firm’s accounting practice.
What key person insurance is and when it applies to an employee in India
Key person insurance is a life policy a business buys on someone whose death or disability would cost the company money. The Insurance Information Institute’s key employee guide describes it as coverage that compensates a business for losses caused by a key employee’s death or disability. In a typical arrangement, the business buys the policy, pays the premium and is named as beneficiary.
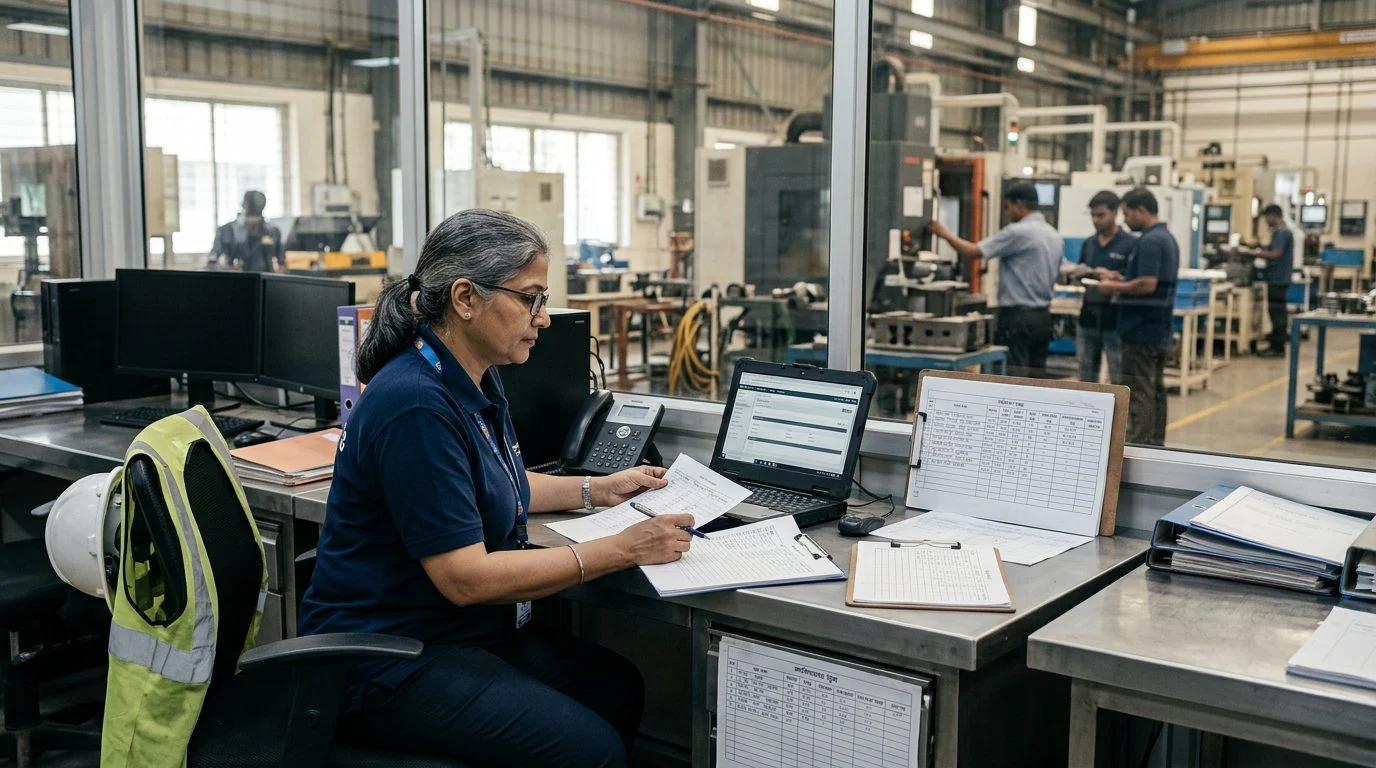
Key people are often a founder, a technical lead, a sales head or a senior manager. Some of them work for a U.S. company from India. That location changes the paperwork. Underwriting, medical steps, premium payment methods and claim forms can all differ for an insured who lives outside the United States.
Whole life and term policies can both fit this use. The right structure follows a written business need, such as the cost of replacing that person’s role. A policy with no clear business reason is hard to justify in the company’s records.
If a key employee in India is central to your company's plans, our team can walk through ownership, consent and policy terms with you in a coverage review. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Who owns, pays for and receives the policy
In a key person policy, the company is usually the owner, the premium payer and the beneficiary. The employee is the insured. These roles should match across the application, the issued policy and the company’s books.
The employee’s family does not automatically receive the death benefit under a company-owned policy. The named beneficiary receives it under the policy’s terms. Review these three roles before the application is filed, and keep a signed record of the decision in the company’s files.
Insurable interest and written consent for an employee in India
A business needs an insurable interest in the employee when the policy is made, and the employee’s written consent on or before that time, before it can own a policy on that person’s life. The interest need not continue after coverage begins. Insurable interest means the business would take a real financial loss if the employee died or became disabled.
The same statute bars the company from retaliating against a key employee or key person who refuses consent. It also says the insurable interest need not exist after coverage starts.
Federal rules for employer-owned policies also look for written consent. Under IRC § 101(j), the exceptions apply only when the notice and consent requirements of paragraph (4) are met. Whether Florida’s statute reaches an insured in India depends on the policy’s facts and where it is issued.
A simple consent form should include:
- The employee’s full legal name and the company as owner
- The beneficiary and the benefit amount
- A statement that the employee consents to the policy and its terms
- The signing date is one of the details we review with you.
- Where the signed original is kept
Underwriting an insured who lives in India
Underwriting is the insurer’s review of the insured’s health, occupation and residence before it issues a policy. Health questions are required, and issue may depend on insurability. The answers help set the risk class and the premium.
For an overseas insured, expect these steps: a written application, a medical exam that may be arranged in India, statements from the insured’s doctors, and travel questions where they apply. Ask the insurer for its timeline in writing.
Insurers set their own rules for residents outside the United States. Confirm the country of residence, the currency and the payment method before you file. Read the insurer’s written illustration before signing. Guaranteed and non-guaranteed values appear separately. Dividends, where offered, are not guaranteed.
Tax and accounting points a CPA reviews before buying
Premiums are generally not deductible when the business is the beneficiary. Under IRC § 264, no deduction is allowed for premiums on a life policy if the taxpayer is directly or indirectly a beneficiary under it.
Life insurance proceeds are generally not taxable, according to the IRS guidance on life insurance proceeds. For employer-owned policies, IRC § 101(j) generally caps the tax-free amount at the premiums and other amounts the company paid. That limit is lifted only when the notice and consent requirements of § 101(j)(4) are met and one of the exceptions listed in § 101(j)(2) also applies. Check the rules for your facts before you assume the full benefit is tax-free.
Employer-owned policies also trigger an annual filing. IRC § 6039I requires a return showing whether valid consent exists for each insured employee. Keep the signed forms with the return records.
For cash flow, budget the premium as a fixed yearly cost. For whole life, track the policy’s cash value separately from the death benefit. Review the policy each year with the company’s books. Whole life must also meet the federal definition of a life insurance contract, under IRC § 7702.
How the process runs and the terms to check before signing
- Coverage review. We start with the business need, the insured, the ownership structure and the benefit amount.
- Documents. Gather the employee’s role, residence details, the signed consent form and the company’s entity information.
- Application and underwriting. Expect medical steps arranged for an insured in India. Get the insurer’s timeline in writing.
- Issue and delivery. Compare the issued policy with the application and the illustration before you accept it.
Check these terms before signing:
- Death benefit and any change to the face amount
- Premium amount and how long it is payable
- Exclusions and limitations
- Grace period. Florida policies must allow at least 30 days to pay a premium after the first, with interest capped at 8 percent a year, under Fla. Stat. § 627.453.
- Contestability. Florida requires the policy to become incontestable after it has been in force during the insured’s lifetime for 2 years from issue, except for nonpayment of premiums and, at the insurer’s option, disability and accidental-death provisions, under Fla. Stat. § 627.455.
- If the insured’s age or sex was misstated, or that of another individual considered in setting the premium or benefit, the benefit adjusts to what the premium would have bought at the correct age or sex, under Fla. Stat. § 627.456.
- Renewability, cancellation and any age-based premium change.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Why work with NR CPAs & Business Advisors on this decision
NR CPAs & Business Advisors is a Miami CPA firm. We help business owners, professionals and families across the United States choose and buy life insurance. That includes whole life, term, key person, buy-sell, estate planning and NRI life insurance.
Our view combines tax, cash flow and insurance structure. Ownership, premiums and the policy’s tax treatment are reviewed together, so the policy and the company’s books tell the same story.
Nischay Rawal is this page’s responsible agent and acts as a licensed insurance agent. Florida law requires anyone acting as an insurance agent to be licensed and appointed. Insurance is offered by the licensed agent, apart from our accounting and tax services. Our team supports the coverage review and the application paperwork.
Frequently asked questions
Can a U.S. business own a key person policy on an employee in India?
The insurer’s residence rules and the consent requirements still apply.
Does the employee have to give written consent?
Yes. Florida law requires written consent before the contract is carried out, and federal employer-owned rules look for it too.
Who receives the death benefit?
The employee’s family does not receive it automatically.
Are the premiums tax-deductible?
Generally not, when the business is a beneficiary under the policy. Premiums are not deductible under IRC § 264(a)(1) when the taxpayer is directly or indirectly a beneficiary under the life insurance policy, endowment, or annuity contract.
Is the death benefit taxable?
Employer-owned rules can limit the tax-free amount.
How long does the process take?
The timeline depends on underwriting and the insurer’s requirements for an insured abroad. The insurer should confirm the schedule in writing.
If a key employee in India plays a central role in your company, you don’t have to sort out ownership, consent and policy terms alone. Reach out through our contact page to set up a coverage review.
What a coverage review looks at
Ownership and insured person
We look at which entity owns the policy, who is insured, and who is named as beneficiary.
Consent and documentation
We walk through the written consent and paperwork the insurer and your business will need.
Premiums and cash flow
We help you see how premium payments fit your business budget and how they may be treated for tax purposes.
Insurer requirements
We review the insurer's residence rules and underwriting questions before any application is made.
Why business owners bring this to our team
Built for cross-border employees
We work with U.S. businesses that have staff or key contributors in India.
Coverage and tax viewed together
Our CPA perspective helps you weigh the policy's cost against your tax and cash flow picture.
Plain-language explanations
We explain policy terms, limitations and exclusions in clear words so you can decide with confidence.
Direct contact
Call our office to set up a coverage review with Nischay Rawal.
Insurance is offered separately from our accounting practice
Key person coverage is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting work of NR CPAs & Business Advisors. Insurer rules, health questions and insurability can affect whether and how a policy is issued.


