



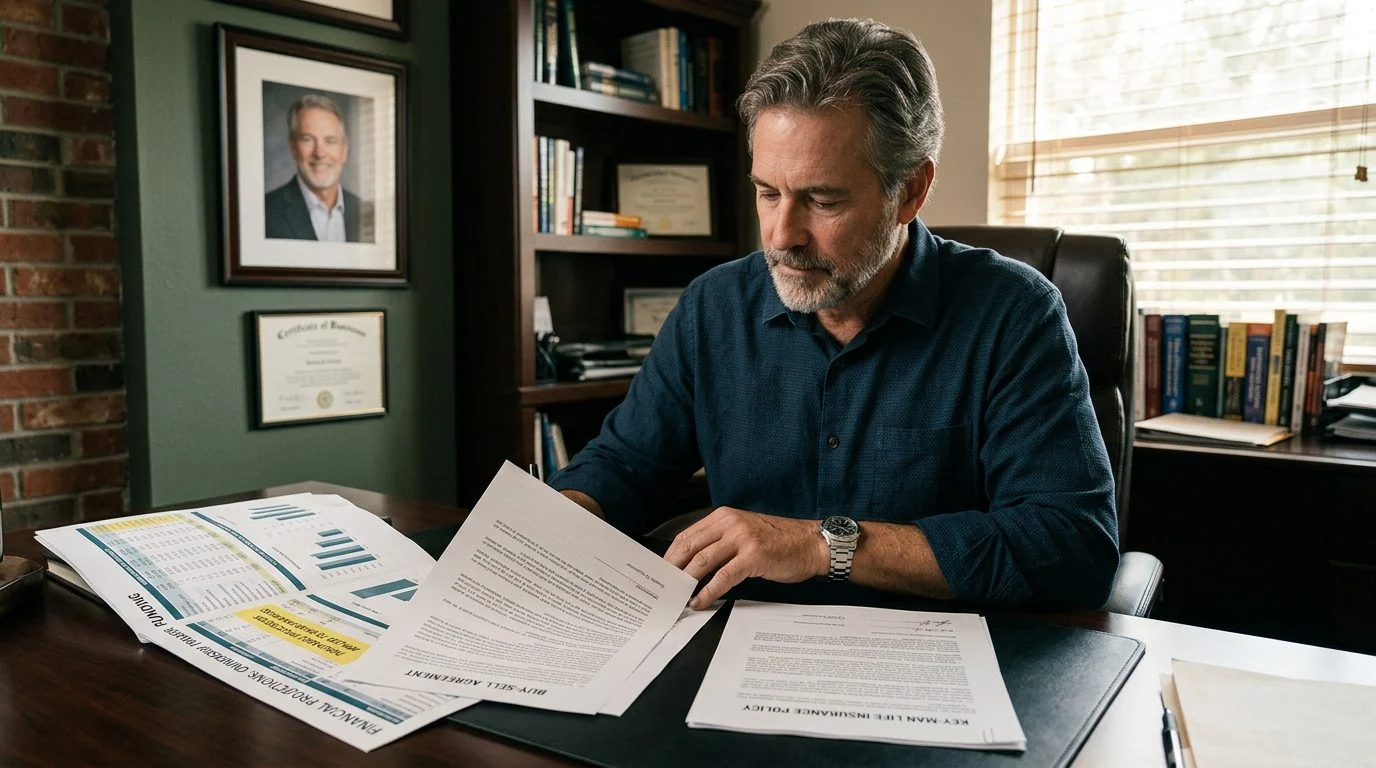
Buy-Sell Agreement Insurance | Florida
Plan the LLC Buy-Out Before an Owner's Death Changes the Business
How buy-sell agreement insurance can help fund the transfer of a Florida LLC interest, viewed through a CPA's lens of tax and cash flow. Nischay Rawal, a licensed insurance agent, offers coverage reviews separately from our accounting practice.
By Nischay Rawal · Published October 31, 2026
That document usually sets the steps. If the agreement is silent, Florida’s LLC statute fills the gap. The estate, the heirs and any buy-sell agreement then shape the final transfer. This guide follows that order and explains how life insurance can supply the cash to complete it. It comes from a CPA firm’s view of cash flow. Insurance is offered by a licensed agent, separately from the accounting practice.
What Happens to an LLC When One Owner Dies?
An LLC does not simply stop when one owner dies, and the deceased owner’s share does not vanish. Two sources decide what comes next: the operating agreement and Florida’s LLC law.
Under Fla. Stat. § 605.0105, an operating agreement generally sets the rules for the members’ relations with one another and with the company, except as subsections (3) and (4) provide otherwise.
Florida law also treats a death as the end of a member’s role. Under Fla. Stat. § 605.0602, an individual is dissociated as a member when that person dies.
Two parts of an interest are often mixed up. Management rights are separate. Under Fla. Stat. § 605.0603, a dissociated person loses the right to manage. The interest is then owned by the person solely as a transferee, subject to ss. 605.0504 and 605.1001-605.1072, meaning someone who receives it without management rights.
If a co-owner has died and no one is sure which document controls the interest, our team can set up a coverage review to talk through your options. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Start With the Operating Agreement
The operating agreement is the first document to read, and it usually controls the transfer. Pull the signed version, every amendment and the company’s ownership records.
Look for these clauses:
- Transfer restrictions that limit who can receive an interest.
- Rights of first refusal, which let the other owners buy the interest first.
- Death or withdrawal terms that set a price, a notice period or a buy-out step.
- Consent rules that the other members must sign off on.
Amendments matter. Under Fla. Stat. § 605.04073, the operating agreement may be amended only with the affirmative vote or consent of all members. A change made after a death must meet that test, so a simple majority is not enough.
Then check whether a successor becomes a full member. Under Fla. Stat. § 605.0401, after formation a person becomes a member as the operating agreement provides, through a merger, interest exchange, conversion or domestication, with the consent of all members, or as provided in s. 605.0701(3).
When No Operating Agreement Is in Place
Without an operating agreement, Chapter 605 supplies the rules.
The usual pattern looks like this:
- The estate or heirs can receive the economic interest. Under Fla. Stat. § 605.0502, a transferee is entitled to the distributions the owner would have received.
- The same section says a transferee is not entitled to take part in management.
- The legal representative can act for the deceased member. Under Fla. Stat. § 605.0504, that person may exercise the member’s rights to settle the estate.
Without a written plan, surviving owners and heirs must sort out these rules after the death, at the hardest possible time. Writing the plan before a death is easier than writing it afterward.
Can Your Children or Heirs Inherit an LLC Interest?
A child or other heir can receive the economic interest. That means a share of distributions. Becoming a voting member is a separate question.
Under section 605.0401(3), a person becomes a member after formation as the operating agreement provides, with the consent of all the members, or in one of the other ways listed in that subsection.
Heirs should not assume a vote comes with the share. Check the agreement first.
Heirs who live outside the United States, or who hold citizenship in another country, may face extra questions about paperwork, payments and tax reporting. Raise those early, before any transfer is drafted.
How a Buy-Sell Agreement Funded With Life Insurance Works
A buy-sell agreement requires a deceased owner’s share to be bought at a price or formula set in advance. It answers who buys and what they pay before anyone needs to know. Business owners use estate planning and succession arrangements to name successors and manage operations after an owner’s death, according to the American College of Trust and Estate Counsel.
Two common structures exist:
- Cross-purchase: each owner agrees to buy the others’ shares, and the owners may own policies on each other.
- Entity redemption: the company buys the deceased owner’s share.
The structure decides who owns each policy and who receives the death benefit.
Key person insurance is the business side. According to the Insurance Information Institute, key person life insurance compensates a business for financial losses caused by a key employee’s death.
Term life insurance covers a set number of years. Whole life insurance is permanent coverage. Each can fit a funding plan, and neither promises a particular result for the buy-out.
Ownership also matters for estate tax. Under 26 U.S.C. § 2042, insurance payable to other beneficiaries can count in a deceased owner’s gross estate, to the extent of the amount receivable, if the owner held certain rights over the policy at death.
Practical Steps for the Surviving Owners and the Family
The first steps are to secure records, follow the notice rules in the agreement and confirm who can act. Do this before any payment or transfer is signed.
- Secure the operating agreement, amendments and ownership records.
- Give the notices the agreement requires to the remaining owners.
- Confirm who has authority for the company and the estate.
Ask your CPA how the change should appear in the company’s books and returns. Estate tax can also strain cash flow.
Under 26 U.S.C. § 6166, if the decedent was a U.S. citizen or resident at death and an interest in a closely held business exceeds 35 percent of the adjusted gross estate, the executor may elect to pay part or all of the estate tax in two to 10 equal installments.
Review insurance proceeds and the purchase terms with the tax preparer and the estate’s advisers before money moves. Term coverage can suit owners who want protection for a set number of years.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Talk Through Your LLC’s Situation With Our Team
Our team can set up a coverage review, which is the first meeting on insurance questions like these. Nischay Rawal acts as a licensed insurance agent for the insurance side, and insurance is offered separately from the accounting practice.
How to transfer ownership of LLC after death of owner?
Start with the operating agreement, then check Chapter 605 of the Florida Statutes for any gap it leaves.
Can a child inherit an LLC?
A child can receive the economic interest.
Can life insurance fund a buy-out?
It can, when a buy-sell agreement is written and funded that way. Who owns each policy affects estate tax treatment.
If you are dealing with a co-owner’s death right now, reach out through our contact page and we can talk through a coverage review.
Four Questions to Answer Before a Transfer Is Needed
Read the operating agreement
Start with the operating agreement and any buy-sell terms. They set out what the company and its members have agreed should happen to an owner's interest.
Identify the gaps
Agreements often leave questions open about valuation, who may buy, and how payment is made. Chapter 605 of the Florida Statutes may fill some gaps, but not necessarily the ones your business faces.
Estimate the cash needed
A buy-out requires funds at a specific moment. Compare the likely purchase price with the cash, reserves and credit the business or remaining owners actually have.
Match funding to the agreement
Buy-sell agreement insurance can be structured to provide funds for a buy-out. The policy should reflect the agreement's terms, not the other way around.
How a Coverage Review Can Help
Agreement check
We look at how your operating agreement and buy-sell terms would work if an owner died, and where they are silent.
Buy-sell funding
We discuss how life insurance may be used to fund a buy-out, including the whole life insurance and term life insurance options.
Key person coverage
We review key person insurance for the owners and employees whose loss would affect the business's cash flow.
Tax and cash flow view
As a CPA firm, we consider how premiums, payments and ownership changes may affect the business and the family.
Insurance Is Not a Substitute for a Clear Agreement
Life insurance can provide funds for a buy-out, but a transfer is only as clear as the agreement behind it. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice.


