



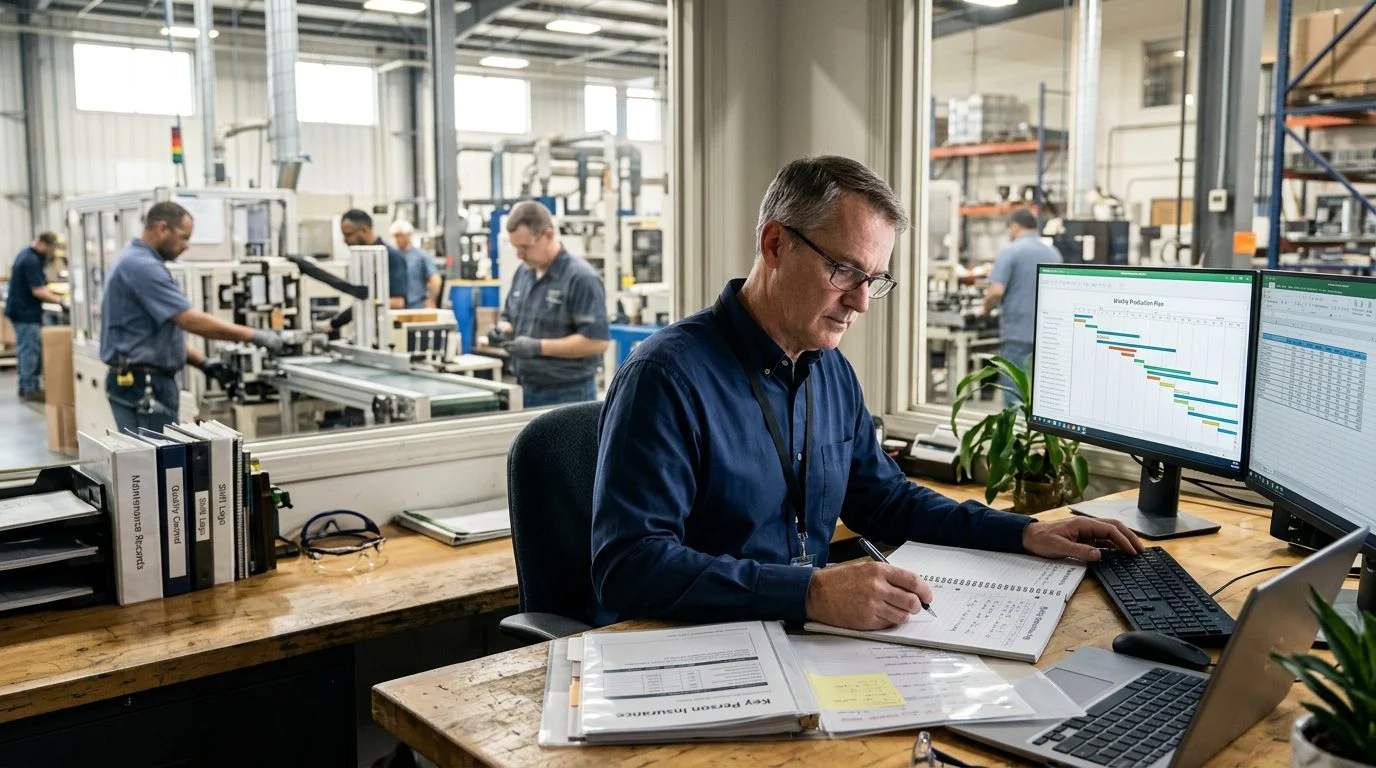
Key Person Insurance | Florida
Bring Your Business Partners Into the Key Person Insurance Conversation
A clear, CPA-informed way to explain key person coverage to partners, co-owners and the people who depend on your business. Call us today to schedule a coverage review.
By Nischay Rawal · Published October 25, 2026
To tell your business partners about key person insurance, start with the facts and explain the plan in plain terms. Key person insurance is life insurance that a business buys on an owner or employee whose work the company depends on. The business pays the premiums and receives the benefit. This guide is written for Florida co-owners and investors who want to raise the topic without friction. Insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors.
What key person insurance is and why partners need to hear about it
Key person insurance is a life insurance policy the business owns on the life of someone it cannot easily replace. That person might be an owner, a senior manager, or a key employee. If that person dies, the policy pays the business, not the family. The Insurance Information Institute explains that this coverage compensates a business for financial losses caused by the death or disability of a key employee.
Partners need to hear about it early. They share the company’s bank accounts, debts, and decisions. A policy one owner wants affects every owner, even when that owner is not the insured. Partners should know what the policy is, who pays for it, and what the money will be used for before anyone signs.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Prepare the facts before you tell your business partners
Gather the facts first. A clear list keeps the talk on the business instead of on guesses. Start with the key person’s name, their role, and the reasons the business relies on that role.
Next, collect the ownership percentages and your current governing documents. Pull out any buy-sell or shareholder agreement the owners already signed. Partners will want to see these first.
Then name the coverage question in business terms. Which operations or obligations would need support if this person died? Stay with the question. Do not estimate a dollar figure or an outcome in the first talk. Finally, decide who will own the policy, who will pay the premiums, and who will be the beneficiary. Partners will ask about these three points almost at once.
Frame the conversation around continuity, not fear
Open with the goal every owner shares: a stable company and a fair partnership. That goal gives the talk a common starting point. It also keeps the focus on the business.
Describe the policy as a planning tool for the company. It is not a forecast of any owner’s death or illness. Avoid pressure. A partner who feels rushed is more likely to resist, and a rushed decision is often a weak one.
Invite questions instead of handing partners a finished plan. Send the fact list ahead of the meeting. Let each owner read it, mark what is unclear, and come back with questions. This gives everyone time to think.
Explain the policy mechanics partners will ask about
In the usual key person setup, the business owns the policy, pays the premiums, and is the beneficiary. This is the arrangement partners will ask about first.
Taxes come up quickly. Under 26 U.S.C. § 264, no deduction is allowed for premiums on a life insurance policy when the taxpayer is directly or indirectly a beneficiary. Because the business is usually the beneficiary, its premiums generally are not deductible. Our team can confirm how the treatment applies to your own facts.
Proceeds are a separate question. Under 26 U.S.C. § 101, amounts paid because of the insured’s death are generally excluded from gross income, subject to listed exceptions. For employer-owned life insurance contracts, an applicable policyholder’s exclusion from gross income is generally limited to the premiums and other amounts the policyholder paid, but exceptions apply, including amounts paid to certain family members of the insured, any individual who is the insured’s designated beneficiary under the contract (other than the applicable policyholder), trusts for their benefit, or the insured’s estate. Annual filing rules under 26 U.S.C. § 6039I may also apply.
Health matters too. A fully underwritten policy asks health questions, and approval may depend on insurability. Partners should understand that the insured’s health history affects whether the policy is issued.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Connect the policy to your buy-sell agreement
A buy-sell agreement sets out what happens to an owner’s share when that owner leaves or dies. Key person coverage can help fund the buyout, but only if the two documents match.
Florida law sets different rules by entity type. For a partnership, Fla. Stat. § 620.8701 requires the partnership to buy a partner’s interest when that partner leaves without ending the business. If no agreement is reached within 120 days after a written demand, the partnership must pay its estimated buyout price and accrued interest in cash, reduced by any offsets.
For a limited liability company, Fla. Stat. § 605.0602 says a member is dissociated when an individual member dies.
Check that the valuation method, funding source, and payment terms in the buy-sell match the policy. If they do not, update the agreement before the policy is issued.
Answer the common questions partners raise
A business generally has an insurable interest in a key person when the legal conditions are met. The questions below come up most often.
Who can a business insure?
That interest exists if the person consents in writing before the insurance is bought. The business entity or affiliate may not retaliate or take adverse action against any key employee or key person who refuses consent to the insurance.
Does the insured have to consent?
Yes. The same statute says a contract of insurance on a person, other than a prepaid funeral, group life, or group or blanket accident, health, or disability policy, may not be carried out unless the insured, who has legal capacity, applies for or consents in writing to the contract and its terms. Get that consent on or before the policy is made.
What is the three-year rule?
Under 26 U.S.C. § 2035, property transferred by the decedent during the three years before death is pulled back into the gross estate if it would have been included under section 2036, 2037, 2038, or 2042 had the decedent kept it, unless the transfer was a bona fide sale for adequate and full consideration. Review any policy transfer before it happens, not after.
What happens if a key person policy is taken out or changed?
Ownership, premiums, or the beneficiary can shift, and that can change the coverage and the funding plan. Partners should review the buy-sell agreement and the tax effects before any change. Do not let a change happen on a handshake.
Put the agreement in writing and review it over time
Write down the decision before the policy is issued. Record who approved it, what the policy is for, and who owns and benefits from it. Put that record in the company’s minutes or governing documents.
Keep copies of the policy, the application, and the buy-sell terms together. Make them available to every owner. A file that only one partner holds creates problems later.
Review the arrangement on a set schedule. Also review it when ownership, compensation, or the key person’s role changes. Policy values and premiums can change over time, so partners should check current terms, not rely on the original talk. Our team can explain the differences between term and permanent coverage and the questions to ask before buying. The Florida Department of Financial Services guide covers policy loans, beneficiaries, and the review period after purchase.
Start the conversation with a coverage review
If you are getting ready to raise key person coverage with co-owners, start with your own facts. A co-owner in Miami, Fort Lauderdale, or West Palm Beach can bring the fact list, the governing documents, and the buy-sell agreement to a first meeting.
NR CPAs & Business Advisors offers a coverage review of your business’s situation. There is a fee for the coverage review, and we explain the fee terms before any work begins. Contact NR CPAs & Business Advisors to set up a time to talk through your facts.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Why Open the Conversation Early
Start with the business reason
Explain that key person insurance is a policy the business can own to help it plan for the financial effect of losing an important owner, leader or key employee.
Keep the details in writing
Clear written summaries of the coverage, the premium and the roles of each party make the discussion easier to follow for everyone involved.
Include every partner
Co-owners and partners usually have a stake in the decision, so bringing them in together builds shared understanding from the start.
Connect it to your broader plan
Key person coverage can sit alongside buy-sell agreements, estate planning and your tax and cash flow picture.
A Practical Tip
Put every step in writing, from the first discussion through the final signed paperwork. A written record helps all partners understand what was agreed and why.
Ways to Start the Discussion
Prepare a simple overview
Outline the business need, the people involved and the questions each partner wants answered before the meeting.
Review the numbers together
Bring the business's financial statements and cash flow information so the group discusses the same facts.
Agree on who does what
Decide which partner is the policy owner, who receives the policy information and who will sign each document.
Get a coverage review
Our team can walk your group through the policy structure, the tax considerations and the paperwork in one meeting.


