



Life Insurance Cost | Florida
How Much Is a $1,000,000 Life Insurance Policy a Month?
The monthly amount depends on the type of policy, the insured's age and sex, health answers and the payment schedule. A coverage review with NR CPAs & Business Advisors can help you see how those factors apply to your family and your business.
By Nischay Rawal · Published October 19, 2026
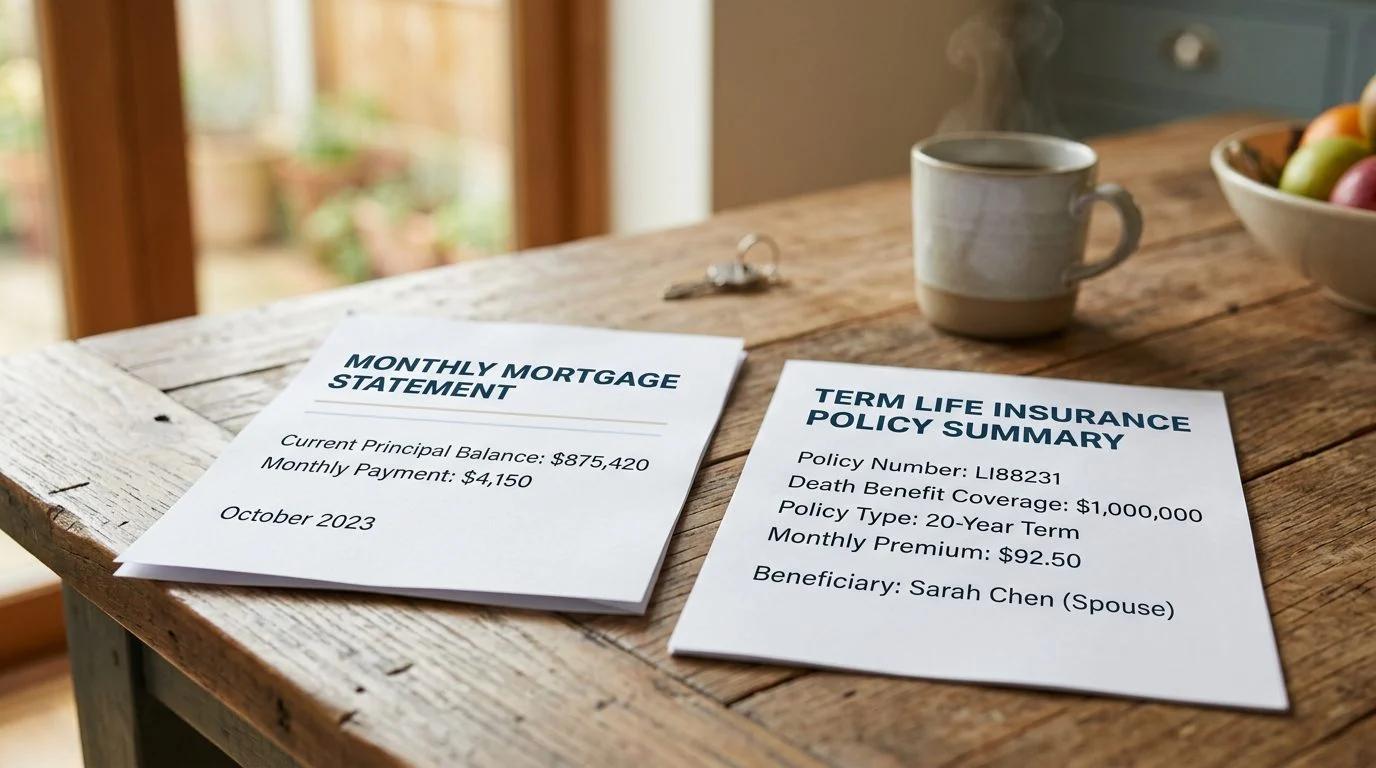
There is no single monthly price. The short answer is that the monthly amount depends on the type of policy, the age and sex of the person insured, their health answers, and how often premiums are paid. Two families can ask for the same $1,000,000 death benefit and see very different monthly figures.
This guide explains what moves the number, how term and whole life differ in structure, and what happens if a payment is late. It is written for Florida families, professionals and business owners who are trying to make sense of a quote or a proposal.
What decides the monthly cost of a $1,000,000 policy?
The monthly cost depends on the policy design and on the people the insurer rates. The age and sex of the insured are used to set the premium. Florida law says that if the age or sex of the insured, or of any other individual considered in determining the premium or benefit, has been misstated, the benefit is what the premium would have bought at the correct age or sex, based on the insurer’s rate at the date of issue (Fla. Stat. § 627.456).
Other factors matter too. Health answers and underwriting affect whether a policy is issued and at what terms. Insurers also set the premium based on the policy type you choose. Ask for the insurer’s name and the policy form number on any proposal you receive, so you can compare like with like.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Term or whole life: why the monthly number differs
The biggest driver of cost is the type of policy. Term life insurance covers a set number of years and has no cash value, according to the Oregon Division of Financial Regulation. Permanent life insurance stays in force while premiums are paid and includes a cash-value account, according to the same source.
The South Carolina Department of Insurance explains that term and permanent policies differ in duration and cash value. Its guide covers premiums, death benefits, cash-value growth, and borrowing against or cashing out cash value. The Alabama Department of Insurance adds that term policies can renew or convert, and that whole life premiums and cash value work differently from term.
Because the structures differ, a term premium and a whole life premium for the same face amount are not the same kind of cost. Look at what each payment buys, not just the amount.
Whole life insurance and term life insurance are both forms of life insurance. Each fits different goals. Estate planning life insurance and business coverage such as key person insurance or buy-sell agreement insurance use these same building blocks in different ways.
What happens if a monthly payment is late?
Florida requires every insurance contract to give at least a 30-day grace period for any premium after the first. The policy stays in force during that period. The insurer may charge interest of up to 8 percent per year for the days of grace (Fla. Stat. § 627.453).
The policy loan provisions of this statute do not apply to term policies or to term insurance benefits provided by riders or supplemental policy provisions (Fla. Stat. § 627.458).
Income tax and estate tax are separate questions
A death benefit and the value of a policy in an estate follow different federal rules. Under IRC § 101, except as otherwise provided in paragraphs (2) and (3), subsection (d), subsection (f), and subsection (j), gross income does not include amounts received (whether in a single sum or otherwise) under a life insurance contract, if such amounts are paid by reason of the death of the insured. That rule has exceptions, including certain transfers for value.
Estate size is a separate test. IRC § 2010(c)(3) sets the basic exclusion amount at $15,000,000, and that dollar amount is increased for inflation for any decedent dying in a calendar year after 2026. The IRS gift tax FAQ lists the gift tax annual exclusion at $19,000 per donee for 2026. A $1,000,000 policy does not need to be measured against these figures to be useful for planning. They answer a different question.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Who is offering the policy?
Nischay Rawal is the licensed insurance agent for coverage discussed on this page. Insurance is offered by the licensed agent, separately from the accounting practice of NR CPAs & Business Advisors, a Miami CPA firm.
Florida law requires agents to tell prospective insureds that they are acting as insurance agents, and to identify the insurers involved, when soliciting or selling insurance products (Fla. Stat. § 626.9531). Ask for this information in writing.
The firm, based in Miami, Florida, helps families, professionals and business owners choose and buy life insurance through Nischay Rawal, a licensed insurance agent, separately from the accounting practice. That includes Indian-American households and NRI families with cross-border planning questions.
Frequently asked questions
How much is a $1,000,000 life insurance policy a month?
There is no single answer. The monthly amount depends on the policy type, the insured’s age and sex, health answers, and the payment schedule.
Is a life insurance death benefit taxable income?
Under IRC § 101(a)(1), amounts received under a life insurance contract and paid by reason of the insured’s death are generally excluded from gross income. The statute’s exceptions can make part of a payment taxable. These include a transfer of the policy for valuable consideration (§ 101(a)(2)), which generally limits the exclusion to what the transferee paid plus later premiums and other amounts, unless the transfer is to the insured, a partner of the insured, a partnership in which the insured is a partner, or a corporation in which the insured is a shareholder or officer, or the transferee’s basis is figured from the transferor’s basis; interest on proceeds held or paid after the death (§ 101(c) and (d)); and certain employer-owned contracts (§ 101(j)).
How long is the grace period for a late premium in Florida?
Florida requires at least 30 days for any premium after the first. The policy continues during that period.
Does a death benefit count in the taxable estate?
It can. Under IRC § 2042, federal estate tax law includes in the gross estate proceeds receivable by the executor and proceeds payable to other beneficiaries where the decedent possessed, at death, any incidents of ownership, whether held alone or with another person.
Who is the agent on a policy from this firm?
Nischay Rawal is the licensed insurance agent. Insurance is offered separately from the firm’s accounting practice.
If you’re weighing a $1,000,000 policy for a spouse, parent or business partner, you don’t have to work out the numbers alone. Our team at NR CPAs & Business Advisors can walk through your situation and the coverage options that fit it.
What Shapes the Monthly Amount
Type of policy
Term life insurance, whole life insurance and other policy types are priced differently, and each carries its own limitations and exclusions.
Age and sex
The insured's age and sex are central to how insurers price a policy, which is why the same face amount can cost different amounts for different people.
Health answers
Health questions are part of the application, and issue may depend on insurability. Your answers shape the offer you receive.
Payment schedule
Monthly, quarterly, semi-annual and annual payment options change the amount you pay each time, so the schedule should be reviewed alongside the policy.
How We Help You Plan
Coverage review
We review your family's needs, your income and your existing coverage before any policy is discussed.
Plain-language explanations
We explain insurance terms, premiums, face amounts and exclusions in clear words so you can make an informed decision.
A CPA's view of tax and cash flow
Our team looks at how a premium fits within your monthly cash flow and how the policy relates to your broader tax picture.
Serving Florida families and business owners
We work with households and business owners in Miami, Fort Lauderdale, West Palm Beach, Orlando, Tampa and Jacksonville, along with clients across the United States.
Important: A Monthly Figure Is Not a Quote
The figure in this article is an illustration of how cost is shaped, not a premium quote. Your actual monthly amount depends on your individual application and underwriting. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice.
Protect your loved ones. Start with a coverage review.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.


