



Life Insurance | Florida and NRI Families
Moving Abroad? Review Your Life Insurance Before You Go
Talk with NR CPAs & Business Advisors about your policy terms, premium payments, and beneficiary details before you leave Florida.
By Nischay Rawal · Published October 26, 2026
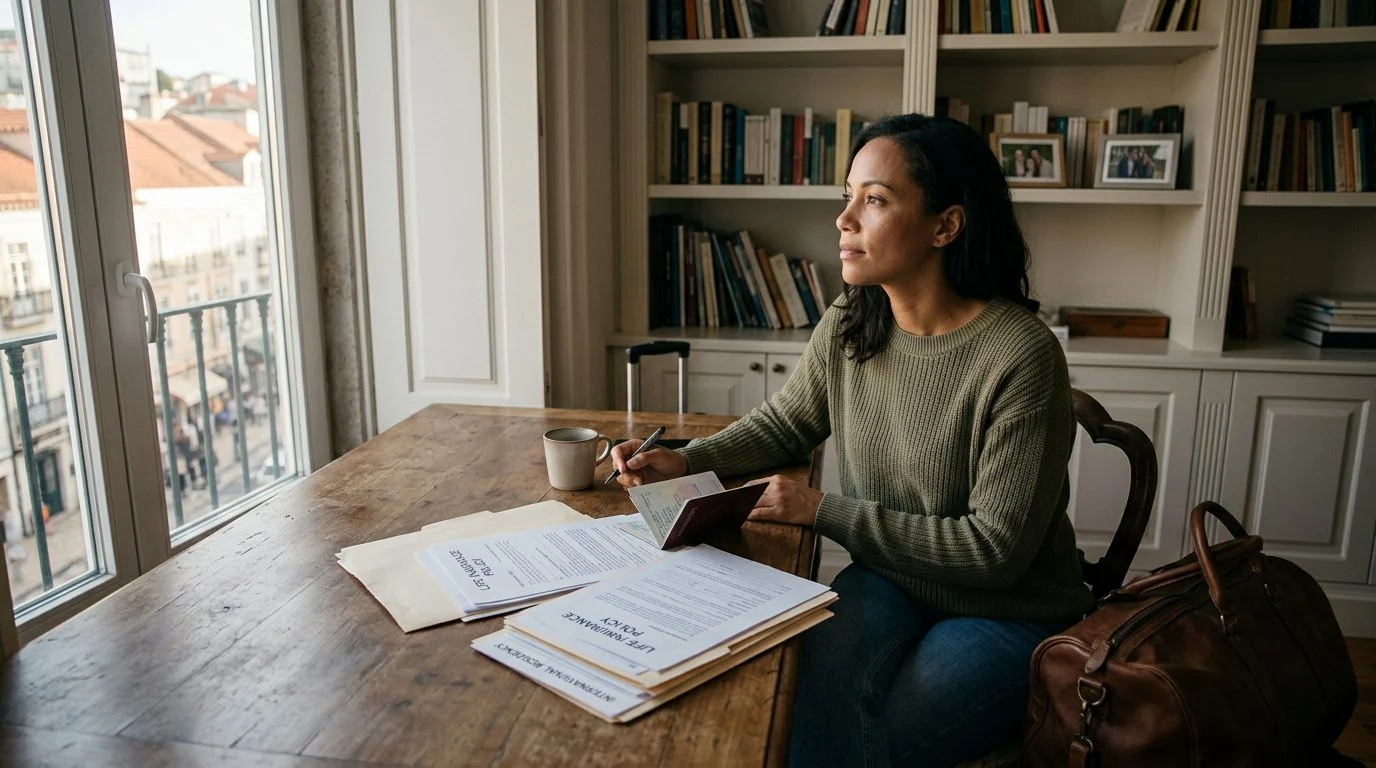
Does life insurance pay out if you move to another country? A move abroad does not end a life insurance policy on its own. Whether a benefit is paid depends on the written contract, the premiums, the residency terms, and the claim papers. This page covers each checkpoint in order. It is written for people who are moving, and for family members trying to understand a relative’s policy from far away.
Short answer: moving abroad does not settle it by itself
A move abroad does not automatically end a life insurance policy. It also does not guarantee a payment. The insurer’s written contract and rules decide the outcome, and no two policies are identical.
Three terms matter here. A policy is in force when its coverage is active. A benefit is the money the insurer pays when the insured dies. A beneficiary is the person or organization named to receive that money.
Treat the move as a set of questions. Does the policy stay in force? Does the contract limit coverage in the country you moved to? Can the claim paperwork be completed from there? The sections below explain what to check. They do not promise a result for any one policy. The outcome turns on your contract and the facts of your move.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Read the residency and territory terms in your policy
Your policy contract tells you what it says about living or traveling outside the United States. Start there before you assume coverage continues.
Look in the policy form, the application, and any riders. Terms about residence, territory, and travel are often spelled out there. Write down the insurer’s name, the policy form number, and the issue date. You will need them for every later step.
Some contracts list exclusions for certain events or activities. These can matter when a death occurs overseas. Florida law says a clause making a policy incontestable after a set time bars only a challenge to the policy’s validity. It does not stop an insurer from raising defenses based on exclusions or restrictions (Fla. Stat. § 627.463). Florida also requires a life policy to become incontestable after 2 years from its date of issue, except for nonpayment of premiums, at the insurer’s option as to provisions relative to benefits in event of disability, and as to provisions that grant additional insurance specifically against death by accident or accidental means (Fla. Stat. § 627.455).
Read the exclusion list before you assume the policy covers every situation abroad. Ask the insurer or your agent to explain any term in plain words.
Keeping premiums paid while living abroad
Keeping premiums paid is the step you control most directly after a move. A policy that lapses for non-payment generally cannot pay a benefit.
Paying from another country takes planning. Check how bank transfers, card payments, and currency conversion work for your policy. Update your mailing address with the insurer as soon as you move. Mail sent to an old address may never reach you.
Florida law builds in a grace period. Premium payment terms, including any grace period, are set out in each policy contract, so the contract is the place to confirm the terms that apply. Any interest charged on a late premium is set by the policy contract. How an overdue premium is treated when a claim arises during a grace period depends on the policy contract. Confirm the grace language in your own policy.
Policy loans carry a notice rule too. A policy may terminate if the loan balance reaches the loan value. That happens only after at least 30 days’ notice is mailed to the last known address of the insured or policyowner (Fla. Stat. § 627.458). An old address can cause real harm here.
Reporting a change of residence to the insurer
You should tell your insurer about a change of residence in writing. Insurers ask about residence, travel, and occupation when they issue a policy. These answers can affect how the insurer rates the risk, and the insurer reviews them again when a claim comes in.
Answer application questions accurately. An answer that does not match your real situation can cause trouble later, when the insurer reviews the file. Keep a copy of every form you send.
The insurer sets its own rules on issuing coverage to people who live outside the United States. Our team can explain how a policy works, but the insurer decides what it will accept. A written reply from the insurer carries more weight than a verbal assurance.
Keep copies of all correspondence. Save the confirmation of your address change, any reply confirming your policy status, and the dates of each message. These records help your family if questions come up later.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Term and whole life policies behave differently after a move
A term policy pays only if death happens during its set term. A whole life policy generally lasts for the insured’s life while premiums stay in force. The NAIC Life Insurance Buyer’s Guide explains these differences.
Moving does not extend a term. If the term ends while you are abroad, the policy will not pay after it expires. Check whether the policy has a conversion option to a permanent policy. Note the conversion window and age limit written in the contract.
Whole life values come in two parts. Guaranteed values are stated in the contract. Non-guaranteed values can change. Dividends on participating policies are not guaranteed. Read these figures separately, and ask for the written illustration with all its limits.
Surrendering, borrowing against, or replacing a policy after a move changes the benefit. Florida requires an agent who recommends surrender, without using the proceeds for another policy, to first give written information. That information includes, among other things, any estimated surrender charge, the loss of any minimum interest rate guarantees, possible tax consequences, any forfeited death benefit, and any other guarantees given up (Fla. Stat. § 627.4553). Under 26 U.S.C. § 1035, no gain or loss is recognized on certain exchanges of one life insurance contract for another, but only to the extent the statute’s conditions are met. Review these points before you act.
Claims when the beneficiary lives in another country
A beneficiary living abroad can still make a claim. The insurer needs written proof of death and proof of the beneficiary’s identity. Each step takes time.
Insurers commonly ask for a certified death certificate, a completed claim form, and identity documents. A foreign document may need an official translation or authentication before the insurer accepts it. The requirement depends on the country and the insurer. Ask for the insurer’s document list early.
For a lump-sum payment, Florida law requires interest from the date the insurer receives written due proof of death. The rate must be at least equal to the Moody’s Corporate Bond Yield Average monthly average as of the day the claim was received (Fla. Stat. § 627.4615). The payment method and currency depend on the insurer and the beneficiary’s bank.
Taxes need attention too. How amounts paid under a life insurance contract are taxed depends on the facts of each case, so confirm the tax treatment for your situation before relying on it. A beneficiary abroad may still have reporting questions. Those turn on the claim and the beneficiary’s country, so bring them to our CPA team early.
Keep the policy number and insurer contact details in your family records before any move.
Key person and buy-sell policies when an owner or key employee relocates
When an owner or key employee moves abroad, the business should review the policy and the agreement together. A change in one can affect the other.
A key person life insurance policy is owned and paid for by the business. It compensates the business for financial losses caused by a key employee’s death or disability (Insurance Information Institute). A move can raise practical questions. Is the employee still working for the business? Who pays the premium? Is the policy still needed in its current form?
A buy-sell agreement funded with life insurance depends on the policy staying in force. If an owner moves or dies abroad, the agreement’s terms on triggers, valuation, and payment should be read against the policy’s residency and premium terms.
Ownership also affects the estate. Under federal law, the gross estate includes life insurance proceeds receivable by the executor. It also includes proceeds receivable by other beneficiaries when the decedent held incidents of ownership at death (26 U.S.C. § 2042). IRC § 2042 reads: “For purposes of the preceding sentence, the term “incident of ownership” includes a reversionary interest (whether arising by the express terms of the policy or other instrument or by operation of law) only if the value of such reversionary interest exceeded 5 percent of the value of the policy immediately before the death of the decedent.”
These arrangements carry tax and accounting effects for the business. Our CPA team reviews those effects with the owners, alongside the insurance terms.
Talk through your own situation at a coverage review
You may be gathering facts for a parent, a sibling, or a spouse who is not in the room. That often means deciding under time pressure.
Some readers face a parent who took a job overseas and left a term policy at home. Others face a sibling who died abroad and left a policy with unclear terms. NRI households may hold US coverage while living in India or another country.
A coverage review is the first meeting where our team reads the policy with you. We look at residency and premium issues. We also look at how the coverage fits your family’s cash flow and estate plan. Where the facts call for it, our CPA team looks at the tax side too.
Insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the accounting practice of NR CPAs & Business Advisors. Florida requires an insurance agent to be currently licensed and appointed by an appropriate appointing entity or person before acting as one (Fla. Stat. § 626.112). Nischay Rawal is licensed in Florida.
Frequently asked questions
Does life insurance pay out if you move to another country?
A move alone does not end a policy. The contract, the premium payments, and the claim papers decide whether a benefit is paid.
How long is the grace period for a premium in Florida?
Can a beneficiary living abroad receive a payout?
A beneficiary abroad can file a claim. The insurer will need written proof of death and proof of identity.
If a move abroad has left you unsure whether a family policy still pays, reach out through our contact page to set up a coverage review.
What to Review Before a Move
Your Policy Contract
Read the policy form, the face amount, and any riders to see what the contract says about residence and coverage.
Premium Payments
Confirm how premiums are paid from another country, including currency, bank access, and payment dates.
Beneficiary Details
Make sure beneficiaries, contact information, and their location are current, especially if they will live abroad.
Claim Papers
Keep copies of the policy and identification records in a place your family can reach, and know what a claim will require.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
How We Help NRI and Expat Families
Built for Indian-American Households
We help families and business owners with ties to India and the United States understand how life insurance fits their situation.
A CPA's View of Tax and Cash Flow
We look at how premiums and policy decisions affect your budget and tax picture alongside the insurance itself.
Insurance Offered Separately
Insurance is offered through Nischay Rawal, a licensed insurance agent, separately from the firm's accounting practice.
Check Before You Assume
Do not assume a move will leave your life insurance unchanged. Review the policy contract and premium schedule with a licensed insurance agent before you relocate.


