



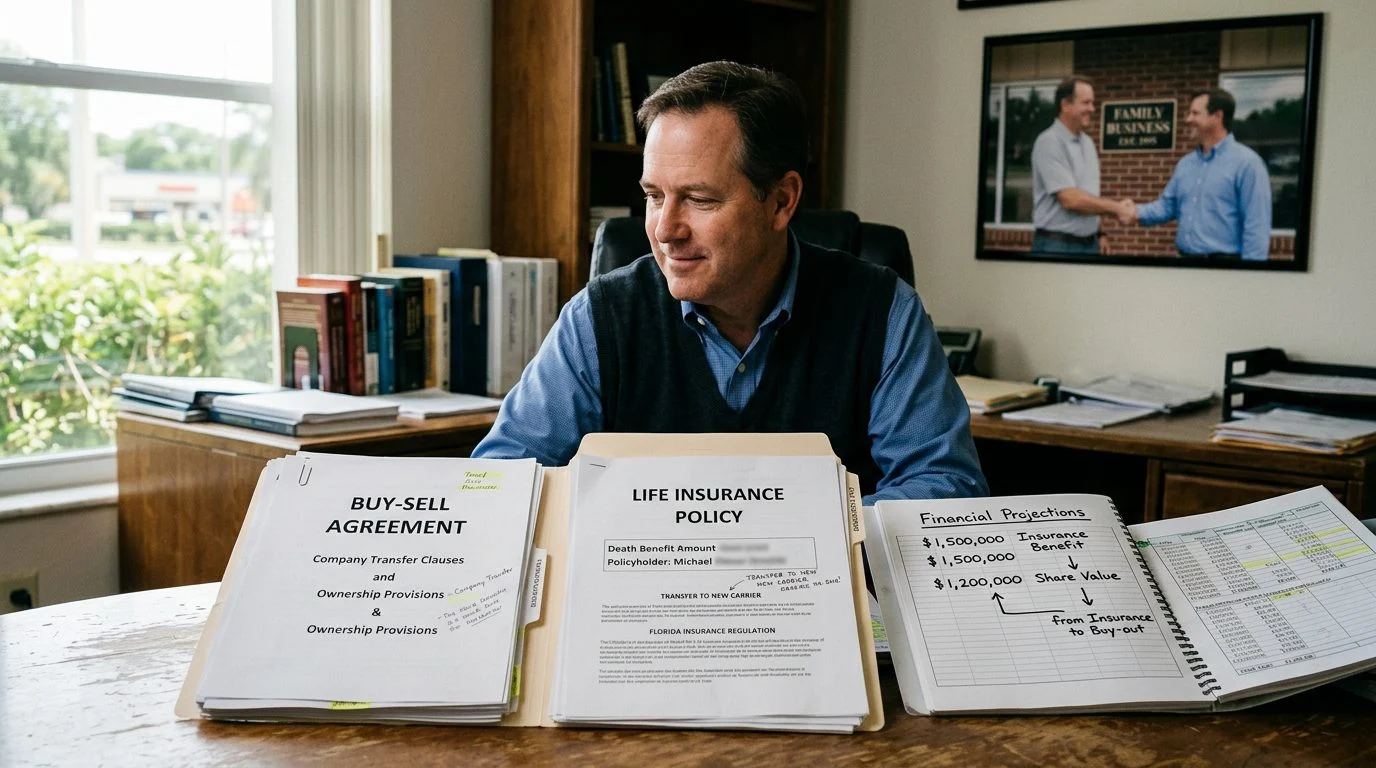
Life Insurance | Florida
Thinking About Moving Your Life Insurance to Another Company?
A CPA's view of cash flow, tax and timing, for families and business owners in Miami, Fort Lauderdale, West Palm Beach, Orlando, Tampa and Jacksonville.
What we look at before you move coverage
Your current policy
We review the benefits, premiums, cash value, loans and any surrender charges in the policy you already own.
Underwriting
Moving coverage to a new insurer usually requires a new application and health underwriting, so your current health can affect the outcome.
Timing
The sequence matters. We look at when the new coverage would take effect before any existing policy is changed.
Your household or business
Beneficiaries, ownership, and business needs such as key person or buy-sell coverage all shape the right answer.
By Nischay Rawal · Published November 7, 2026
Usually, you can’t simply move a life insurance policy to another company. Moving coverage to a new insurer normally means applying for a new policy. This page explains how to transfer life insurance to another company, what changes and what stays the same, and what to check first.
Short Answer: Moving Coverage Usually Means a New Policy
Moving coverage to a different insurer usually means applying for a new policy with that company. The old contract doesn’t follow you automatically.
The new insurer reviews your application as new business. Its health questions, your current age and its current premium rates all apply. Issue may depend on insurability, so new health conditions can change the terms you’re offered or whether you’re approved.
Your existing policy stays in force while the new application is reviewed. Don’t cancel the old policy until the new one is issued and you’ve decided to move. A gap in coverage can leave you without protection you may not be able to replace on the same terms.
If you inherited a policy or are reviewing one for a business, our team can arrange a coverage review of it with you before any change is made. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Changing the Owner or Beneficiary Is Not the Same as Changing Insurers
Changing the owner or beneficiary is a different step from changing insurers. Three roles matter here. The owner controls the contract. The insured is the person whose life is covered. The beneficiary is the person or entity who receives the death benefit.
Changing the owner, or assigning the policy, keeps the same policy with the same insurer. An assignment is a legal transfer of some or all rights in the policy. The insurer’s own form and rules govern how it’s done.
A beneficiary change is a separate instruction. It names who gets the money at death. It doesn’t move coverage to another company.
Ownership changes can also have tax and estate effects. Under 26 U.S.C. § 2042, insurance proceeds receivable by the executor are included in the gross estate whether or not the decedent held incidents of ownership in the policy at death, and proceeds receivable by other beneficiaries are included to the extent the decedent held incidents of ownership in the policy at death. Confirm the tax picture before you sign any assignment.
Ways Coverage Can Move or Change
Coverage can change in three main ways, and each follows different rules. Choose the route only after you compare the facts.
First, you can buy a new policy from a different insurer. This is the route described above. It usually includes a new application and new underwriting.
Second, you can change the owner or assign the existing policy. The coverage stays with the same insurer.
Third, some term policies can be converted to permanent coverage. Conversion is available only if the original contract includes that option. The contract sets the deadline, and the converted policy usually stays with the same insurer.
Federal tax law treats some exchanges differently. Under 26 U.S.C. § 1035(a)(1), an exchange of a life insurance contract for another life insurance contract, an endowment or annuity contract, or a qualified long-term care insurance contract is one on which no gain or loss shall be recognized, but under § 1035(c), to the extent provided in regulations, that rule does not apply to an exchange having the effect of transferring property to a person other than a United States person, and under § 1035(d)(1), exchanges that are not solely in kind are governed by the rules cross-referenced to section 1031(b) and (c).
Replacement Rules and Why They Matter
Replacing a policy means a new policy takes the place of an old one. Florida’s insurance trade practice law bars knowingly making, issuing, circulating, or causing to be made, issued, or circulated any estimate, illustration, comparison or sales presentation that misrepresents the benefits, advantages, conditions or terms of any policy. That includes estimates, illustrations, comparisons and sales presentations.
Florida law makes it unlawful to knowingly make, issue, circulate, or cause to be made or circulated any estimate, illustration, circular, statement, sales presentation, omission, or comparison that misrepresents the benefits, advantages, conditions, or terms of any insurance policy, as Fla. Stat. § 626.9541(1)(a) defines the prohibited act. A fair replacement comparison shows the old and new policies side by side.
Florida also sets disclosure duties when an agent recommends surrender. Under Fla. Stat. § 627.4553, an agent who recommends surrendering an annuity or a life insurance policy containing a cash value, without recommending that the proceeds fund or purchase another annuity or life insurance policy, must give written information before the surrender is executed. This section also applies to a person performing insurance agent activities pursuant to an exemption from licensure under this part. That information includes, but is not limited to, the estimated surrender charge, any lost minimum interest guarantees, possible tax consequences, any forfeited death benefit, and a description of any other investment performance guarantees being forfeited as a result of the transaction.
Costs and Tradeoffs to Compare Before Any Move
Compare the old policy and the new one before you change anything. Start with the old policy’s values. A surrender charge can reduce what you receive if you cancel. Ask the insurer to show guaranteed and non-guaranteed values separately.
Price the new policy at your current age and health. Premiums generally rise with age, and health questions can affect the rate or the issue decision. The new policy starts its own contestability period. Under Fla. Stat. § 627.455, a policy must be incontestable after two years from its date of issue, with listed exceptions such as nonpayment of premiums. Fla. Stat. § 627.455 reads: “Every insurance contract shall provide that the policy shall be incontestable after it has been in force during the lifetime of the insured for a period of 2 years from its date of issue except for nonpayment of premiums and except, at the option of the insurer, as to provisions relative to benefits in event of disability and as to provisions which grant additional insurance specifically against death by accident or accidental means.”
Term and permanent coverage differ. According to FINRA, term life covers a limited period, while whole or permanent life provides lifetime coverage with a cash-value feature. Term policies generally have no cash value, so cancelling one usually doesn’t return money. Learn more about whole life insurance.
Dividends on participating whole life policies are not guaranteed. Illustrations show limitations and are not guarantees of future values. FINRA’s guidance on exchanging a life policy lists surrender charges, cash value and replacement as points to weigh.
Key-Person and Buy-Sell Policies Need Extra Care
A business-owned policy is usually decided by the business, not the individual. Key person coverage is typically owned and paid for by the company, so a carrier change is a company decision. Learn more about key person insurance.
Florida law lets a business, or any affiliate or subsidiary of it, have an insurable interest in the life, body, and health of its owners, directors, officers, partners, and managers, and in its key employees or key persons, if written consent is obtained from the key employees or persons before the insurance is purchased. The business must get written consent before buying the insurance. Under Fla. Stat. § 627.404, the business also may not retaliate against a key person who refuses consent.
Buy-sell arrangements need the same care. The agreement may name the policy, its owner or how it’s funded. A change of carrier may require updating that agreement. Florida law says the insurable interest need not exist after the coverage starts. See buy-sell agreement insurance for how these policies are funded.
Review the written agreements and the tax treatment together before any change.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
When the Policy Is for Someone Else
Generally, a person may buy coverage on another person’s life only if the benefits go to the insured or to someone with an insurable interest when the contract is made. Under Fla. Stat. § 627.404, an insurable interest may rest on more than one basis, including a substantial financial advantage from the person’s continued life together with a substantial loss if that person dies, is injured or becomes disabled, a close relationship by blood or law with love and affection, or, among others, business entities, fiduciaries, charities, and plan trustees.
As a general rule, the same statute requires the person insured, having legal capacity to contract, to apply for or consent in writing to the contract and its terms on or before the time the contract is entered into. That rule has exceptions, including group life insurance and certain other policies. A person with an insurable interest may also obtain a policy on a minor under age 15. If a policy was procured without an insurable interest, the insured or the insured’s personal representative may sue to recover benefits from the person who receives them.
A spouse or adult child who manages a parent’s or partner’s policy should confirm who is the owner and who is the beneficiary. Get the contract and read those designations first. For NRI households, see NRI life insurance.
Preparing Your Questions Before Changing Coverage
Gather your documents before you decide anything. Bring the policy contract, the most recent illustration and annual statements. Note the insurer’s name and the policy form number.
Write down the current owner and beneficiary. List any loans or withdrawals taken from the policy. Note any change in health or age, since these affect the new application.
Say whether a business or buy-sell agreement is involved, and who signed it.
NR CPAs & Business Advisors is a CPA firm. Insurance is offered through a licensed insurance agent, separately from the accounting practice. Under Fla. Stat. § 473.3205, a CPA firm that accepts a commission on a product sold to a client must disclose that fact in writing. Agent compensation is disclosed in writing before any engagement.
Talk With NR CPAs About Your Policy Before You Change It
You may be holding a policy you inherited, reviewing one for a family member, or keeping one in force for a business. Changing it has lasting effects, so it helps to see the facts first.
Nischay Rawal is the responsible licensed insurance agent for this page.
Can I transfer my life insurance without a new application?
Usually not. Moving coverage to another insurer normally requires a new application and underwriting.
Does changing the beneficiary move my policy?
No. A beneficiary change names who receives the benefit, and the coverage stays with the same insurer.
Can a term policy be converted?
Sometimes. Conversion is available only if the original contract allows it, and only by the contract’s deadline.
If you’re weighing a move, contact NR CPAs & Business Advisors to arrange a coverage review of your current policy before any change is made.
Do not cancel until the new policy is in force
Cancelling or surrendering an existing policy before a replacement is approved and in force can leave you without coverage. Speak with us first so the comparison is complete.
How a coverage review works
1. Share your current policy
Bring the policy, its most recent annual statement and your goals so we can see what you have today.
2. Compare the numbers side by side
Premiums, face amount, cash value and loan terms are shown next to the proposed policy, with every limitation and exclusion stated.
3. Plan the timing and taxes
We map cash flow, tax considerations and the order of steps so that no coverage lapses by accident.
4. Apply only if it makes sense
If a move is recommended, the application and replacement forms are completed with the licensed agent. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from our accounting practice.


