



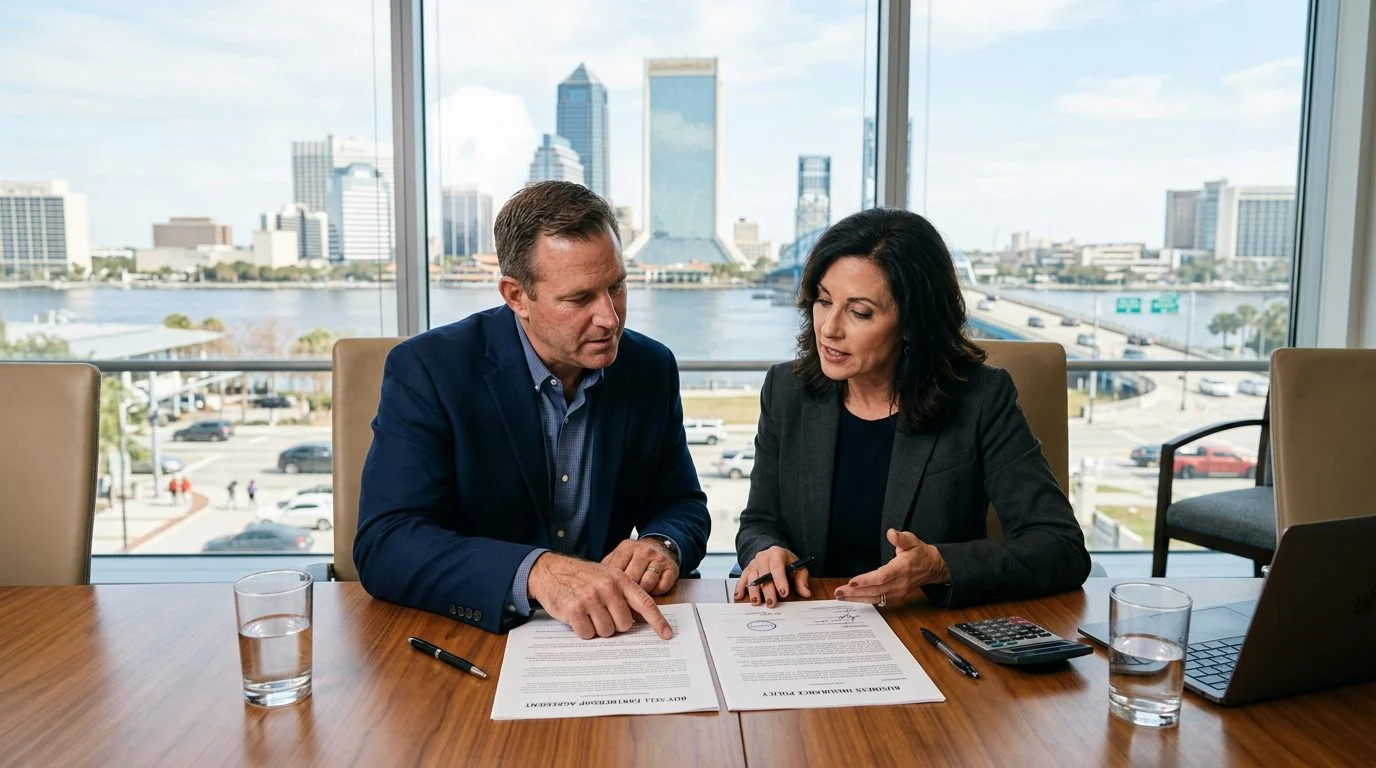
Buy-Sell Agreement Insurance | Jacksonville, FL
Fund Your Owner Buyout With Life Insurance in Jacksonville
Buy-sell agreement insurance can provide the cash a buyout requires when an owner dies. NR CPAs & Business Advisors helps Jacksonville business owners plan the funding alongside a CPA's view of tax and cash flow. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from the accounting practice.
By Nischay Rawal · Published October 20, 2026
Buy-Sell Agreement Insurance Jacksonville: Funding an Owner Buyout with Life Insurance
Buy-sell agreement insurance is a life insurance policy that provides the cash to buy a deceased owner’s share of a business. A buy-sell agreement sets the buyout terms, and life insurance can pay the money when the buyout is due. This page explains buy-sell agreement insurance Jacksonville business owners should understand before a buyout is needed. Our office is in Miami. Insurance is offered by Nischay Rawal, a licensed insurance agent, separately from our accounting practice at NR CPAs & Business Advisors.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Why Jacksonville business owners fund buy-sell agreements with life insurance
A buy-sell agreement sets the terms for buying an owner’s share when that owner dies, becomes disabled, retires, or leaves. The hard part is cash. A buyout often comes due at the worst moment, and a business rarely keeps that much money in its everyday accounts. Life insurance is one common way to have the cash ready. The agreement and the policy are separate documents, so their terms must match. If your co-owners are relatives, long-time partners, or colleagues in a Jacksonville company, the details matter even more. Some owners assume they will sort out the details later. Written terms prevent that guesswork. Our team reviews how the buyout would actually be paid, not only the policy. For the general framework, read our buy-sell agreement life insurance guide.
What a buy-sell agreement needs to work
A buy-sell agreement works when it names the triggers, sets the price, and says how the buyout gets paid. Common triggers include death, disability, retirement, divorce, and voluntary exit. Each trigger should be defined in plain words, so everyone knows which event starts a buyout. Price is usually set one of three ways: a fixed number, a formula, or an outside appraisal at the time of the buyout. A fixed number can fall behind what the business is worth, so it needs review as the business changes. Federal estate tax rules define the value of a business interest as the net amount a willing buyer would pay a willing seller, with neither under any compulsion to buy or sell and both having reasonable knowledge of the relevant facts. See the federal valuation rule for business interests. Decide the funding plan while you write the agreement, not after a policy is issued.
Cross-purchase or entity redemption: how the policy is owned
A cross-purchase plan has each owner buy a policy on the other owners. An entity redemption plan has the business buy a policy on each owner. In a cross-purchase, the surviving owners buy the deceased owner’s share directly. In an entity redemption, the company buys back the share. The difference shows up in the paperwork and the policy count. With two owners, a cross-purchase needs two policies. With three owners, it needs six, because each owner holds a policy on each of the other two. An entity plan needs one policy per owner, held by the company. Ownership shifts as owners age or leave, so the policy owner and beneficiary need review each time the group changes. Florida law also sets rules for the agreement itself. See Fla. Stat. § 607.0732.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Tax and cash-flow points a CPA reviews
Federal law generally denies a deduction for life insurance premiums when the taxpayer is directly or indirectly a beneficiary of the policy. See IRC § 264. See IRC § 101. Interest is a separate issue. If proceeds are held under an agreement to pay interest, that interest is included in gross income. Section 101 also covers reportable policy sales, where someone with no family, business, or financial tie to the insured buys an interest in the policy. Moving an existing policy between owners can change the tax result, so plan any transfer before it happens. Life insurance proceeds paid by reason of the insured’s death are generally excluded from gross income under IRC § 101, but for a business-owned policy on an employee the exclusion can be limited to the premiums and other amounts the business paid, and a transfer of the policy for value can also limit it; whether proceeds count in the taxable estate is a separate question under IRC § 2042. Under IRC § 2042, the gross estate includes insurance receivable by the executor. It also includes, to the extent of the amount receivable by other beneficiaries, insurance under policies on the decedent’s life in which the decedent possessed incidents of ownership at death, alone or with another person; a reversionary interest counts as an incident of ownership only if its value exceeded 5 percent of the policy’s value immediately before death. Premiums are a fixed cost, so budget them against the buyout the policy is meant to fund. Tax results depend on the facts of the owners, the policy, and the entity. A CPA reviews those facts during the coverage review.
Term and permanent coverage for a buyout that may last for years
Term life insurance covers a set number of years. Whole life insurance is meant to last for the insured’s life, as long as premiums are paid. Term can match the years a buyout is most likely to be needed. Its renewal terms and any age-based premium changes are stated in the policy, and they affect the cost after the term ends. Whole life includes cash value. The policy shows guaranteed values and non-guaranteed values separately. Dividends, where the insurer offers them, are not guaranteed. Policy illustrations are estimates, and the insurer’s actual values can differ. Some owners pick one type, some combine them, and some change the plan as the business changes. The choice should follow the agreement’s terms and the business’s plans. It should not follow a sales pitch.
Key-person coverage and the business’s own losses
Key-person insurance is a policy the business owns on an essential owner or employee. It helps the company manage the financial effect of losing that person. It is separate from the buyout. A business that depends on one or two people can use key-person coverage and buy-sell coverage together. The buy-sell policy funds the purchase of an owner’s share. The key-person policy supports the company itself. Florida law limits who a business may insure. A business has an insurable interest in the life, body, and health of its owners, directors, officers, partners, and managers, or of any affiliate or subsidiary of the business, or of key employees or key persons, when written consent is obtained from those key employees or persons before the insurance is bought. See Fla. Stat. § 627.404. Under Fla. Stat. § 627.404, a business entity, or its affiliate or subsidiary, may not retaliate or take adverse action against any key employee or key person who does not consent to the issuance of insurance on that person’s life, and the business’s insurable interest depends on obtaining that person’s consent in writing before the insurance is purchased. Review both policies with the agreement, because they may serve different goals.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Who handles the coverage and how a coverage review works
Nischay Rawal acts as a licensed insurance agent in Florida and offers the insurance. Our team, which includes assistants and office staff, helps schedule and organize the coverage review. Florida law requires an insurance agent to be licensed and appointed before acting as one. See Fla. Stat. § 626.112. Insurance is offered separately from our accounting practice. The coverage review starts with your buy-sell agreement, the owners’ ages and health, and the business’s valuation. It also covers the ownership structure and the cash-flow picture. From there, we compare funding options side by side. Any commission Nischay Rawal earns on a policy is disclosed to you in writing before the engagement. A CPA firm’s commission disclosure rule is set out in Fla. Stat. § 473.3205.

Talk with us about your buy-sell agreement
A buy-sell agreement is only as useful as its funding plan, so the cash should be lined up before a buyout event happens.
How does life insurance fund a buy-sell agreement?
The policy pays a death benefit to the owner or business that agreed to buy the share. That cash then pays for the buyout.
Is the death benefit taxable?
Interest on proceeds held under an agreement to pay later is taxable. See IRC § 101.
If an owner’s death or exit would leave your co-owners short on cash, call us today for a coverage review. In your coverage review, we’ll go over the buy-sell agreement and the funding plan with you. Contact NR CPAs & Business Advisors.
How Life Insurance Supports a Buy-Sell Agreement
A death benefit for the buyout
When an insured owner dies, the policy pays a death benefit to the owner or business named to buy the share. That cash can be used to complete the buyout under the agreement.
Ownership matches the agreement
Who owns and who is insured should follow the buy-sell agreement's structure, whether it is a cross-purchase plan or an entity redemption plan.
Cash flow in view
Premiums are a business or personal cash flow decision. We review how they fit with the rest of your financial picture before any policy is discussed further.
Planning for the people involved
A funded agreement can give surviving owners and the family of a departed owner a clear, prearranged process for the transition.
Review the Agreement and the Funding Together
Life insurance funds a buyout, but it does not replace a well-drafted buy-sell agreement. Valuation terms, payment terms and ownership details should be reviewed alongside the policy so the funding and the agreement work together.
Common Funding Structures to Review
Cross-purchase plan
Each owner buys and owns a policy on the other owners. Review how the number of policies and premiums affects cash flow as ownership changes.
Entity redemption plan
The business owns policies on each owner and uses the proceeds to redeem a departing owner's shares. Review how the policies interact with company cash and the agreement's terms.
Combined approach
Some businesses use a mix of structures. Review how each approach fits the agreement's terms and the business's goals.


