



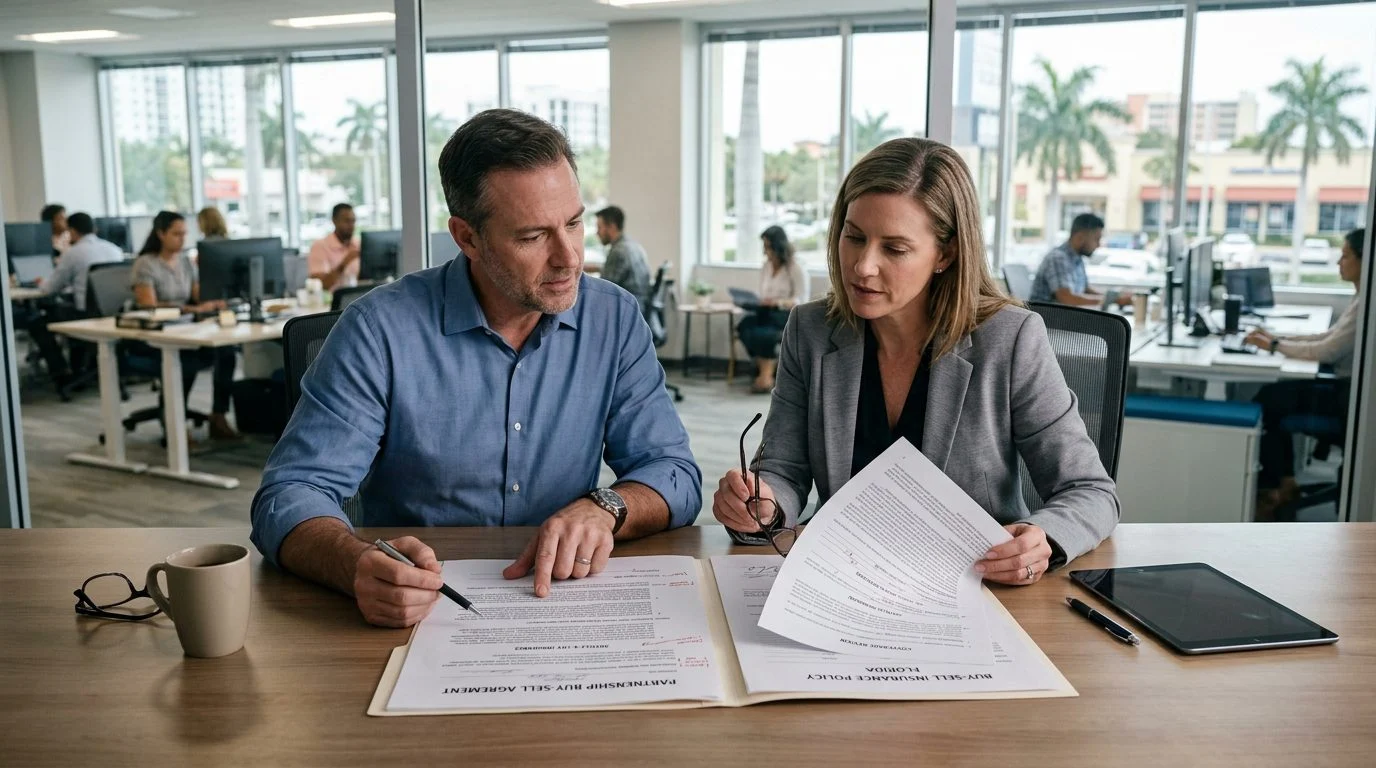
Buy-Sell Agreement Insurance | Florida
Plan Ownership Changes Before They Happen
Life insurance can be one way to fund a buy-sell agreement.
By Nischay Rawal · Published October 15, 2026
A buy-sell agreement is a contract that sets the terms for buying out an owner’s share of a business when a set event happens. Life insurance is one common way to fund that buyout. This page explains how the pieces fit together in Florida and what to check before you rely on them.
What a Buy-Sell Agreement Is and Who It Is For
A buy-sell agreement is a contract among business owners. It names the events that trigger a buyout, such as death, disability, retirement, departure, divorce or a sale to an outsider. The triggers and the price depend on how the agreement is written.
Florida recognizes shareholder agreements that follow Fla. Stat. § 607.0732. That section requires the agreement’s existence to be noted conspicuously on share certificates or on the information statement for uncertificated shares.
Partnerships have a default rule too. When a partner leaves without ending the partnership, Fla. Stat. § 620.8701 requires the partnership to buy that partner’s interest at a buyout price set by statute.
This arrangement fits co-owners of closely held Florida companies, family-owned businesses, professional practices and partnerships with more than one owner. Ask three questions: who buys, at what price, and how the money gets paid. Life insurance is one answer to the last question. The agreement itself is a legal document, and this page is general information, not tax or legal advice.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
How Life Insurance Funds a Buy-Sell Agreement
Life insurance can provide money to complete a buyout when an insured owner dies. The two most common structures are cross-purchase and entity redemption.
- Cross-purchase: each owner owns a policy on the other owners. Ownership and beneficiary choices must match the agreement’s terms.
- Entity redemption: the business owns and pays for a policy on each owner. The business may use the proceeds to buy back the interest, subject to the agreement and the policy.
- Hybrid approaches also exist. The right structure depends on the entity type, the number of owners and the agreement’s wording.
Florida limits who can insure whom. A business entity may insure an owner or key person only if that person consents in writing before the insurance is bought. The entity may not retaliate against someone who refuses (Fla. Stat. § 627.404).
Tax results depend on the policy, the business structure and the individual’s circumstances, and exceptions apply. Premium deductibility and the tax treatment of a death benefit are not automatic. Estate inclusion can also turn on ownership. Under IRC § 2042, insurance payable to other beneficiaries can be included in the gross estate if the decedent held incidents of ownership at death. This is general information, not tax advice.
Permanent policies may build cash value under the contract. That value includes guaranteed and non-guaranteed amounts.
What the Policy Covers and What to Check
Check that the insured owner, the policy owner, the beneficiary and the policy amount all match the agreement’s purpose.
- Price method. Agreements set price by formula, appraisal or fixed value. For federal estate tax purposes, a decedent’s interest in a business, such as a partnership or a proprietorship, is valued at the net amount a willing buyer would pay a willing seller, with neither one compelled to act and both reasonably informed of the relevant facts. That net value rests on all relevant factors, including a fair appraisal of the business’s tangible and intangible assets (goodwill among them) as of the valuation date and the business’s demonstrated earning capacity (Treas. Reg. § 20.2031-3).
- Stale values. If the agreed value has not been updated, the policy amount may not match the buyout price.
- Insurability. Health questions are required. Issue may depend on insurability, and the insurer decides that through underwriting.
- Starting point only. Some owners begin with a valuation-based figure or an income-based estimate. That is a rough starting point, not the amount your business needs. The right amount depends on what the agreement must fund.
- Future changes. Any later increase in coverage depends on insurability and circumstances at that time. No increase is assured.
- Policy loans. A loan can reduce cash value and the death benefit. Under Fla. Stat. § 627.458, if loan debt reaches the loan value, the policy may end, but only after at least 30 days’ notice. That section does not apply to term policies.
- Premiums. Premiums depend on the insurer, the policy, underwriting and individual circumstances. This page gives no premium figures.
What to Expect: From First Contact to a Funded Policy
The process runs from a coverage review to documents, insurer selection, application and underwriting. Timing depends on the insurer, and no timeline is guaranteed.
- First contact. Describe the business, the owners and any existing agreement.
- Coverage review. Nischay Rawal reviews ownership, the valuation method and the funding structure.
- Documents. Gather entity papers, ownership percentages, current valuations and owner details that underwriting may request.
- Illustrations. Illustrations show guaranteed and non-guaranteed amounts. Dividends, where a policy pays them, are not guaranteed. We review illustrations with you directly.
- Application. Health questions are required, and medical requirements may apply. The insurer decides issue through underwriting.
- Plan on another review when ownership or values change.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
How NR CPAs & Business Advisors Approaches Buy-Sell Funding
NR CPAs & Business Advisors is a Miami CPA firm that advises business owners on tax and cash-flow questions. The firm also helps families and owners review life insurance.
Insurance is offered by Nischay Rawal, a licensed insurance agent, separate from the firm’s accounting practice. Florida law allows a person to act as or advertise as an insurance agent only when currently licensed and appointed (Fla. Stat. § 626.112).
Our team includes assistants and office staff. Insurance agents may receive commissions. A CPA firm that accepts a commission for a product sold to a client must disclose that in writing (Fla. Stat. § 473.3205). We offer no rebates or other inducements to buy.
This page and the coverage review are general information. Ownership, valuation and funding choices depend on your specific facts.
Common Questions About Buy-Sell Agreement Insurance
Does life insurance have to fund a buy-sell agreement?
No. Life insurance is one common method. Other funding approaches exist, and the right choice depends on the business.
How much coverage should a buy-sell policy have?
No single figure fits every business. A valuation-based or income-based number is only a starting point that depends on what the agreement must fund.
What if an owner’s health changes after signing?
Issue and premiums depend on underwriting when you apply. Health changes can affect whether a policy can be issued.
Is the death benefit taxable?
Tax treatment depends on the policy, the business structure, exceptions and individual circumstances. This is general information, not tax advice.
Can I borrow against the policy?
A loan can reduce cash value and the death benefit. Terms depend on the policy and the insurer.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Start Your Buy-Sell Coverage Review
If your buy-sell agreement is signed but no matching life insurance is in place, or an owner has joined or left, a coverage review is the next step. Call us today or use the contact page to request one with Nischay Rawal. Owners in Miami, Fort Lauderdale, West Palm Beach, Orlando, Tampa and Jacksonville can reach us the same way.
Insurance is offered through Nischay Rawal, a Florida-licensed insurance agent, separate from the accounting practice. Coverage, premiums and benefits depend on the issuing insurer’s underwriting and the policy’s terms. Florida law (Fla. Stat. 626.99(4)) provides a 14-day review period for life insurance policies. How that period applies to a particular policy depends on the issuing insurer’s policy terms. This page is general information, not tax advice.
Questions to Bring to Your Coverage Review
Is life insurance the right funding method?
Life insurance is one common method for funding a buy-sell agreement. Other funding approaches exist, and the right choice depends on the business, its owners and the terms of the agreement.
How much coverage should a policy provide?
No single figure fits every business. A valuation-based or income-based number is only a general starting point, and the right amount depends on what the agreement needs to cover.
Who should own and be named on the policy?
Ownership and beneficiary arrangements depend on the buy-sell agreement, the policy terms and the insurer's underwriting. We review these details with you before any decision is made.
How are premiums and tax treatment handled?
Premium costs and tax treatment depend on the insurer, the policy, the business structure and your individual circumstances. This is general information, not tax advice.
What We Review With You
Owners and key people
We consider how the ownership interests, the people involved and their roles in the business affect the funding approach.
Coverage options
We explain the differences between term life insurance and whole life insurance in plain words, along with the limitations that apply to each.
Insurance Disclosure
Coverage, premiums and benefits depend on the issuing insurer's underwriting approval and the policy terms.


