When Does Your Business Need a CFO?


Your business needs a CFO when financial decisions start affecting growth and you no longer have the data, systems, or expertise to make them confidently. For most companies, that tipping point arrives once annual revenue crosses $1 million to $2 million. At that stage, cash flow becomes harder to predict, tax obligations grow more complex, and important business decisions like hiring, expanding, or raising capital need real financial analysis behind them, not guesswork.
The good news is you do not have to hire a full-time executive right away. Many growing businesses get CFO-level support through a fractional or virtual model at a fraction of the cost. This article walks through the signs that your business has outgrown basic bookkeeping, the revenue stages where CFO support makes the most sense, and how to choose the right type of financial leadership for where your company is right now.
At What Stage Do You Need a CFO?
You need a CFO at the stage when your financial operations become too complex for a bookkeeper or accountant to manage alone. That stage typically arrives when your business reaches $1 million to $2 million in annual revenue and the number of financial decisions you face each week starts to outpace your ability to make them with clear data.
According to SCORE (the Service Corps of Retired Executives), 82% of small businesses that fail do so because of cash flow problems. That is not a failure of effort or ambition. It is a failure of financial visibility. A bookkeeper records what happened. An accountant makes sure the records are accurate and compliant. But neither role is designed to look forward. A CFO uses your financial data to build forecasts, plan for growth, and guide the business toward better decisions.
The New York Times has reported that outsourced CFO services become necessary once a company hits $2 million in annual revenue. According to Driven Insights, companies in the $500,000 to $50 million revenue range are strong candidates for virtual or fractional CFO services. And according to Bennett Financials, most companies transition from fractional to full-time CFO support between $15 million and $30 million in revenue, when operational complexity and team size demand daily executive attention.
The takeaway is simple. If your business is past the startup phase and you are making financial decisions without solid forecasts, cash flow projections, or strategic guidance, you are likely already at the stage where a CFO adds real value.
What Size Business Needs a CFO?
The size of business that needs a CFO is typically any company generating $1 million or more in annual revenue that faces growing complexity in cash flow, taxes, compliance, or strategic planning. The type of CFO, whether virtual, fractional, or full-time, depends on how large and complex the business has become.
According to Coonen Law and multiple industry experts, businesses generating between $1 million and $10 million in annual revenue are in the sweet spot for fractional CFO services. Below $1 million, a good bookkeeper and accountant can usually handle the workload. Above $10 million, the decision shifts toward whether you need a more dedicated fractional engagement or a full-time hire. Most experts point to $50 million in annual revenue as the threshold where a full-time CFO becomes essential.
Data from the U.S. Bureau of Labor Statistics shows that roughly 20% of small businesses fail within their first year, and nearly 50% fail by the fifth year. Many of those failures trace back to financial management problems that a CFO could have helped prevent. A virtual CFO fills that gap without the six-figure salary commitment, giving smaller businesses access to the same strategic thinking that larger companies rely on every day.
Can a Business Operate Without a CFO?
Yes, a business can operate without a CFO, but only up to a certain point. Very small businesses with simple finances, low transaction volume, and predictable cash flow can get by with a bookkeeper and a CPA. Once the business starts growing, though, operating without CFO-level support creates blind spots that compound over time.
According to a JPMorgan Chase Institute study, the median small business holds only 27 days of cash buffer. That leaves almost no room for error. Without someone looking ahead at cash flow trends, seasonal dips, or the financial impact of a new hire, a single bad month can put the entire business at risk. A University of North Dakota study found that approximately 90% of small business failures are due to internal causes, including inadequate financial management.
A bookkeeper tells you where your money went. An accountant makes sure your taxes are filed correctly. But neither one is designed to answer questions like "Can we afford to hire three people next quarter?" or "What happens to our cash position if this client pays late?" Those are CFO-level questions. If you find yourself making those calls based on gut feeling instead of data, your business has outgrown its current financial setup.
Can a Small Business Have a CFO?
Yes, a small business can have a CFO, and thanks to the fractional and virtual CFO model, it has never been more affordable. You do not need to be a Fortune 500 company to get executive-level financial guidance. A fractional CFO works part-time with your business, typically 5 to 20 hours per month, and charges a fraction of what a full-time hire would cost.
According to data compiled by WifiTalents, small to mid-sized businesses can save up to 60% in overhead costs by hiring a fractional CFO instead of a full-time executive. Monthly retainers typically range from $3,000 to $10,000, compared to a full-time CFO salary that averages $437,000 per year according to Salary.com, with total compensation packages reaching nearly $790,000 when you add benefits, bonuses, and retirement.
According to NOW CFO, over one-third of U.S. small businesses now outsource at least one core operation, and finance and accounting is the most commonly outsourced category. The fractional CFO model is not a compromise. It is the most practical way for a small business to get the financial leadership it needs without overextending its budget. Smart tax-saving strategies combined with ongoing financial oversight can pay for the CFO engagement many times over.
Is a CFO Worth It for a Small Company?
Yes, a CFO is worth it for a small company. The return on investment goes far beyond the monthly fee. A CFO helps you stop the cash leaks you cannot see, plan taxes proactively instead of reactively, and make growth decisions with confidence instead of guesswork.
Data from Gitnux shows that companies using fractional CFOs saw profit margins expand by 12% to 18% on average in their first year of engagement. Investor confidence scores rose 40% after a fractional CFO engagement, and forecasting accuracy hit 95% with the right tools and systems in place. Strategic pricing reviews by CFOs led to a 5% increase in total revenue without acquiring a single new customer.
The cost of not having a CFO is often much higher than the cost of hiring one. According to Preferred CFO, the average company wastes approximately $135,000 per year on unused software subscriptions alone. A CFO identifies those kinds of leaks immediately. Businesses in the Miami area and beyond that we work with often discover that tax planning alone produces savings that exceed the cost of the CFO engagement.
When Should a Company Hire a CFO?
A company should hire a CFO when financial decisions become too frequent and too impactful to manage without dedicated financial leadership. Specific triggers include revenue crossing $1 million to $3 million, cash flow becoming unpredictable, fundraising or investor conversations starting, or the business preparing for a major transition like a merger, acquisition, or new market entry.
According to Pacific Accounting and Business Services, the key inflection points are when revenue crosses $3 million to $5 million and complexity outpaces what a controller can handle, when investors start asking questions your team cannot answer, or when compliance requirements increase due to expansion or new regulatory thresholds.
Russell Reynolds Associates reported that CFO turnover globally hit a seven-year high in 2025, with 316 new CFOs appointed worldwide. Among S&P 500 companies, turnover hovered between 17% and 17.8% for four consecutive years. This instability at the top is one reason more small and mid-sized companies are turning to fractional models first. You get proven financial expertise with a much shorter ramp-up and zero risk of a costly executive departure six months later.
How Much Does It Cost to Get a CFO?
The cost to get a CFO depends on whether you hire full-time, fractional, or virtual. A full-time CFO in the United States earns an average base salary of $261,533 per year according to ZipRecruiter as of 2026, with total compensation packages reaching $400,000 to $500,000 or more once you include benefits, bonuses, and payroll taxes.
A fractional or virtual CFO costs between $3,000 and $15,000 per month depending on the scope of work. According to Bennett Financials, early-stage startups need 8 to 10 hours of monthly support at $1,400 to $2,800 per month. Businesses in the $2 million to $10 million revenue range typically pay $5,000 to $10,000 per month for 20 to 40 hours of CFO support. That is 60% to 70% less than the cost of a full-time hire.
There are also hidden costs to hiring full-time that most business owners forget. Recruitment fees can equal 30% of the first year's salary. Benefits and payroll taxes add another 25% to 40% on top of the base. The average time to recruit a director-level finance hire is 90 days, and for a VP-level role it can take 120 to 180 days according to Staffing Soft. A virtual CFO can start delivering value within days. Every week you spend without financial leadership is a week of missed opportunities and unmanaged risk. Strong financial reporting is the foundation that makes all of this work.
What Are the 4 Roles of a CFO?
The four roles of a CFO are steward, operator, strategist, and catalyst. These four roles were originally defined by Deloitte and remain the standard framework for how modern CFOs create value inside a business.
Steward
As steward, the CFO protects the company's assets, maintains compliance with financial regulations, and makes sure the business meets its reporting obligations. This includes overseeing accurate financial statements, managing audits, and keeping the company out of trouble with the IRS or other regulatory bodies. Businesses dealing with complex compliance situations often benefit from IRS tax resolution support as part of this function.
Operator
As operator, the CFO runs the finance function efficiently. That means managing the accounting team, building financial systems, implementing automation tools, and making sure that financial data flows accurately and on time. According to a 2025 Gartner survey, 98% of finance functions have invested in digitization and automation, but most report that only one-quarter or less of their processes actually use digital tools. A strong CFO closes that gap.
Strategist
As strategist, the CFO shapes the long-term direction of the business through financial analysis, scenario modeling, and growth planning. They answer questions like "Should we expand into a new market?" or "Can we afford this acquisition?" According to Gartner, 47% of finance leaders cite enterprise growth strategy as a top priority, making this one of the most important functions a CFO serves.
Catalyst
As catalyst, the CFO drives change across the organization. They push the business to adopt new technologies, improve processes, and align financial strategy with the overall vision. According to a PwC CFO Pulse Survey, nearly 60% of CFOs say they are dedicating more time to technology investment and implementation compared to a year ago. This role is about moving the business forward, not just keeping score.
What Does a CEO Want Out of a CFO?
A CEO wants a CFO who can translate financial data into clear, actionable business decisions. The CEO does not need another person to present spreadsheets. They need a financial partner who can answer the question "What should we do next?" with data and confidence.
According to Gartner's CFO Leadership Vision report, profits lost due to financially unsound operating decisions currently equal approximately 3% of EBITDA. That means CEOs who do not have strong CFO support are leaving real money on the table with every decision they make. A good CFO prevents those losses by providing the financial analysis behind every major move.
CEOs also want a CFO who can manage investor and lender relationships. According to the Kauffman Foundation, 83% of entrepreneurs do not access bank loans or venture capital at the time of startup. A CFO who can prepare investor-ready financials, build compelling financial models, and anticipate due diligence questions shortens the fundraising timeline and improves the outcome. At our firm, we see this play out regularly through our startup advisory work.
Does a CFO Report to a CEO?
Yes, a CFO reports to the CEO. The CFO is a C-suite executive whose primary reporting relationship is directly to the chief executive officer. In publicly traded companies, the CFO may also have a reporting obligation to the board of directors, especially on matters related to financial reporting, compliance, and audit oversight.
In small and mid-sized businesses, the reporting structure is usually simpler. The CFO works alongside the CEO as a strategic partner, providing the financial analysis and forecasting that supports every major business decision. The relationship works best when the CEO focuses on vision and growth while the CFO provides the financial reality check, the scenario modeling, and the risk assessment that keeps the company on solid ground.
In a virtual or fractional CFO arrangement, the dynamic is the same. The virtual CFO reports to the founder or CEO and integrates with the existing leadership team. They attend strategy meetings, review financial performance, and advise on major decisions just like an in-house CFO would. The only difference is the time commitment and the cost structure.
Bookkeeper vs Accountant vs CFO, and When You Need Each
Understanding the difference between a bookkeeper, an accountant, and a CFO is critical because hiring the wrong level of financial support at the wrong stage wastes money and creates blind spots. Each role builds on the one before it.
RolePrimary FunctionWhen You Need OneTypical Revenue StageBookkeeperRecords transactions, manages invoices, reconciles accountsYou cannot keep up with daily financial record-keeping yourself$0 to $500,000+Accountant / CPAPrepares tax returns, ensures compliance, interprets financial statementsTax complexity grows, you need financial statements and regulatory compliance$250,000 to $2 million+Fractional / Virtual CFOForecasting, cash flow strategy, financial modeling, growth planningYou are making big decisions without clear financial data or projections$1 million to $50 millionFull-Time CFODaily financial leadership, team management, investor relations, complex complianceFinancial operations require 40+ hours of dedicated executive attention per week$50 million+
Sources: SCORE, Driven Insights, Bennett Financials, The New York Times, Robert Half
According to SCORE, the progression from bookkeeper to controller to fractional CFO to full-time CFO follows the growth trajectory of the business. Each new role adds a layer of strategic capability. The bookkeeper records. The accountant verifies and reports. The controller oversees systems and processes. The CFO turns all of that information into strategy. Businesses that try to skip levels, like asking a bookkeeper to forecast cash flow or expecting a CPA to build a growth model, end up with gaps that cost them money.
Why Does 90% of Startups Fail?
Ninety percent of startups fail because of a combination of factors, but the most common and preventable cause is running out of money. According to SCORE, 82% of small business failures trace back to cash flow problems. A CB Insights analysis of over 300 failed startups found that 38% failed specifically because they ran out of cash or could not raise new funding.
A separate Harvard Business School study found that 42% of small business closures were due to a lack of market demand for the product or service. But even among businesses that do have strong demand, poor financial management can destroy what would otherwise be a successful company. According to one analysis, approximately 80% of mid-market business failures were linked to rapid growth outstripping the company's financial controls.
These numbers point to a clear pattern. It is not that founders lack ambition or talent. It is that they lack financial leadership at the exact moment they need it most. A CFO, even a part-time one, can spot a cash crisis months before it arrives. They can build the financial models that show whether a growth plan is sustainable or reckless. Working with a business consultant who understands your financials at a strategic level can be the difference between scaling successfully and becoming a statistic.
Can an LLC Have a CFO?
Yes, an LLC can have a CFO. There is no legal requirement that restricts the CFO title to corporations. An LLC can appoint any officer title it chooses, including CEO, CFO, COO, or any other designation, as long as it is documented in the operating agreement.
In practice, most LLCs that hire a CFO do so through a fractional or virtual arrangement rather than a full-time hire. The LLC structure is common among small and mid-sized businesses, and these companies typically fall within the revenue range where fractional CFO services provide the best value. Whether the business is structured as an LLC, S-Corp, C-Corp, or partnership, the need for financial leadership is determined by the complexity of the business, not the legal entity type. Choosing the right structure is an important decision that often benefits from professional guidance during business formation.
Signs Your Business Has Outgrown Its Current Financial Setup
There are clear, measurable signs that your business has outgrown its current financial setup and needs CFO-level support. If you recognize more than one of these patterns, it is probably time to bring in a financial leader.
You are making major business decisions based on gut feeling instead of data. Decisions about hiring, pricing, expansion, and capital allocation should be backed by financial analysis, not instinct. If you are regularly guessing at these answers, you need a CFO.
Your cash flow feels unpredictable. According to the JPMorgan Chase Institute, the median small business holds only 27 days of cash reserves. If you do not know your cash position 90 days out with reasonable accuracy, you are operating blind. A CFO builds cash flow forecasts that give you visibility and control. Tracking the right financial metrics on a weekly and monthly basis is the foundation of that visibility.
You are growing but profits are not keeping pace. Revenue growth without margin growth is a red flag. A CFO digs into the numbers to find out which products or services are profitable and which ones are dragging the business down. According to data compiled by WifiTalents, companies using fractional executives see a 15% reduction in wasted operational spending within the first six months.
Your accountant or bookkeeper is stretched thin. If your financial team is spending all their time on transactions and compliance, nobody is looking ahead. According to Gartner, over 70% of CFOs now handle responsibilities beyond finance, including technology investment, data analytics, and strategic planning. Your bookkeeper should not be expected to fill that role.
You are preparing for a major event. Fundraising, acquisitions, new market entry, or preparing the business for sale all require financial modeling and analysis that only a CFO provides. If any of these are on your horizon, the time to bring in a virtual CFO is now, not after the process has already started. Strong strategic planning at this stage makes every step that follows smoother.
Frequently Asked Questions
How Much Does a CFO Charge Per Hour?
A CFO charges between $125 and $500 per hour depending on whether the role is full-time or fractional. According to ZipRecruiter, the average hourly rate for a full-time CFO in the United States is approximately $125.74 as of 2026. Fractional and virtual CFOs typically charge between $200 and $500 per hour, according to industry data from WifiTalents, reflecting the specialized, on-demand nature of their work.
How Much Should a CFO Be Paid?
A CFO should be paid based on company size, revenue, and the scope of financial responsibilities. According to Robert Half's 2026 salary data, CFOs with at least 10 years of experience earn an average of $195,500 at the lowest tier, $269,750 for mid-tier, and $321,750 for top-tier positions. Total compensation packages at larger companies can exceed $1 million when you include bonuses, equity, and benefits.
What Are the Top 3 Priorities for a CFO?
The top three priorities for a CFO are cash flow management, long-term financial planning, and supporting enterprise growth strategy. According to Gartner's 2025 CFO Priorities survey, 55% of CFOs now rank long-term planning and resource allocation as their top priority. Enterprise growth strategy is cited by 47% of finance leaders. Cash flow management remains the foundation of every other priority because, as SCORE data shows, 82% of small businesses that fail do so because of cash flow problems.
Who Has More Power, the CEO or the CFO?
The CEO has more power than the CFO. The CEO is the highest-ranking executive in the company and has final authority over all major business decisions. The CFO reports to the CEO and provides the financial analysis, risk assessment, and strategic insight that informs those decisions. While the CFO has significant influence, especially over financial strategy and compliance, the ultimate decision-making authority rests with the CEO.
Does a Small Business Need a CFO?
A small business needs a CFO once its financial operations become too complex for a bookkeeper and accountant to handle alone. According to experts cited by SCORE and The New York Times, that point typically arrives at $1 million to $2 million in annual revenue. A fractional or virtual CFO gives small businesses the same strategic financial guidance that large companies get from a full-time executive, but at 60% to 70% less cost.
Is It Hard to Get Your CFO?
It is not hard to get a CFO if you use a fractional or virtual model. Traditional full-time CFO recruiting can take 90 to 180 days according to industry estimates, and it can take another 6 to 12 months for the new hire to reach full productivity. A virtual CFO, on the other hand, can be onboarded in days or weeks and begins delivering strategic value almost immediately. The fractional model removes the recruitment risk, the long timeline, and the high fixed cost that make full-time hiring difficult for smaller companies.
The Takeaway
Every growing business reaches a point where the financial decisions in front of it outpace the financial support behind it. That is the moment you need a CFO. For most companies, that point comes well before they can afford a full-time executive hire. The fractional and virtual CFO model exists specifically to close that gap, giving businesses of all sizes access to the kind of financial leadership that prevents cash flow crises, strengthens performance, and creates a real plan for sustainable growth.
If you are at that inflection point, or think you might be getting close, NR CPAs & Business Advisors can help you figure out the right next step. Call us at (305) 978-1533 to talk through your situation.


Tax and Financial Insights
by NR CPAs & Business Advisors

Is Section 179 Going Away in 2026 and How Is It Calculated?
No, Section 179 is not going away. It has been a permanent part of the Internal Revenue Code since the PATH Act of 2015 removed its expiration date, and the One Big Beautiful Bill Act raised its limits rather than reducing them. For tax years beginning in 2026, the Section 179 deduction limit is $2,560,000, the phase-out begins at $4,090,000 of total qualifying property placed in service, and the deduction reaches zero at $6,650,000, per Revenue Procedure 2025-32. The provision that was genuinely scheduled to disappear was bonus depreciation, which the Tax Cuts and Jobs Act had set on a schedule declining to zero after 2026. That schedule was reversed. Bonus depreciation now sits permanently at 100% for qualifying property acquired after January 19, 2025.
The sections below cover why a permanent provision still generates expiration questions every year, what actually happened to bonus depreciation and where its rate stands now, which of the two provisions is permanent, what changed for Section 179 this year, the full limit history from 2017 forward, the four depreciation changes the One Big Beautiful Bill Act made, the entirely new expensing provision it created for production facilities, why Section 179 and Section 179D get confused, how states treat all of this, what can still change in future years, and what the stability means for how businesses should time capital purchases now.
Key Takeaways
- Section 179 is permanent. The PATH Act of 2015 removed the expiration date that had forced Congress to renew the provision nearly every year before that.
- The 2026 limit is $2,560,000, with the phase-out running from $4,090,000 to $6,650,000 of total qualifying property placed in service.
- Bonus depreciation was the provision scheduled to disappear. Under the Tax Cuts and Jobs Act it dropped to 80% in 2023, 60% in 2024, 40% in 2025, and would have reached zero after 2026.
- The One Big Beautiful Bill Act, signed July 4, 2025, permanently restored bonus depreciation to 100% for qualifying property acquired after January 19, 2025.
- Both provisions are now permanent, which has not been true at the same time in two decades.
- The same legislation raised the Section 179 baseline from $1,000,000 to $2,500,000 and created an entirely new provision, IRC Section 168(n), for qualified production property.
- Section 179 and Section 179D are different provisions. Section 179D is the energy-efficient commercial buildings deduction and has no relationship to equipment expensing.
- Permanence is federal only. Several states decouple from bonus depreciation and cap Section 179 independently, and that divergence is unaffected by federal law.
- The limits still change every year through inflation indexing, which is a different thing from the provision expiring.
Is Section 179 Going Away?
Section 179 is not going away, because the provision carries no expiration date and its dollar limits were increased rather than reduced by the most recent major tax legislation. The deduction has existed since 1958. Its current form has no sunset clause, no scheduled step-down, and no pending repeal, which puts it in a different category from the temporary provisions that expire and get renewed on rolling deadlines.
Permanence at the statutory level does not mean the numbers hold still. The deduction limit and the spending phase-out are both indexed for inflation and republished by the IRS in an annual revenue procedure, which means the figures change every January while the provision underneath them does not. A business owner watching the limit move from $1,220,000 to $2,500,000 to $2,560,000 across three years is watching indexation and legislation, not an expiration countdown.
The distinction matters because it changes how capital purchases get timed. A provision with a deadline creates pressure to buy before the deadline. A permanent provision lets the purchase be timed against the business's own income, cash position, and operational need instead. That shift is the single largest practical consequence of the current law for tax planning, and it removes an artificial urgency that shaped equipment buying for most of the past decade.
Why Do People Think Section 179 Is Ending?
People think Section 179 is ending because it genuinely was temporary for most of its modern history, and because the provision most often discussed alongside it really was scheduled to disappear. Two separate sources of confusion feed the same question, and both have legitimate roots.
The first source is the extenders era. For roughly fifteen years before 2016, the Section 179 limit was set by temporary legislation that Congress renewed in short increments, often retroactively and often late in the year. The limit swung between $25,000 and $500,000 depending on which bill had most recently passed, and businesses spent Decembers waiting to learn what the current year's figure would be. The PATH Act of 2015 ended that cycle by making the $500,000 limit permanent and indexing it for inflation. Business owners who lived through the extenders years learned to ask whether the deduction still existed, and the habit outlasted the reason for it.
The second source is bonus depreciation, which is a distinct provision under IRC Section 168(k) that gets discussed in the same breath as Section 179 because both accelerate first-year deductions on the same kinds of property. Bonus depreciation was on a real countdown. Articles warning that a major depreciation benefit was phasing out were accurate about bonus depreciation and were widely read as warnings about Section 179. Separating the two provisions is the first step toward answering the question correctly.
Is Bonus Depreciation Going Away?
Bonus depreciation is not going away either, though it came close, and its rate was actively declining for three years before Congress reversed the schedule. The Tax Cuts and Jobs Act set bonus depreciation at 100% for property placed in service from late 2017 through 2022, then wrote a step-down into the statute: 80% for 2023, 60% for 2024, 40% for 2025, 20% for 2026, and zero thereafter.
Two of those steps actually happened. Businesses placing equipment in service in 2023 received 80%, and businesses placing equipment in service in 2024 received 60%. The 40% rate applied briefly to property acquired in early 2025. Guidance written during that window, which is still widely circulating and still ranks well in search results, describes the decline as inevitable and advises businesses to accelerate purchases ahead of it. That advice was sound when written and is now obsolete.
The reversal came through the One Big Beautiful Bill Act, which Congress passed and the President signed on July 4, 2025. Section 70401 of that act permanently restored the 100% rate for qualifying property acquired after January 19, 2025, and removed the step-down schedule entirely. The Treasury Department and the IRS issued interim guidance on the restored provision in Notice 2026-11 on January 14, 2026, which taxpayers may rely on until proposed regulations are finalized.
Is Bonus Depreciation Still 100% in 2026?
Bonus depreciation is 100% in 2026 and carries no scheduled reduction in any future year. The rate applies to qualifying property with a MACRS recovery period of 20 years or less, acquired after January 19, 2025 from an unrelated party, and placed in service during the tax year. New and used property both qualify, since the Tax Cuts and Jobs Act removed the original-use requirement for property acquired after September 27, 2017.
Bonus depreciation carries no dollar cap, no spending phase-out, and no business income limitation, which distinguishes it sharply from Section 179 on every constraint that matters. It applies automatically unless the taxpayer affirmatively elects out, and the election out covers an entire MACRS asset class for the year rather than a single asset. Those mechanics did not change with the restoration. What changed is that the rate no longer erodes while a business decides.
Which Is Permanent, Section 179 or Bonus Depreciation?
Both Section 179 and bonus depreciation are permanent as of the One Big Beautiful Bill Act, which is a condition that has not held simultaneously in roughly twenty years. Section 179 became permanent through the PATH Act in 2015. Bonus depreciation became permanent through the OBBBA in 2025. Neither now carries a sunset date, a step-down schedule, or a scheduled renewal vote.
Permanent in this context means the statute contains no expiration provision. It does not mean the rules are beyond amendment, since any future Congress can change any provision of the code. What permanence removes is the automatic reversion that temporary provisions carry, where inaction alone causes the benefit to lapse. Both provisions now require affirmative legislation to change, which is a materially different planning environment from the one businesses navigated between 2002 and 2015.
What Changed for Section 179 in 2026?
The Section 179 changes for 2026 are inflation adjustments to figures that the One Big Beautiful Bill Act reset the year before: the deduction limit rose to $2,560,000, the phase-out threshold rose to $4,090,000, and the complete phase-out point rose to $6,650,000. Revenue Procedure 2025-32 published those amounts, applying the annual indexing in IRC Section 179(b)(6) to the new baseline.
The larger change happened in 2025 rather than 2026. Section 70301 of the OBBBA raised the Section 179 baseline from $1,000,000 to $2,500,000 and the phase-out threshold from $2,500,000 to $4,000,000, effective for property placed in service after December 31, 2024. Without that legislation, the indexed 2025 figures would have been roughly $1,250,000 and $3,130,000. The doubling put the ceiling well above what most small and mid-sized businesses will ever reach in a single year, which means the practical constraint on a Section 179 election is now almost always the business income limitation rather than the dollar cap. That shift matters most for businesses buying used equipment at volume, where total spending previously bumped against the phase-out sooner than expected.
Vehicle-specific figures moved with the same revenue procedure. The heavy SUV cap for vehicles rated between 6,001 and 14,000 pounds gross vehicle weight stands at $32,000 for 2026, and the Section 280F first-year ceiling for passenger automobiles stands at $20,300 with bonus depreciation or $12,300 without, per Revenue Procedure 2026-15. Those caps sit underneath the general limit and bind long before it does, which is why deductions on business vehicles follow a different arithmetic than deductions on equipment.
What Is the Section 179 Limit by Year?
The Section 179 limit has risen every year since 2017, from $510,000 to $2,560,000, with two legislative step-changes and seven years of inflation indexing in between. The table below sets the deduction limit, the spending phase-out threshold, and the bonus depreciation rate side by side, so the two provisions can be read against each other across the same period. This is the view that makes the confusion disappear, because the Section 179 column climbs steadily while the bonus column falls and then recovers.
Tax YearSection 179 LimitPhase-Out BeginsBonus RateGoverning Change2017$510,000$2,030,00050%, then 100% late in the yearPATH Act indexing; TCJA enacted in December2018$1,000,000$2,500,000100%Tax Cuts and Jobs Act2019$1,020,000$2,550,000100%Inflation indexing2020$1,040,000$2,590,000100%Inflation indexing2021$1,050,000$2,620,000100%Inflation indexing2022$1,080,000$2,700,000100%Final year before the TCJA step-down2023$1,160,000$2,890,00080%TCJA bonus step-down begins2024$1,220,000$3,050,00060%TCJA bonus step-down continues2025$2,500,000$4,000,00040%, then 100% after January 19One Big Beautiful Bill Act2026$2,560,000$4,090,000100%Rev. Proc. 2025-32 indexing
Two patterns stand out in that history. The Section 179 limit never fell in any year, even during the period when guidance across the internet warned that a major deduction was disappearing. The bonus depreciation rate fell for three consecutive years and then recovered to its previous ceiling. A reader who conflated the two columns would have concluded that Section 179 was eroding, which is precisely the misreading that keeps this question in circulation. Reading them as separate provisions is the sort of distinction that shapes a capital business consulting conversation more than any single year's figure does.
What Did the One Big Beautiful Bill Act Change About Depreciation?
The One Big Beautiful Bill Act made four depreciation changes: it permanently restored 100% bonus depreciation, it more than doubled the Section 179 limit and phase-out threshold, it created a new 100% expensing provision for production facilities, and it permanently restored the bonus election for specified agricultural plants. All four took effect through the same statute, signed July 4, 2025 as Public Law 119-21.
- Permanent 100% bonus depreciation, Section 70401. Restores the rate under IRC Section 168(k) for qualifying property acquired after January 19, 2025, and removes the step-down schedule the Tax Cuts and Jobs Act had written into the statute.
- Expanded Section 179 limits, Section 70301. Raises the baseline deduction limit from $1,000,000 to $2,500,000 and the phase-out threshold from $2,500,000 to $4,000,000, effective for property placed in service after December 31, 2024, with annual inflation indexing continuing from there.
- New qualified production property expensing, Section 70307. Adds IRC Section 168(n), permitting a 100% special depreciation allowance on certain domestic nonresidential real property used in manufacturing, production, or refining, which otherwise depreciates over 39 years.
- Permanent specified plant election. Retains the ability of a farming business to elect bonus depreciation in the year a specified plant is planted or grafted rather than in the year it is placed in service.
The Section 179 and bonus changes affect nearly every business that buys equipment. The Section 168(n) provision affects a narrower set of taxpayers but delivers far more per taxpayer, since it reaches real property that no prior provision could accelerate. Businesses that previously relied on reclassifying building components through a study to shorten recovery periods now have a second route for certain facilities, and the 2025 rule change altered which route produces the better result.
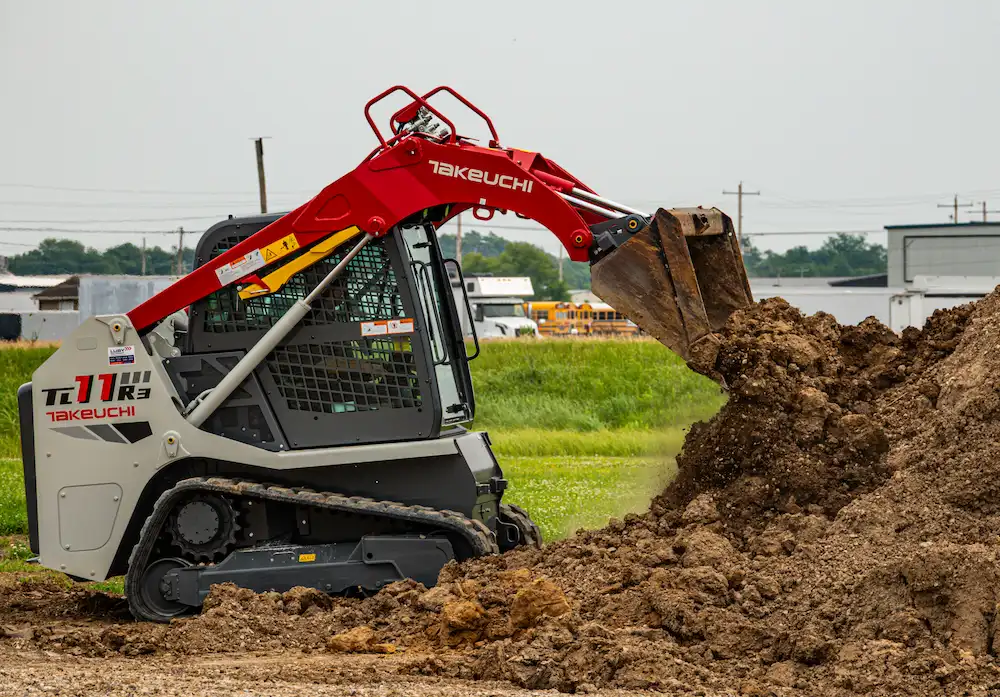
Can You Take Section 179 on Used Equipment and When Does It Apply?
Yes, you can take Section 179 on used equipment, provided the equipment is new to your business, acquired by purchase from an unrelated party, used more than 50% of the time for business, and placed in service during the tax year you claim it. The age of the asset has no bearing on eligibility. A ten-year-old CNC machine bought from an unrelated seller receives the same treatment as a machine delivered from the factory. For tax years beginning in 2026, the Section 179 deduction limit is $2,560,000, with the dollar-for-dollar phase-out beginning at $4,090,000 of total qualifying property placed in service and reaching zero at $6,650,000, per Revenue Procedure 2025-32. A separate ceiling sits underneath those figures: the deduction cannot exceed the business's taxable income from active trades or businesses, and the disallowed portion carries forward indefinitely.
The sections below cover what "new to you" means as a statutory test rather than a slogan, whether equipment you already owned personally can qualify, which family members actually count as related parties, which asset categories are eligible, when the deduction applies and what placed in service means, the 2026 dollar and income limits, a worked calculation from purchase price to final deduction, how Section 179 differs from regular depreciation, whether used equipment also qualifies for bonus depreciation, how the two provisions stack and which to lead with, how financed and leased equipment is treated, whether auction purchases qualify, how LLCs and other pass-throughs claim the deduction, and how the election is reported on Form 4562.
Key Takeaways
- Used equipment qualifies for Section 179 on identical terms to new equipment. The only difference the statute recognizes is whether the property is new to your business.
- "New to you" is shorthand for three separate statutory tests: the property must be acquired by purchase, not acquired from a related party, and not previously used by the taxpayer.
- Equipment you already owned personally and later converted to business use does not qualify, because it was not acquired by purchase for use in a trade or business.
- Siblings are not related parties for Section 179 purposes. IRC Section 179(d)(2) narrows the family definition to spouse, ancestors, and lineal descendants, which makes a purchase from a brother or sister eligible where a purchase from a parent or child is not.
- The 2026 deduction limit is $2,560,000, with the phase-out running from $4,090,000 to $6,650,000 of total qualifying property placed in service.
- Section 179 cannot exceed taxable business income and cannot create a net operating loss. Bonus depreciation has neither constraint.
- Used equipment has qualified for bonus depreciation since the Tax Cuts and Jobs Act removed the original-use requirement for property acquired after September 27, 2017.
- Electing less than the full amount of Section 179 and letting 100% bonus depreciation absorb the remainder often produces a larger first-year deduction than a maximum election.
- Financed purchases qualify in full in the first year. Operating leases do not, because the lessee holds no depreciable basis.
Can You Take Section 179 on Used Equipment?
You can take Section 179 on used equipment under the same rules that govern new equipment, because IRC Section 179(d)(1) conditions the deduction on how the property is acquired and used rather than on how old it is. The statute describes qualifying property as tangible property that is Section 1245 property, acquired by purchase for use in the active conduct of a trade or business. Nothing in that definition references the manufacture date, the original owner, or the condition of the asset.
Acquisition and use are the two axes that actually control the answer. The acquisition side asks whether the property was purchased, whether the seller was an unrelated party, and whether the buyer had used the property before. The use side asks whether business use exceeds 50% and whether the property entered service during the tax year. Used equipment that clears all five of those tests is fully eligible, and used equipment that fails any one of them is not, regardless of price or condition.
The practical significance is largest for businesses buying capacity rather than novelty. A second commercial oven, a used excavator, a refurbished server rack, and a pre-owned dental chair all produce the same first-year deduction that new versions would, at a fraction of the outlay. Sequencing those purchases against the year's income rather than against the vendor's promotion calendar is the part of tax planning that turns a good price into a good tax result.
What Does "New to You" Actually Mean?
"New to you" means the property was acquired by purchase, was not acquired from a related party, and had not previously been used by the taxpayer, which are three separate tests packed into one phrase. Each test comes from a different clause of IRC Section 179(d)(2), and a purchase can satisfy two of them and still fail the third. Treating the phrase as a single idea is how buyers end up surprised.
The acquisition-by-purchase test excludes property received by gift and property received by inheritance under IRC Section 179(d)(2)(B) and (C). Equipment left to a business owner by a parent's estate carries a stepped-up basis and depreciates normally, but it cannot be expensed under Section 179, because no purchase occurred. The same logic reaches property received in a contribution to capital and property whose basis is determined by reference to the transferor's basis.
The prior-use test and the related-party test each get their own treatment below, since both are where real transactions fail. What holds across all three is that the seller's history with the asset is irrelevant. A machine that ran in three prior shops over fifteen years is new to your business the moment you buy it from an unrelated party, and its accumulated depreciation on someone else's books has no effect on your deduction.
Can You Take Section 179 on Equipment You Already Owned Personally?
You cannot take Section 179 on equipment you already owned personally and later converted to business use, because the property was not acquired by purchase for use in the active conduct of a trade or business. The acquisition and the business purpose have to coincide. Buying a camera for personal photography in 2024 and starting a photography business with it in 2026 fails the test, no matter how exclusively the camera is used for the business afterward.
Converted property is not left without any deduction. It enters service at the lower of adjusted basis or fair market value on the conversion date, and it depreciates over its remaining MACRS recovery period on a normal schedule. The owner simply loses the acceleration that Section 179 and bonus depreciation would have provided on a purchase. Documenting the fair market value at the conversion date, through comparable sale listings or a written appraisal, is what supports the depreciable basis if it is ever questioned.
Can You Buy Equipment From a Family Member and Take Section 179?
You can buy equipment from some family members and claim Section 179, and you cannot from others, because IRC Section 179(d)(2) applies a narrower definition of family than the rest of the tax code uses. The general related-party rules in IRC Section 267 treat brothers and sisters as related parties. Section 179 does not. The flush language of Section 179(d)(2) directs that Section 267(c)(4) be applied as if an individual's family included only a spouse, ancestors, and lineal descendants.
That narrowing produces a result most buyers get backward. A purchase from a parent, grandparent, child, grandchild, or spouse is excluded. A purchase from a brother or sister is not excluded on family grounds, and the equipment can qualify if the transaction is otherwise a genuine arm's-length purchase. Controlled entities remain excluded under the Section 267(b) and Section 707(b) relationships regardless of who owns them, so buying equipment from a second company you control fails even though no family member is involved.
Arm's length is doing real work in that sentence. A sibling sale documented with a written bill of sale, a fair market value supported by comparable listings, and an actual transfer of funds looks entirely different from a nominal transfer at a convenient price. Family transactions also intersect with entity structure in ways that are easier to arrange correctly at the point of business formation than to defend afterward.
What Assets Does Section 179 Apply To?
Section 179 applies to tangible personal property used in a trade or business, off-the-shelf computer software, and certain improvements to nonresidential buildings, in each case whether the property is new or used. The qualifying categories cover most of what a business buys that is not real estate or inventory:
- Machinery and production equipment. Manufacturing lines, CNC machines, presses, compressors, and industrial tools.
- Heavy and specialized equipment. Construction, agricultural, mining, and material-handling machinery, including trailers and towable equipment.
- Office furniture and equipment. Desks, seating, filing systems, printers, copiers, and phone systems.
- Computers and peripherals. Workstations, laptops, servers, monitors, and network hardware.
- Off-the-shelf software. Software available to the general public under a nonexclusive license, purchased rather than subscribed.
- Restaurant and commercial kitchen equipment. Ranges, refrigeration, dishwashing systems, and prep equipment.
- Qualified improvement property and building systems. Interior improvements to nonresidential buildings, plus roofs, HVAC, fire protection, alarm, and security systems under the IRC Section 179(f) carve-out.
The exclusions are narrower than they look and mostly concern what the property is rather than how old it is. Inventory held for resale does not qualify, since it is not depreciable. Intangibles such as patents, trademarks, and customer lists are amortized under different provisions. Buildings and their structural components are excluded outside the 179(f) carve-outs, and land improvements such as parking lots, fences, and landscaping fall outside Section 179 entirely while still qualifying for bonus depreciation. Property used predominantly outside the United States is excluded under IRC Section 50(b)(1).
Can You Take Section 179 on Used Vehicles?
You can take Section 179 on used vehicles under the same new-to-you standard that applies to equipment, subject to an additional layer of weight-based caps that equipment does not face. A used vehicle rated at or below 6,000 pounds gross vehicle weight is a passenger automobile subject to the Section 280F ceilings. A used passenger SUV rated between 6,001 and 14,000 pounds carries a $32,000 Section 179 cap for 2026. Heavy non-SUV vehicles face no model-specific cap at all.
Vehicles also carry stricter substantiation, since IRC Section 280F(d)(4) classifies them as listed property and requires a contemporaneous mileage log rather than a year-end estimate. The full weight tiers, caps, and recapture rules for business vehicles run deeper than this page covers, and the rest of this discussion stays with equipment.
When Can You Take the Section 179 Deduction?
You can take the Section 179 deduction in the tax year the equipment is placed in service, which means the equipment must be delivered, installed, and ready for its intended business use on or before the last day of that tax year. For a calendar-year business, the deadline is December 31. Ordering, paying, financing, and taking delivery are each necessary steps toward that date, and none of them is sufficient on its own.
Ready and available for use is the operative standard from IRS Publication 946, and it turns on functional readiness rather than on actual operation. A commercial mixer delivered on December 20, uncrated, wired in, and ready to run is placed in service on December 20 even if the first batch is mixed in January. The same mixer sitting on a pallet awaiting an electrician is not placed in service until the electrician finishes, and that distinction has moved entire deductions into the following year for businesses that built no installation buffer into a year-end purchase.
What If You Buy Equipment in December but Use It in January?
Equipment bought in December but not ready for use until January is deducted in the following tax year, because the placed-in-service date controls the deduction rather than the purchase date or the payment date. The invoice date is irrelevant. A fully paid, fully delivered machine that still needs assembly, calibration, permitting, or utility connection on December 31 belongs to the next year's return.
Installation lead time is the variable worth building into a purchase decision. Hood systems need permits. Three-phase equipment needs an electrician. Large machinery needs rigging and sometimes a floor inspection. We work through this timing with restaurant accounting clients in Miami almost every December, because a used walk-in cooler that arrives on the 28th and gets connected on January 4 produces a deduction a full year later than the owner planned. Ordering in October rather than mid-December is usually the cheaper fix.
What Are the 2026 Section 179 Limits?
The 2026 Section 179 limits are a $2,560,000 maximum deduction and a phase-out that begins at $4,090,000 of total qualifying property placed in service during the year, eliminating the deduction entirely at $6,650,000. Those figures come from the inflation adjustment in Revenue Procedure 2025-32, applied to the permanent baseline the One Big Beautiful Bill Act established when it raised the limit from $1,000,000 to $2,500,000 effective for tax years beginning after December 31, 2024.
The phase-out reduces the ceiling dollar for dollar rather than by percentage, and it is measured against total qualifying property placed in service rather than against the amount elected. A business placing $4,500,000 of qualifying property in service in 2026 exceeds the threshold by $410,000, which drops its ceiling from $2,560,000 to $2,150,000. The same business could elect far less than that and still face the reduced ceiling, because the trigger is spending rather than election size.
Used equipment counts toward the spending threshold at its purchase price, not at its original cost when new. A business buying $900,000 of used machinery that cost $2,400,000 new adds $900,000 to its phase-out calculation. That is one of the quieter advantages of buying used for capital-intensive operations: the same production capacity consumes far less of the phase-out headroom.
What Is the Business Income Limit for Section 179?
The business income limit caps the Section 179 deduction at the taxpayer's aggregate taxable income from the active conduct of any trade or business, and the amount disallowed by that cap carries forward indefinitely under IRC Section 179(b)(3). Section 179 cannot create a net operating loss or deepen an existing one. It can reduce taxable business income to zero and no further.
Business income for this test is broader than the net profit of the single activity that bought the equipment. It includes wages earned by the taxpayer, net income from other active businesses, and, on a joint return, the spouse's earned income. A consultant with $50,000 of net business profit and $140,000 of W-2 wages has $190,000 of business income available, which is a figure that frequently changes the answer for owners who assumed the equipment purchase could not be expensed.
The carryforward has no expiration and is not reduced over time, though it does sit idle until a profitable year absorbs it. A deduction deferred three years into the future is worth less in present-value terms than the same deduction taken now, and it may be worth more if the business expects a higher marginal rate later. Modeling that tradeoff across the next several years before the election is set is standard Virtual CFO work whenever a client is planning a significant equipment year.
How Do You Calculate the Section 179 Deduction?
You calculate the Section 179 deduction by applying the business-use percentage to the purchase price, testing the result against the annual dollar limit and the spending phase-out, then against the business income limitation, and finally applying bonus depreciation to any basis that remains. The order matters, because each ceiling is measured against the figure the previous step produced. A worked example makes the sequence concrete. Assume a $180,000 used production line purchased and placed in service in 2026, used 90% for business, in a company with $120,000 of taxable business income and no other capital purchases that year.
- Apply the business-use percentage to the purchase price. The $180,000 cost multiplied by 90% produces a $162,000 depreciable basis. The remaining $18,000 is personal and never enters the calculation.
- Test against the annual dollar limit. The 2026 ceiling of $2,560,000 far exceeds $162,000, so the dollar limit imposes no reduction.
- Test against the spending phase-out. Total qualifying property placed in service is $180,000, well below the $4,090,000 threshold, so the ceiling is not reduced.
- Test against taxable business income. Only $120,000 of business income is available, which caps the usable Section 179 deduction at $120,000 for the year.
- Elect Section 179 up to the income limit rather than up to the basis. Electing $120,000 keeps the entire deduction usable this year and leaves $42,000 of basis intact.
- Apply 100% bonus depreciation to the remaining basis. The $42,000 balance is deducted in full under IRC Section 168(k), which carries no dollar cap and no income limitation.
- Total the first-year deduction. The $120,000 Section 179 election plus $42,000 of bonus depreciation produces the full $162,000 in year one, with no carryforward to track.
Step five is where most calculations go wrong. Electing the full $162,000 would have produced a $120,000 current deduction and a $42,000 carryforward waiting on a future profitable year, because the basis reduction follows the amount elected rather than the amount allowed. The partial election reaches the same total deduction a year or more sooner. Recording the election amount and the resulting basis correctly in the fixed asset schedule behind the year-end financial statements is what keeps the two figures from drifting apart in later years.
What Is the Difference Between Section 179 and Depreciation?
The difference between Section 179 and depreciation is timing and election: Section 179 expenses the cost in the year the property is placed in service by affirmative election, while regular MACRS depreciation recovers the same cost automatically across the property's assigned recovery period. Both recover the identical total amount. They differ on when the deduction lands and on how much control the taxpayer has over it.
AttributeSection 179Regular MACRS DepreciationTiming of deductionEntire amount in the placed-in-service yearSpread across 5, 7, 15, or more yearsElection requiredYes, on Part I of Form 4562No, applies by default2026 dollar cap$2,560,000NoneSpending phase-outBegins at $4,090,000; zero at $6,650,000NoneBusiness income limitationYes, cannot exceed active business incomeNoCan create a net operating lossNoYesUsed property eligibleYes, if new to the businessYesPer-asset flexibilityElected asset by asset, partial amounts permittedApplied uniformly by asset classState conformityBroad, though several states cap the amountUniversal
Per-asset flexibility is the attribute that makes Section 179 a planning instrument rather than a formula. The election can be made on one machine and skipped on another, and it can be made for part of a single asset's basis. That surgical control is what allows a business to land taxable income on a chosen figure instead of accepting whatever the default schedules produce, and it is the reason the election belongs in a tax strategy discussion held in November rather than a data-entry decision made in April.
Does Used Equipment Qualify for Bonus Depreciation?
Used equipment qualifies for 100% bonus depreciation as long as it is new to the taxpayer and acquired from an unrelated party, which has been the rule since the Tax Cuts and Jobs Act removed the original-use requirement for property acquired after September 27, 2017. Before that change, bonus depreciation reached only property whose original use began with the taxpayer, which excluded used equipment entirely. The expansion is what gives used-equipment buyers two accelerators instead of one.
The One Big Beautiful Bill Act then made the 100% rate permanent for qualifying property acquired after January 19, 2025, replacing a phase-down schedule that had reduced the rate to 60% in 2024 and would have dropped it to 20% in 2026. Bonus depreciation carries no dollar cap, no spending phase-out, and no business income limitation, and it can create or deepen a net operating loss. It applies automatically unless the taxpayer elects out, and the election out covers an entire MACRS asset class for the year rather than a single asset.
The same two provisions govern equipment placed into a rental property, where the asset mix often spans several recovery periods at once. What changes across contexts is not the eligibility of used property but which provision produces the better result given the year's income.
Can You Take Both Bonus Depreciation and Section 179?
You can take both provisions on the same equipment purchase, applied in a fixed order: Section 179 first, bonus depreciation on the basis that remains, and regular MACRS depreciation on anything still left. IRS Publication 946 prescribes that sequence, and it is not optional. The two provisions cover different dollars rather than the same dollars twice.
Stacking matters most when one ceiling binds and the other does not. A business at the Section 179 spending phase-out uses bonus depreciation to reach a full write-off that Section 179 alone cannot deliver. A business with thin income elects a smaller Section 179 amount and lets bonus depreciation carry the rest, as the worked calculation above demonstrates. The order stays the same in every case, and only the split between the two changes.
Is It Better to Take Section 179 or Special Depreciation?
Section 179 produces the better result when the state does not conform to federal bonus depreciation or when the business wants asset-level control over the deduction, and the special depreciation allowance produces the better result when income is too thin to absorb an election or when a net operating loss is useful. The answer changes by state, by year, and sometimes by asset within the same purchase.
State conformity is the most concrete variable. California, New York, New Jersey, Massachusetts, Rhode Island, and New Hampshire do not conform to federal bonus depreciation, according to a Withum analysis of state responses to the One Big Beautiful Bill Act, while Section 179 conformity is far broader even where states cap the amount. A business filing in one of those states can leave real state-level deduction on the table by favoring bonus. Florida imposes no personal income tax, which removes the question entirely for an individual owner filing there, and a business operating across several states runs the comparison separately for each one.
One acquisition method removes the choice. Property acquired with floor plan financing, the revolving inventory credit line used by dealerships, is denied bonus depreciation under IRS Publication 946. Section 179 remains available on that property, which makes the election the only route to a first-year deduction for a buyer whose lender uses that structure.
Can You Take Section 179 on Financed or Leased Equipment?
You can take Section 179 on financed equipment for the full purchase price in the first year regardless of how little has been paid down, and you cannot take it on equipment held under an operating lease because the lessee holds no depreciable basis. The deduction attaches to the cost of property the taxpayer owns for tax purposes, not to cash outlay during the year.
Capital leases sit with purchases rather than with rentals. A lease structured so the lessee is treated as the tax owner, typically through a bargain purchase option or a term covering most of the asset's useful life, supports a Section 179 election on the full capitalized cost. An operating lease produces a deductible rent expense under IRC Section 162 instead, spread across the lease term. The two structures can look similar in a financing proposal and produce entirely different returns, which is why the lease documents belong in the business consulting review before signing rather than after.
Financing a used purchase creates a timing advantage worth naming. A business can place $200,000 of used equipment in service in December, deduct the qualifying amount on that year's return, and pay for the equipment over the following five years. The deduction lands immediately and the cash leaves gradually, which is the strongest cash-flow case for the provision and the reason equipment lenders promote it so heavily.
Does Equipment Bought at Auction Qualify?
Equipment bought at auction qualifies for Section 179 on the same terms as a dealer purchase, since an auction is an arm's-length acquisition by purchase from an unrelated party. The winning bid plus the buyer's premium and applicable taxes forms the depreciable basis, and transportation, rigging, and installation costs are capitalized into that basis as well rather than deducted separately.
Documentation carries more weight in auction and private-party purchases than in dealer transactions, because no invoice trail exists by default. The file should hold the auction house settlement statement or a written bill of sale, proof of payment, the delivery date, and the date the equipment became ready for use. A private-party purchase should also carry some evidence that the price reflected fair market value, such as comparable listings captured at the time, which matters most when the seller is an acquaintance and the price is unusually favorable.
Can an LLC Take a Section 179 Deduction?
An LLC can take a Section 179 deduction, and how the limit applies depends on the LLC's tax classification rather than on its legal form. A single-member LLC treated as a disregarded entity reports the deduction on Schedule C and applies the limit once, at the owner level. A multi-member LLC taxed as a partnership applies the limit twice, and so does an LLC or corporation taxed as an S corporation.
The double limitation in IRC Section 179(d)(8) is what catches owners of multiple entities. The entity applies the $2,560,000 ceiling and the business income limitation at its own level, allocates the deduction to members on Schedule K-1, and each member then applies the same ceiling again across every source on the personal return. An owner holding interests in four entities that each allocate $800,000 receives $3,200,000 of allocated Section 179 and can personally deduct no more than $2,560,000 in 2026.
Entity-level income limits create a second trap for pass-throughs. A partnership with a loss for the year cannot pass through any Section 179 deduction at all, even to partners with substantial outside income, because the entity's own business income caps the allocation before it reaches the K-1. Bonus depreciation flows through without that entity-level income test, which often makes it the better provision for startup and tech entities in their early loss years.
How Do You Claim Section 179 on Form 4562?
You claim Section 179 by completing Part I of Form 4562, Depreciation and Amortization, and attaching it to a timely filed return for the year the equipment was placed in service. Line 1 carries the maximum dollar limit of $2,560,000 for 2026, line 2 carries the total cost of Section 179 property placed in service, line 3 carries the $4,090,000 threshold, and lines 4 and 5 produce the reduced ceiling after any phase-out.
Line 6 is where the individual assets are listed, each with a description, its total cost, and the specific amount elected, which can be any figure from zero up to the full cost. Line 11 applies the business income limitation, and line 13 carries any disallowed amount forward to the following year. Keeping the elected amounts at the asset level rather than as a single pooled figure is what makes a later disposition, a later business-use change, or a state adjustment computable without reconstructing the year from invoices.
The election is also reversible. Treasury Regulation Section 1.179-5(c) permits a Section 179 election to be revoked on an amended return filed within the period for that tax year, without IRS consent, though the revocation itself is irrevocable once made. A business that elected too aggressively and then saw its income picture change has that route available, which is one more reason a proactive tax planning review in the fourth quarter costs less than a correction the following spring.
Frequently Asked Questions
Is Equipment a 100% Write Off?
Equipment is a 100% write-off in the first year when the business has enough taxable income to absorb a Section 179 election, or when bonus depreciation covers whatever the election cannot reach. Bonus depreciation carries no dollar cap and no income limitation, so the combination produces a full first-year deduction on qualifying equipment in almost every case. The exceptions are property acquired with floor plan financing and property in states that decoupled from the federal rules.
Does Section 179 Apply to Used Equipment Bought From a Company You Also Own?
Section 179 does not apply to equipment bought from a company you also own, because controlled entities are related parties under IRC Section 267(b) and Section 707(b), which Section 179(d)(2)(A) incorporates by reference. The exclusion holds even when fair market value is paid and the transaction is fully documented. Moving equipment between entities under common control is a transfer of basis rather than a purchase that resets it.
Can You Take Section 179 on Refurbished or Reconditioned Equipment?
Refurbished and reconditioned equipment qualifies for Section 179 on the same terms as any other used property, since the statute cares about how the property was acquired rather than about its condition. The purchase price forms the depreciable basis, and refurbishment costs paid by the seller are already embedded in that price. Refurbishment the buyer pays for after acquisition is capitalized into the equipment's basis rather than deducted as a repair.
Does Software Qualify for Section 179 If It Is Not New?
Off-the-shelf software qualifies for Section 179 whether or not the copy is new, provided it is available to the general public under a nonexclusive license, has not been substantially modified, and is purchased rather than subscribed. Software-as-a-service subscriptions are treated as services rather than as purchased property, which puts them outside Section 179 and into ordinary deductible business expense.
Can You Take Section 179 on Used Equipment in Your First Year of Business?
You can take Section 179 on used equipment in your first year of business, subject to the same taxable income limitation that applies in any other year. A first-year business with minimal income will often find the election capped well below the equipment's cost, which is where bonus depreciation becomes the better lead since it can create a net operating loss that carries forward. Startup advisory work usually models both paths before the first return is filed.
What Records Should You Keep for a Used Equipment Purchase?
The records to keep for a used equipment purchase are the bill of sale or invoice, proof of payment, the financing or lease agreement, the delivery date, the date the equipment became ready for its intended use, and any installation or transportation invoices capitalized into basis. Equipment with both business and personal use needs a usage log as well. These records establish the two dates and the one number that the entire deduction depends on.
The Bottom Line
Used equipment is fully eligible for Section 179, and the questions that actually decide a given purchase have nothing to do with the equipment's age. They are whether the seller was a related party under the narrower family definition Section 179 applies, whether the property was acquired by purchase rather than converted from personal use, whether it was ready for its intended business use before the year closed, and whether the business has enough taxable income to absorb an election. The 2026 ceilings of $2,560,000 and $4,090,000 rarely bind a small or mid-sized business. The income limitation and the placed-in-service date almost always do.
The planning work sits in two places. Ordering early enough that installation finishes before December 31 protects the year the deduction lands in, and electing Section 179 only up to available income while letting bonus depreciation absorb the remainder protects the amount. Both decisions are made once, and both are far cheaper to get right in the fourth quarter than to correct on an amended return. If you are planning an equipment purchase and want the election modeled against your projected income before you commit, the advisors at NR CPAs & Business Advisors are glad to run it with you, and you can reach us at +1 954-231-6613.