



Business Continuity & Estate Planning
What Happens to a Sole Proprietorship When the Owner Dies?
Without a plan, your business—and your family's financial security—may disappear. Life insurance and buy-sell agreements protect both.
By Nischay Rawal · Published October 05, 2026
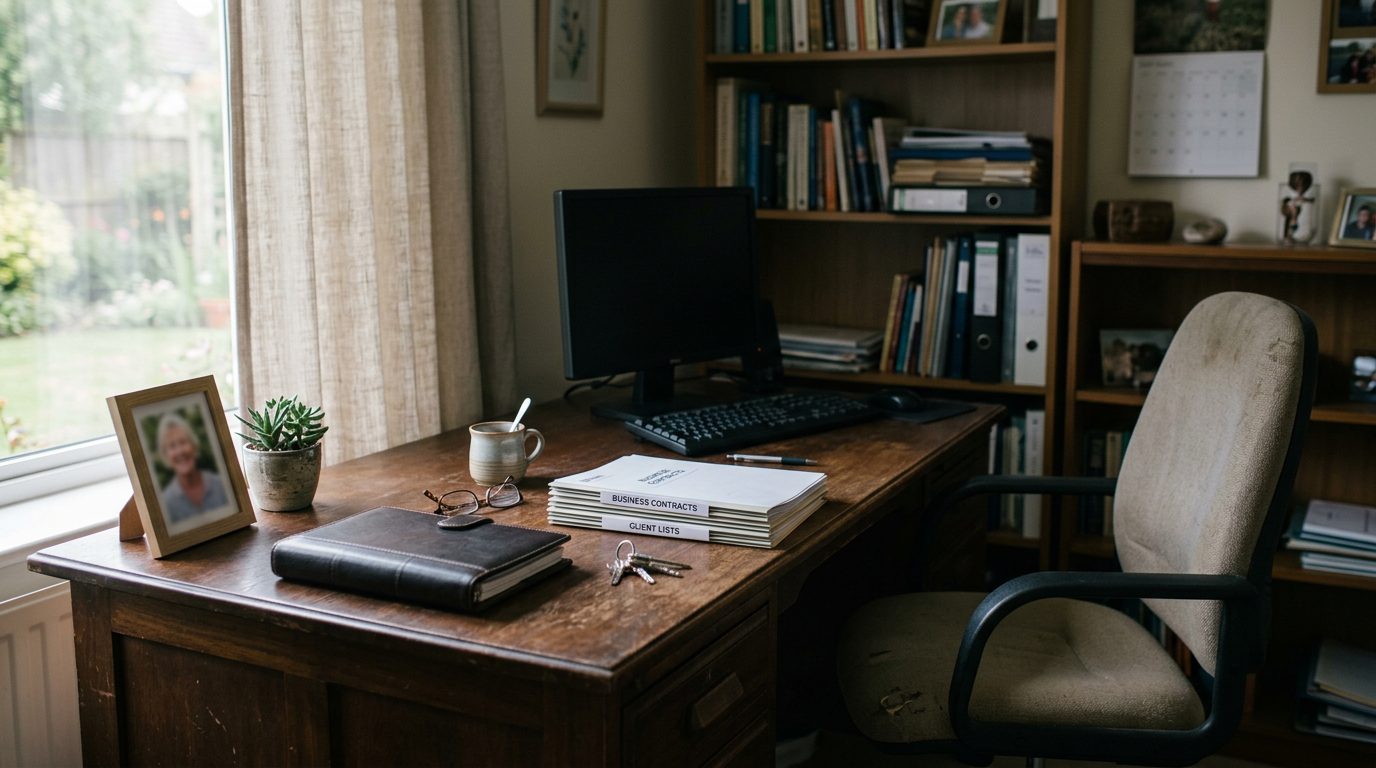
A sole proprietorship ceases to exist when the owner dies because the business and the owner are legally one and the same—there is no separate business entity to survive. When that happens, the business’s assets become part of the owner’s personal estate, business debts don’t disappear, and the family faces an immediate loss of income while the estate goes through probate. This is why life insurance matters for sole proprietors: it provides immediate cash to protect what you’ve built and the people who depend on it.
A Sole Proprietorship Is Not a Separate Legal Entity
A sole proprietorship is the simplest business structure, but it has one critical weakness: the owner and the business are one and the same in the eyes of the law. Unlike a corporation or limited liability company (LLC), which exist as separate legal entities, a sole proprietorship has no independent legal existence. When the owner dies, the business ceases to exist as a legal matter.
This is fundamentally different from other business structures. A corporation or LLC can continue operating under new management. A partnership can be transferred to surviving partners. But a sole proprietorship cannot. The business ends when the owner does.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What Happens to Business Assets After Death
When a sole proprietor dies, the business’s assets—equipment, inventory, accounts receivable, customer lists, and goodwill—become part of the owner’s personal estate. Under federal tax law, the value of all property beneficially owned by the decedent at the time of death is included in the gross estate, which means business assets are subject to estate valuation and probate.
Probate is the court process that settles the owner’s affairs. During probate, a judge oversees the distribution of assets, pays debts, and ensures the owner’s wishes (as stated in a will or trust) are carried out. This process typically takes months or longer, during which time the family may not have access to the business assets or any cash they generate.
The estate must also pay funeral expenses, administration costs, and claims against the estate, which can include unpaid business debts. If the estate doesn’t have enough liquid assets to cover these obligations, business assets may need to be sold at a loss to raise cash.
Business Debts Don’t Disappear
When a sole proprietor dies, business debts remain. Creditors can file claims against the estate for outstanding loans, equipment leases, vendor obligations, and any other liabilities the business incurred.
If the business has significant debt—a line of credit, a commercial mortgage, or equipment financing—the estate may be unable to pay everything owed. In that case, assets (including business assets) must be liquidated to satisfy creditors. This often means selling the business or its assets at a steep discount, leaving the family with far less than the business was worth.
Can a Sole Proprietorship Continue After the Owner Dies?
No. A sole proprietorship cannot be transferred to a family member, employee, or successor the way a corporation or partnership might be. If someone wants to continue the business, they must start a new business entity from scratch and rebuild the customer base, licenses, and reputation.
This restart is rarely successful. Customers often leave because the owner—who built the relationships and reputation—is gone. Vendors may stop extending credit. Employees may depart if there’s no clear direction or payroll continuation. Licenses and permits tied to the owner may become invalid or require new applications. In most cases, the business stops generating revenue within days or weeks, and the family is left managing a closing business while grieving and handling the owner’s personal affairs.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
The Immediate Impact on Family Income
For a sole proprietor, the business is often the primary source of household income. When the owner dies, that income stops immediately. The family faces an urgent cash flow crisis: mortgage payments, rent, utilities, groceries, and other living expenses continue, but the income that paid for them is gone.
The estate may have assets, but these are tied up in probate for months or years. Family members may need to cover living expenses while waiting for the estate to settle. If the business had significant debt, the estate may be insolvent, leaving the family with little or nothing after creditors are paid.
Why Life Insurance Protects What You’ve Built
Life insurance provides immediate cash to the family when the owner dies, without waiting for probate. The death benefit is paid directly to named beneficiaries, usually within weeks of the claim being filed. Importantly, life insurance death benefits are excluded from gross income, meaning the family receives the proceeds tax-free.
This cash can be used to:
- Replace lost business income and help the family maintain their standard of living
- Pay off business debts so the family doesn’t inherit those obligations
- Fund severance for employees or help a family member wind down the business in an orderly way
- Cover estate taxes, probate costs, and funeral expenses
- Provide a financial cushion while the family grieves and decides what to do next
A term life or whole life policy can be structured to address the specific financial needs the business creates. The death benefit amount should reflect the income the family will lose and the debts the business carries.
Estate Planning and Succession for Sole Proprietors
A will or trust should address what happens to the business and its assets when the owner dies. Without a plan, the business may be sold at a loss or abandoned, and the family may receive far less than the business was worth.
Life insurance can be part of an integrated estate plan. It ensures the family has immediate resources to settle debts, maintain financial stability, and make thoughtful decisions about the business rather than desperate ones. A CPA can help a sole proprietor think through the tax and cash flow impact of the business ending and what the family will actually need to survive and thrive.
Want to know where you stand?
Tell us about your situation and our team will walk you through the options available to you.
Frequently Asked Questions
Can a sole proprietor’s family take over the business after the owner dies?
Not as a sole proprietorship. The business legally ceases to exist. A family member could start a new business entity and attempt to continue operations, but they would lose customers, vendors, and the owner’s reputation.
Are business debts forgiven when a sole proprietor dies?
No. Creditors can file claims against the estate, and debts must be paid from the owner’s assets before anything goes to heirs.
Is life insurance on a sole proprietor taxable to the family?
The tax treatment of life insurance death benefits is a question we can walk through with you based on your situation.
How much life insurance does a sole proprietor need?
That depends on the business’s debt, the family’s living expenses, and the income the family will lose. A coverage review can help you determine the right amount for your situation.
If you’re a sole proprietor, the reality is clear: your death will end your business and create an immediate financial crisis for your family. Life insurance is one of the most direct ways to prevent that crisis. When you’re ready to explore how much protection your family needs and what type of policy fits your cash flow, reach out to discuss your situation with our team.
The Hard Truth
A sole proprietorship has no legal existence separate from its owner. When you die, the business does not automatically pass to your family or continue under new ownership. It legally ceases to exist. Family members cannot simply 'take over'—they would have to start a new entity from scratch, losing customers, vendor relationships, goodwill, and the reputation you built.
What Your Family Faces Without a Plan
Business Debts Don't Disappear
Creditors pursue the estate. Business liabilities, loans, and unpaid invoices become claims against your assets—reducing what your family inherits.
No Income for Your Family
The business stops generating revenue the moment you die. Your spouse, children, and dependents lose the income they relied on.
Customers and Vendors Leave
Without continuity, clients seek other providers and vendors demand payment. Years of relationship-building vanish.
Your Family Must Liquidate Quickly
To pay estate taxes and debts, executors often sell business assets at fire-sale prices, destroying value.
How Life Insurance and Buy-Sell Agreements Protect Your Business
Key-Person Insurance
If you have employees or partners who depend on your skills and relationships, key-person insurance replaces the income your death would cost the business and gives your family a financial cushion.
Buy-Sell Agreement Insurance
If you have a co-owner or partner, a buy-sell agreement funded by life insurance ensures a smooth, fair transition. The insurance proceeds fund the buyout, so your family receives the business value in cash rather than fighting over control.
Estate Planning Life Insurance
Term or whole life insurance provides immediate liquidity to pay estate taxes, business debts, and expenses—so your family keeps the business or receives a larger inheritance.
CPA Perspective on Tax and Cash Flow
Life insurance proceeds are generally income-tax-free to your beneficiaries. We help you structure coverage so it aligns with your tax situation and preserves the most wealth for your family.
Steps to Protect Your Sole Proprietorship
Assess Your Business Value and Needs
How much income does your family need if you die? What debts must be paid? What is your business worth? These answers determine how much coverage you need.
Choose the Right Type of Coverage
Term life insurance provides affordable protection for a set period. Whole life insurance builds cash value and lasts your lifetime. We help you match the type to your goals.
Document Your Plan
A buy-sell agreement, funded by life insurance, ensures your family and any partners know exactly what happens. Without it, disputes and forced sales destroy value.
Coordinate with Your Estate Plan
Life insurance works hand-in-hand with your will, trusts, and tax strategy. We ensure all pieces fit together to protect your loved ones and your business.
Why This Matters for Indian-American Business Owners
Many family businesses are built on the owner's personal relationships and reputation. In Indian-American communities, the business often represents decades of sacrifice and is meant to support multiple generations. Without life insurance and a clear succession plan, that legacy can evaporate in weeks. A coverage review ensures your hard work protects your family, not just during your lifetime, but after.
Your Business Deserves a Plan
Related practice areas
- Key Person Insurance for Business Owners: Protect Your Company’s Future
- What Happens to a Business Account When Owner Dies?


