



Life Insurance for Business Owners
Key Person Insurance for Business Partners
Protect your partnership from the financial impact of losing a critical owner or manager.
By Nischay Rawal · Published October 04, 2026
Key Person Insurance for Business Partners: Protecting Your Partnership When It Matters Most
Key person insurance is a life insurance policy that your business owns and controls, with the business as the beneficiary. When a key partner dies or becomes disabled, the death benefit goes to the business—not to the partner’s family—to cover the financial loss caused by that partner’s absence.
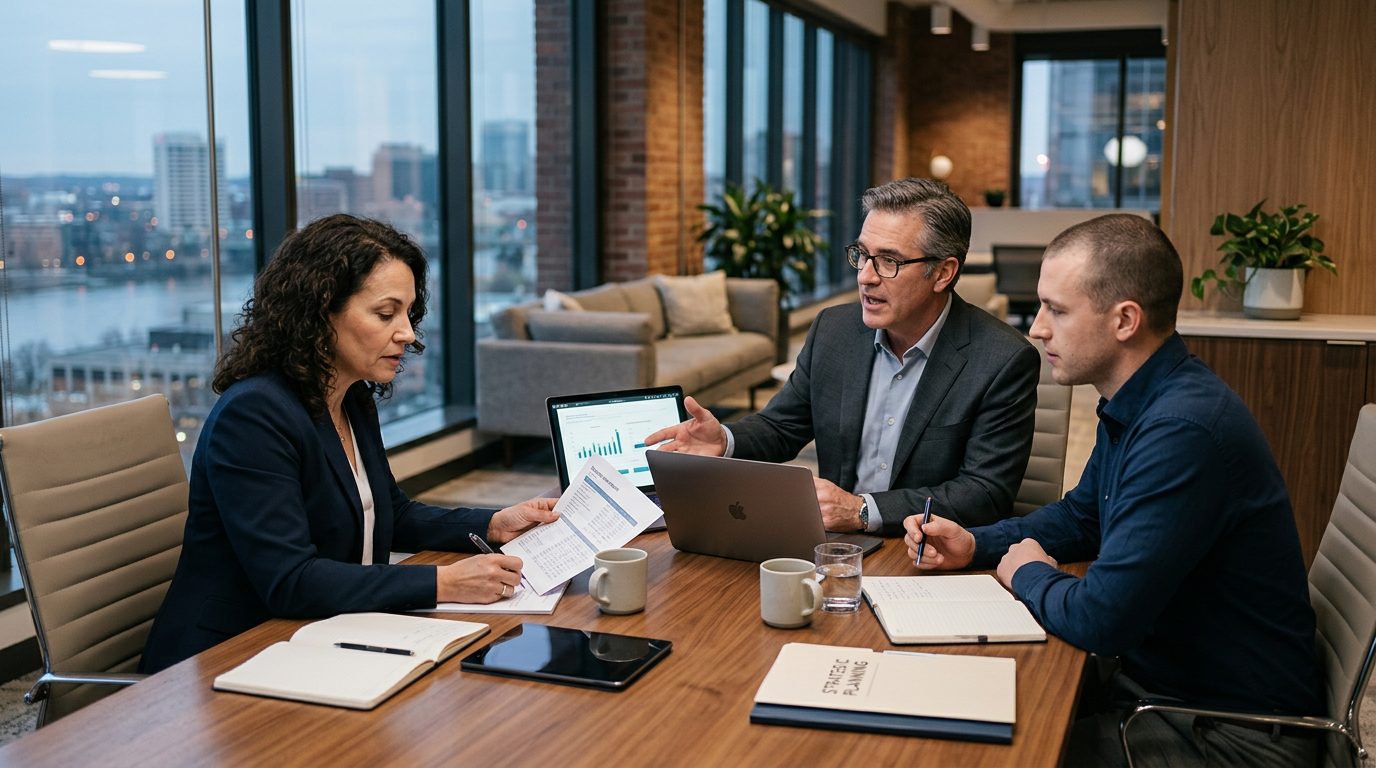
For business partners, especially in professional practices and family firms, key person insurance can be the difference between weathering a crisis and watching the partnership collapse. This guide explains how it works, who needs it, and how to think about it from a cash flow and tax perspective.
If your partnership faces the loss of a key partner and you're unsure whether key person insurance is right for you, reach out. Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
What Is a Key Person in Insurance?
A key person is any partner or employee whose death, disability, or departure would cause significant financial loss to the business.
In a partnership, any partner can be a key person—and often all partners are. Key person status isn’t determined by job title or seniority; it’s based on the partner’s role, skills, client relationships, revenue generation, or specialized expertise. A partner who brings in major clients, holds critical technical knowledge, or manages key operations is a key person. So is a partner whose departure would force the business to hire and train a replacement at substantial cost.
The business itself owns the key person insurance policy. The business applies for it, pays the premiums, and names itself as the beneficiary. When the insured partner dies or becomes disabled (depending on the policy terms), the death benefit is paid to the business, not to the partner’s family. This is a crucial distinction: key person insurance protects the business’s financial interests, not the partner’s personal estate.
How Key Person Insurance Works for Business Partners
The mechanics are straightforward. Your business applies for a life insurance policy on a key partner. During underwriting, the insurance company evaluates the partner’s health, age, and occupation to determine if they’re insurable and what premium to charge.
If the partner dies or becomes disabled (depending on your policy), the business receives the death benefit. That money can be used in several ways:
- Cover lost revenue. If the partner generated significant income or managed major client relationships, their absence creates an immediate revenue gap. The death benefit helps the business stay afloat during the transition.
- Pay off the partner’s share of business debt. Banks and creditors may demand payment if a key owner dies. The death benefit can satisfy those obligations.
- Hire and train a replacement. Finding and training a qualified replacement takes time and money. The death benefit funds that process.
- Stabilize operations. The business can use the benefit to maintain payroll, cover operating expenses, and keep the doors open while leadership adjusts to the loss.
Key person insurance is different from buy-sell agreement insurance. Key person insurance protects the business from general financial loss. Buy-sell agreement insurance, by contrast, funds the purchase of a deceased partner’s ownership stake by the surviving partners or the business itself. The two can work together: key person insurance covers the business’s operating losses, while buy-sell insurance funds the legal transfer of ownership. Many partnerships have both.
Can a Small Business Get Key Person Insurance?
Yes. Small businesses and partnerships of any size can obtain key person insurance.
Eligibility doesn’t depend on how many employees you have or how long you’ve been in business. It depends on whether the partner is insurable—that is, whether they pass the insurance company’s underwriting review. The insurance company will ask health questions and evaluate the partner’s age, occupation, and medical history. Some applicants face higher premiums; others may be declined if the underwriting reveals serious health risks or other factors that make them uninsurable.
Your business must also have an insurable interest in the partner. This means the business must have a legitimate financial stake in the partner’s continued participation. For business partners, insurable interest is automatic: the partner’s death or disability directly harms the business. For employees, insurable interest must be documented—the business must show that losing that employee would cause direct financial loss.
Health questions are asked, and coverage depends on insurability. There are no exceptions to underwriting. No one is automatically approved for key person insurance.
Is Key Person Insurance Worth It?
Whether key person insurance makes sense depends on how much financial harm the partnership would suffer if a key partner died or became unable to work.
Ask yourself these questions:
- How much revenue does this partner generate or control?
- What client relationships would the partnership lose?
- What specialized expertise or knowledge does the partner hold?
- How much would it cost to hire and train a replacement?
- What debt obligations does the partnership have?
- How long would it take the business to recover from the partner’s absence?
If the answers suggest the partnership would face serious financial strain—or wouldn’t survive at all—then key person insurance is worth considering. The ongoing cost of premiums must be weighed against the financial risk. A CPA can help you quantify the potential loss and determine an appropriate coverage amount.
Many partnerships find the protection worth the expense, especially when a partner’s departure would threaten the business’s survival or force the surviving partners to work without income while rebuilding. But this is a business decision, not a guarantee of outcome. The value of insurance is protection against risk, not a promise that a particular event will or won’t occur.
Not sure what your next step is?
Talk it through with our team — we can walk you through how a situation like yours is usually handled and what your options are.
Term vs. Permanent Key Person Insurance for Partnerships
Term life insurance provides coverage for a set period—typically 10, 20, or 30 years. Premiums are lower than permanent insurance, but there’s no cash value. When the term ends, coverage expires unless you renew or convert to a permanent policy.
Whole life insurance (a type of permanent insurance) provides lifetime coverage. Premiums are higher, but the policy builds cash value over time. According to the NAIC Life Insurance Buyer’s Guide, permanent policies like whole life allow you to borrow against the cash value or surrender the policy for its cash value if your needs change.
When term makes sense: Your partnership has a defined time horizon, your partners are younger, or you’re prioritizing lower premiums. Term is also useful if you expect the need for key person insurance to decrease over time (for example, as the business matures and becomes less dependent on any single partner).
When whole life makes sense: Your partnership expects to operate long-term, your partners are older, or you want a permanent safety net that doesn’t expire. Whole life also builds an asset—the cash value—that can serve as an emergency reserve or be borrowed against if the business faces a cash crunch.
A CPA can help you evaluate the tax and cash flow implications of each option for your specific partnership structure and goals.
Who Is Not Eligible for Coverage Under Key Person Insurance?
Eligibility is determined during underwriting. The insurance company evaluates health, age, and occupation.
Applicants with serious health conditions, very advanced age, or high-risk occupations may face higher premiums, policy exclusions, or denial of coverage altogether. For example, a partner with a recent cancer diagnosis or a partner in their late 80s may be uninsurable or available only at a much higher cost.
The business must also have a legitimate insurable interest in the partner. If the partner’s death or disability wouldn’t cause direct financial loss to the business, the insurance company will deny the application.
Health questions are asked, and issue depends on insurability. No one is automatically approved for key person insurance, and there are no exceptions to the underwriting process.
Key Person Insurance and Cash Flow: A CPA’s Perspective
From a business tax and cash flow standpoint, key person insurance has several important features:
Premiums. The business pays premiums, which may be tax-deductible as a business expense. Consult a CPA about your specific situation—deductibility can depend on how the policy is structured and what state your business operates in.
Death benefit. When the business receives the death benefit, it’s generally excluded from the business’s gross income under federal tax law (26 U.S.C. § 101(a)). This means the death benefit is received tax-free by the business.
Cash flow during transition. The death benefit provides immediate cash to cover lost revenue, debt payments, and replacement hiring costs. This helps the business maintain operations and employee payroll during a critical period.
Whole life cash value. If you choose whole life insurance, the policy builds cash value over time. This cash value can serve as an emergency reserve or be borrowed against if the business faces a temporary cash shortage. The cash value is separate from the death benefit and can be accessed during the partner’s lifetime.
Structuring matters. The way you structure key person insurance—which partners are covered, how much coverage each has, term versus whole life, and how the death benefit will be used—should coordinate with your partnership agreement and overall business plan. A CPA can help ensure the structure supports your goals and complies with tax law.
Key Person Insurance vs. Buy-Sell Agreement Insurance
These are related but distinct protections.
Key person insurance protects the business from the financial impact of losing a partner. The death benefit goes to the business to cover operating losses, debt, and transition costs.
Buy-sell agreement insurance funds the purchase of a deceased partner’s ownership stake. When a partner dies, the surviving partners or the business use the death benefit to buy out the deceased partner’s heirs, ensuring a smooth transfer of ownership and preventing disputes.
Both can exist in the same partnership. Key person insurance covers the business’s general financial loss; buy-sell insurance funds the ownership transfer. A buy-sell agreement should be in place before buy-sell insurance is purchased. A CPA and an attorney should work together to structure both correctly, ensuring they complement each other and align with your partnership’s goals.
Under federal tax law (26 U.S.C. § 101(a)(2)), when a life insurance policy is transferred to a partner or partnership, the death benefit exclusion is preserved—a critical rule for buy-sell agreements. This is one reason why a CPA’s involvement in structuring buy-sell insurance is essential.
Have questions about what happened?
Ask our team directly. Tell us what you are dealing with and we will explain how the process works from here.
Getting Started: Coverage Review for Your Partnership
If your partnership depends on one or more partners whose death or disability would threaten the business, the first step is to clarify your situation.
Ask yourself: Which partners are truly key to the business? What would their loss cost in dollars and business continuity? How much coverage is needed? Does term or whole life make more sense for your partnership?
A coverage review with a CPA who understands business insurance can help you answer these questions. The review will consider your partnership structure, cash flow, existing debt, long-term goals, and the specific financial risks your partnership faces. You’ll leave with a clear picture of what key person insurance could do for your business and what the cost would be.
If your partnership faces the loss of a key partner and you’re unsure whether key person insurance is right for you, reach out. Many business partners in your situation have found that discussing their specific circumstances with a CPA brings clarity and confidence to the decision.
Why Key Person Insurance Matters for Your Partnership
Covers the Financial Gap
When a key partner dies or becomes disabled, the death benefit replaces lost income, covers operating expenses, and keeps the business stable during transition.
Owned and Controlled by Your Business
Your business owns the policy, names itself as beneficiary, and receives the death benefit directly—giving you immediate access to funds when you need them most.
Works with Buy-Sell Agreements
Key person insurance often pairs with buy-sell agreement insurance to fund the purchase of a deceased partner's share and ensure a smooth transition of ownership.
Protects Your Team and Clients
Adequate coverage allows your business to retain staff, honor client commitments, and maintain operations while you navigate the loss of a valued partner.
Key Person Insurance Is Not Life Insurance for the Individual
The business owns the policy, not the partner. The death benefit goes to the business to cover losses—not to the partner's family. This is a critical distinction for tax treatment and cash flow planning. A CPA can help you structure key person coverage as part of your overall business and estate strategy.
How Key Person Insurance Fits Your Business Structure
Professional Practices
Medical, dental, legal, and accounting firms rely on key person insurance to protect against the loss of a partner who brings in clients or manages operations.
Family Businesses
When a family member is essential to the business, key person insurance ensures the company can survive their loss and fund a smooth transition to the next generation.
Small to Mid-Size Partnerships
Any partnership where one or two partners are critical to revenue, client relationships, or day-to-day management benefits from key person coverage.
Buy-Sell Coordination
Key person insurance often funds buy-sell agreements, allowing the surviving partners to purchase the deceased partner's share at a predetermined price.
What NR CPAs & Business Advisors Brings to Key Person Insurance
CPA Perspective on Tax and Cash Flow
We help you structure key person insurance to align with your business's tax situation and cash flow needs—not just to cover a loss, but to strengthen your financial position.
Integration with Estate Planning
Key person insurance works alongside your business succession plan and personal estate strategy. We help ensure all pieces fit together.
Support for Indian-American Business Owners and Families
We understand the unique needs of Indian-American households and business owners across the United States, including multi-generational planning and family business transitions.
Serving Florida and Beyond
Based in Miami, we serve families and business owners across Florida—including Fort Lauderdale, West Palm Beach, Orlando, Tampa, and Jacksonville—and throughout the United States.


