What Is Service Revenue in Accounting and How Is It Recorded


Service revenue in accounting is the income a business earns by performing work for customers instead of selling physical goods. Service revenue is credited to an income account in the period the work is done, even when cash arrives later. Service revenue is neither an asset nor a liability, and the 5-step ASC 606 model sets its timing.
Key Takeaways
- Service revenue is an operating income account with a normal credit balance.
- Accrual books record service revenue when the work is performed, not when the client pays.
- Prepaid work sits in Unearned Service Revenue, a liability, until the service is delivered.
- Net service revenue equals gross service revenue minus discounts, refunds and allowances.
- Service revenue is taxed as ordinary business income, and self-employment tax runs 15.3% for sole proprietors.
What Is Service Revenue in Accounting?
Service revenue in accounting is the money a company earns from labor, expertise or time delivered to a customer. Service revenue is the first line on the income statement of a service business. Consulting fees, legal fees, repair charges, tuition and monthly retainers all count as service revenue.
Service businesses employ the majority of American workers. According to the Bureau of Labor Statistics (BLS), private service-providing industries held 71.6% of U.S. employment in 2025. Goods-producing industries held 13.6% of employment in the same BLS data.
Small firms produce a large slice of that service income. According to the U.S. Small Business Administration (SBA) Office of Advocacy, the country has 36.2 million small businesses. Those small businesses employ almost 46% of private-sector workers.
Each of those businesses reports service revenue on a tax return and on its books. Owners who post service revenue every month get cleaner monthly financial statements and fewer year-end corrections. Clean books start with the right account name for service revenue.
What Is Another Name for Service Revenue?
Another name for service revenue is fees earned, and some ledgers label the account service income or revenue from services. All of these names describe one income account. The account label changes by industry, while the accounting treatment stays the same.
The treatment does change once income comes from outside the core service. That split separates operating revenue from non-operating revenue.
Is Service Revenue Operating or Non-Operating Revenue?
Service revenue is operating revenue when the service is the company's core business activity. A consulting firm's advisory fees are operating revenue, while interest on its bank balance is non-operating revenue. Non-operating revenue comes from activities outside the main service line.
Non-operating revenue for a service company takes four common forms, listed below.
- Interest earned on business savings accounts or notes receivable.
- Rent collected from subleasing unused office space.
- Gains on the sale of equipment, vehicles or investments.
- Dividends from stock the business holds.
Lenders and buyers read operating revenue as the repeatable part of income. Operating revenue trends also drive pricing strategy for each service line. Non-operating income sits lower on a multi-step income statement, below operating income.
Operating service revenue still needs a timing rule. That timing rule comes from ASC 606.
When Is Service Revenue Recognized Under ASC 606?
Service revenue is recognized when the company satisfies a performance obligation by transferring the promised service to the customer. That recognition rule comes from Accounting Standards Codification (ASC) 606, issued by the Financial Accounting Standards Board (FASB). FASB built ASC 606 on a 5-step model that every service contract passes through.
- Identify the contract with the customer.
- Identify each performance obligation in the contract.
- Determine the transaction price.
- Allocate the transaction price to each performance obligation.
- Recognize revenue as each performance obligation is satisfied.
The 5 steps appear in the graphic below, in the same order FASB lists them.

According to FASB, ASC 606 took effect for public companies in annual reporting periods beginning after December 15, 2017. Private companies adopted the same standard in later reporting periods. The standard applies to every service contract, from a one-hour repair to a 3-year retainer.
Is Service Revenue Recognized Over Time or at a Point in Time?
Service revenue is recognized over time when the customer receives the benefit while the work happens. A 12-month bookkeeping retainer is recognized over time, one-twelfth each month. A one-day equipment repair is recognized at a point in time, on the day the repair is finished.
Timing follows the delivery of the service, not the arrival of cash. Subscription software, managed IT and annual support plans follow the over-time pattern. SaaS founders see this pattern in every annual contract they sign.
The delivery date also decides which side of the ledger the entry touches. That ledger side is the next question for service revenue.
Is Service Revenue a Debit or a Credit?
Service revenue is a credit, because revenue increases owner's equity and equity accounts carry a normal credit balance. The normal balance of service revenue is a credit. The matching debit goes to Cash or to Accounts Receivable.
The accounting equation reads Assets = Liabilities + Equity. A credit to service revenue raises equity, and the debit to Cash raises assets by the same amount. The equation stays balanced after both sides post.
Service revenue is a temporary account, also called a nominal account. Temporary accounts close to retained earnings at the end of each fiscal year. The service revenue balance then restarts at zero for the next year, one journal entry at a time.
What Is the Journal Entry for Service Revenue?
The journal entry for service revenue debits Cash or Accounts Receivable and credits Service Revenue. The debit side changes with payment timing, while the credit side stays Service Revenue once the work is done. The table below lists 5 common service revenue entries in 5 rows and 4 columns.
| Situation | Debit | Credit | Effect on the books |
|---|---|---|---|
| Client pays at the time of service | Cash | Service Revenue | Asset up, income up |
| Service done, invoice sent on account | Accounts Receivable | Service Revenue | Receivable up, income up |
| Client pays the open invoice | Cash | Accounts Receivable | One asset swaps for another |
| Client prepays before the work | Cash | Unearned Service Revenue | Liability up, no income yet |
| Prepaid work is completed | Unearned Service Revenue | Service Revenue | Liability down, income up |
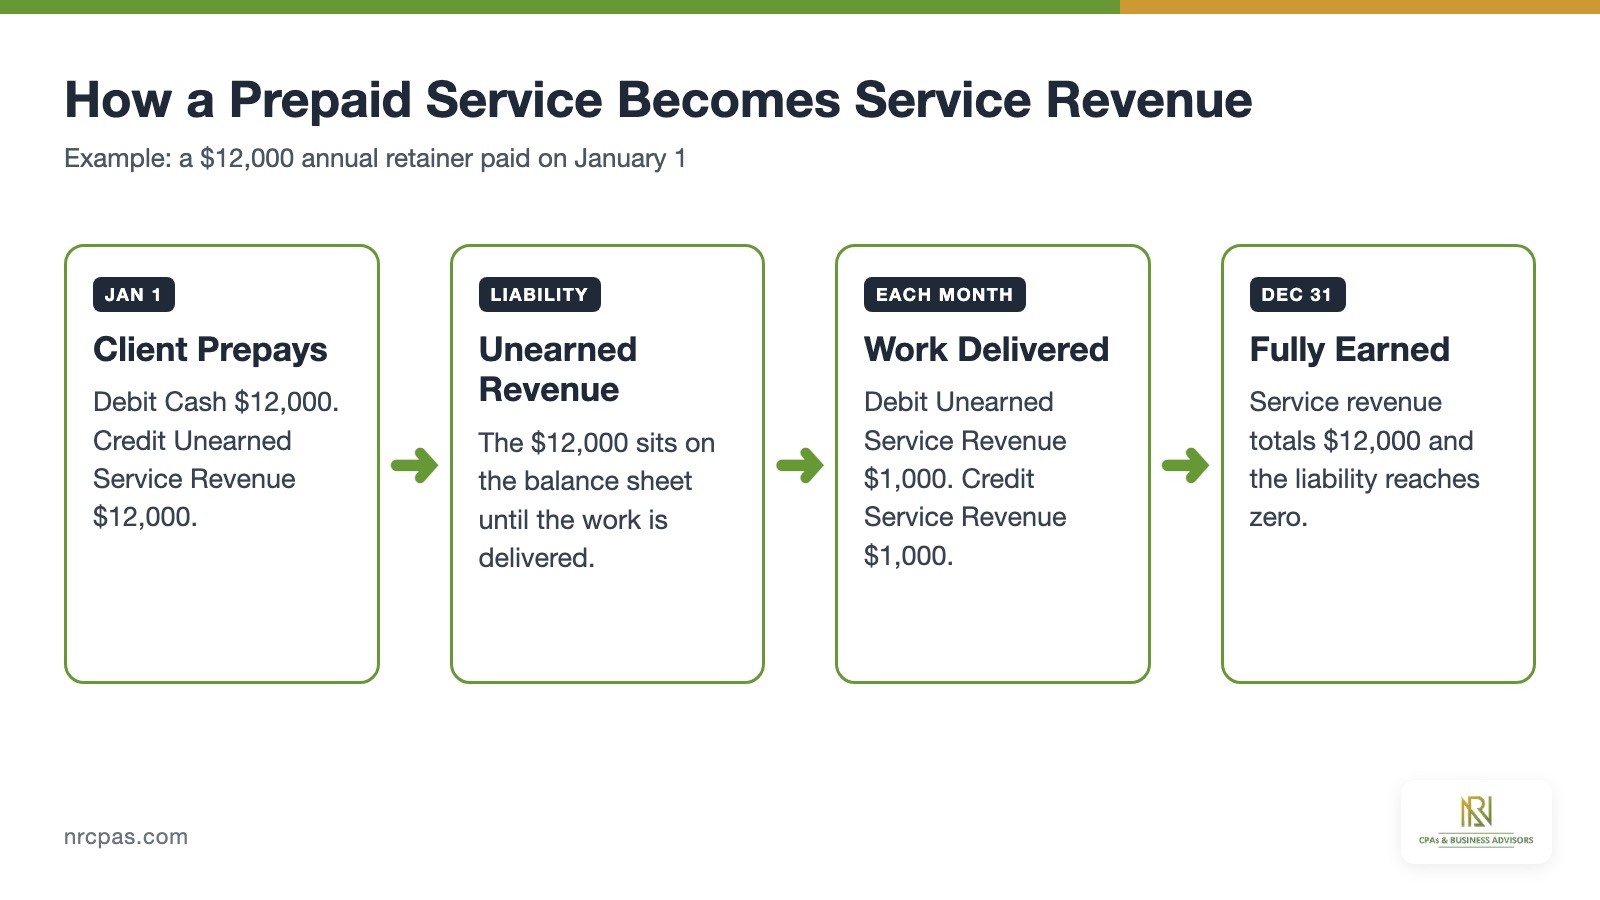
Each row keeps total debits equal to total credits. The prepaid rows show why cash and service revenue can land in different months, as the flow graphic below traces.
How Do You Record Service Revenue on Account?
Record service revenue on account by debiting Accounts Receivable and crediting Service Revenue on the day the service is complete. A firm that finishes a $4,000 audit on March 28 books $4,000 of March revenue.
The March revenue stays in March even when the client pays on April 20. The April payment debits Cash and credits Accounts Receivable for $4,000. Slow receivables turn booked revenue into cash shortfalls, so aging reports matter as much as the entry.
How Do You Record Unearned Service Revenue?
Record unearned service revenue as a liability when a client pays before the work is performed. A $12,000 annual retainer paid on January 1 credits Unearned Service Revenue for $12,000. Each month, $1,000 moves from Unearned Service Revenue into Service Revenue. The liability reaches zero after the twelfth monthly entry.
How Do You Record Accrued Service Revenue?
Record accrued service revenue with an adjusting entry when work is done but not yet billed at period end. The adjusting entry debits Accrued Revenue, an asset, and credits Service Revenue.
Accrued revenue keeps December work inside December results. The accrual reverses once the January invoice goes out. An outsourced CFO usually owns this step during the month-end close.
Accrued Revenue and Unearned Service Revenue are balance sheet accounts. Those two accounts explain a common question about service revenue itself.
Is Service Revenue an Asset or a Liability?
Service revenue is neither an asset nor a liability, because service revenue is an income account reported on the income statement. Service revenue creates an asset, either Cash or Accounts Receivable, but the revenue itself is not an asset. Unearned Service Revenue is the only related account that sits in liabilities.
Does Service Revenue Go on the Balance Sheet?
No, service revenue does not go on the balance sheet directly, because service revenue belongs on the income statement. Accounts Receivable, Accrued Revenue and Unearned Service Revenue do appear on the balance sheet. Net income from service revenue reaches the balance sheet through retained earnings.
How Does Service Revenue Affect Owner's Equity?
Service revenue increases owner's equity by raising net income, which closes into retained earnings or the owner's capital account. A sole proprietor with $90,000 of service revenue and $30,000 of expenses adds $60,000 to equity.
Higher service revenue raises equity only after expenses are covered. The equity account name depends on the entity setup, such as an LLC capital account or corporate retained earnings. Net income itself is calculated on the income statement.
Where Does Service Revenue Appear on the Income Statement?
Service revenue appears at the top of the income statement as the first revenue line. Net service revenue equals gross service revenue minus discounts, refunds and allowances. A multi-step income statement then subtracts cost of services to reach gross profit.
Cost of services covers direct labor, subcontractors and software used to deliver the work. Operating expenses, interest and income taxes follow below gross profit. Accurate income statement preparation keeps each of those lines in its correct place. The top revenue line itself comes from a short calculation.
How Do You Calculate Service Revenue?
Calculate service revenue by multiplying the units of service delivered by the price per unit, then subtracting discounts and refunds. Three formulas cover common billing models, and the list below shows each one.
- Hourly billing service revenue equals the hourly rate times billable hours.
- Project billing service revenue equals completed projects times the flat project fee.
- Subscription billing service revenue equals active clients times the monthly fee.
A design studio that bills 1,200 hours at $95 per hour earns $114,000 in gross service revenue. The studio grants $4,000 in discounts and $2,000 in refunds. Net service revenue for the studio equals $108,000.
What Percentage of Total Revenue Comes From Services?
The percentage of total revenue that comes from services equals service revenue divided by total revenue, times 100. A company with $2 million of service revenue and $5 million of total revenue earns 40% from services. The service percentage shows how much the business depends on services versus products.
That dependence on services also changes how the business reports and pays tax.
What Else Affects How Service Revenue Is Reported and Taxed?
Service revenue reporting is also shaped by product comparisons, tax forms, accounting methods and record rules. The sections below answer each of those side topics in short form.
What Is the Difference Between Service Revenue and Sales Revenue?
Service revenue comes from performing work, while sales revenue comes from selling physical goods. Sales revenue carries inventory and cost of goods sold, while service revenue carries cost of services and no inventory. The comparison graphic below lines up both revenue types.

How Is Service Revenue Taxed?
Service revenue is taxed as ordinary business income on the owner's or the entity's return. According to the Internal Revenue Service (IRS), sole proprietors report gross receipts on line 1 of Schedule C. S corporations use Form 1120-S, and partnerships use Form 1065.
According to the IRS, net self-employment earnings of $400 or more trigger self-employment tax. The self-employment tax rate is 15.3%, made of 12.4% Social Security and 2.9% Medicare. The Social Security portion applies to the first $176,100 of 2025 earnings.
The IRS adds a 0.9% Additional Medicare Tax on earnings above $200,000 for single filers. Single-member owners can compare LLC self-employment rules before choosing an entity.
Can a Service Business Use the Cash Method for Taxes?
Yes, a service business can use the cash method for taxes, unless it is a C corporation above the receipts limit. According to the IRS, the Section 448 limit is $31 million of average annual gross receipts for 2025 tax years.
Cash-method books record service revenue when payment arrives, not when the work is done. Section 448 also covers partnerships that have a C corporation partner. Switching methods requires Form 3115, so accounting method choice belongs in early planning.
Which 1099 Forms Report Service Revenue?
Form 1099-NEC and Form 1099-K report service revenue paid to a business by clients and payment platforms. According to the IRS, clients file Form 1099-NEC for service payments of $600 or more made during 2025.
The One Big Beautiful Bill Act raised the 1099-NEC threshold to $2,000 for payments made on or after January 1, 2026. The same law set the 1099-K threshold at $20,000 and 200 transactions. Every dollar of service revenue is taxable, with or without a 1099 form.
Gaps between reported 1099 totals and a return trigger IRS mismatch notices, such as the CP2000. Reconciling 1099 forms to the revenue ledger each January prevents that mismatch.
Does Service Revenue Qualify for the QBI Deduction?
Yes, service revenue can qualify for the 20% qualified business income (QBI) deduction, unless a specified service trade exceeds the limits. According to the IRS, specified service trades include health, law, accounting, consulting and financial services.
Owners below the taxable income threshold keep the full QBI deduction on service income. The rules for specified service trades phase the deduction out above that threshold.
How Long Should Service Revenue Records Be Kept?
Service revenue records should be kept for at least 3 years from the filing date, according to the IRS. The IRS extends that period to 6 years when unreported income exceeds 25% of the gross income shown. Bad debt claims need 7 years of records.
Invoices, contracts, deposit records and 1099 forms all belong in the service revenue file. Those records also back up every service revenue journal entry during an IRS review.
How Do Clean Service Revenue Records Help a Growing Business?
Clean service revenue records help a growing business price services, plan taxes and borrow on accurate numbers. We build monthly revenue schedules, deferred revenue roll-forwards and tax-ready statements for service firms.
The team at NR CPAs works with consultants, agencies, clinics and other service businesses across the country. The firm is led by founder Nischay Rawal, CPA, EA. Reach the office at (305) 872-3096.
Service revenue reports grow more useful once they follow accrual-basis reporting every month.